Illinois Loan Modification Agreement
Overview of this form
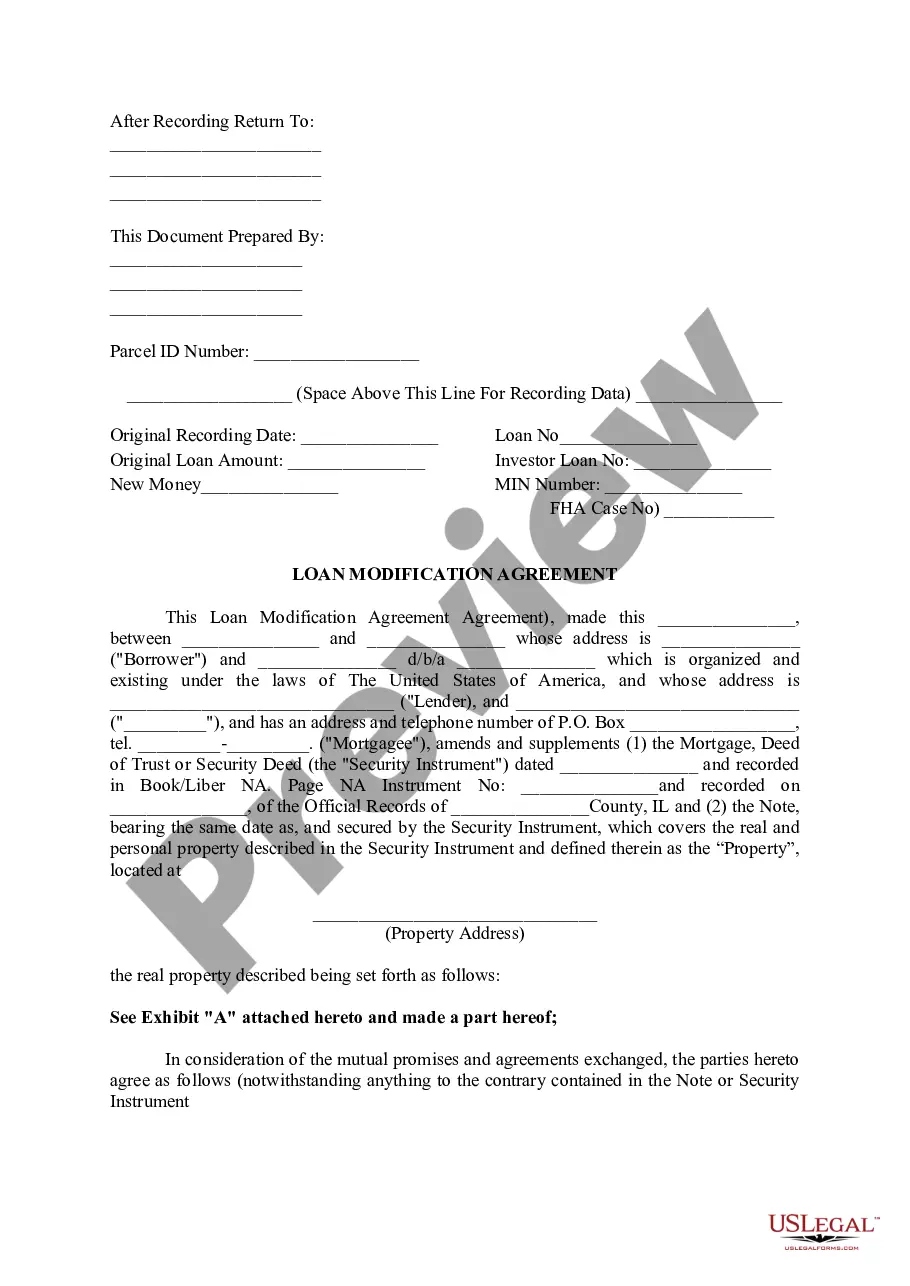
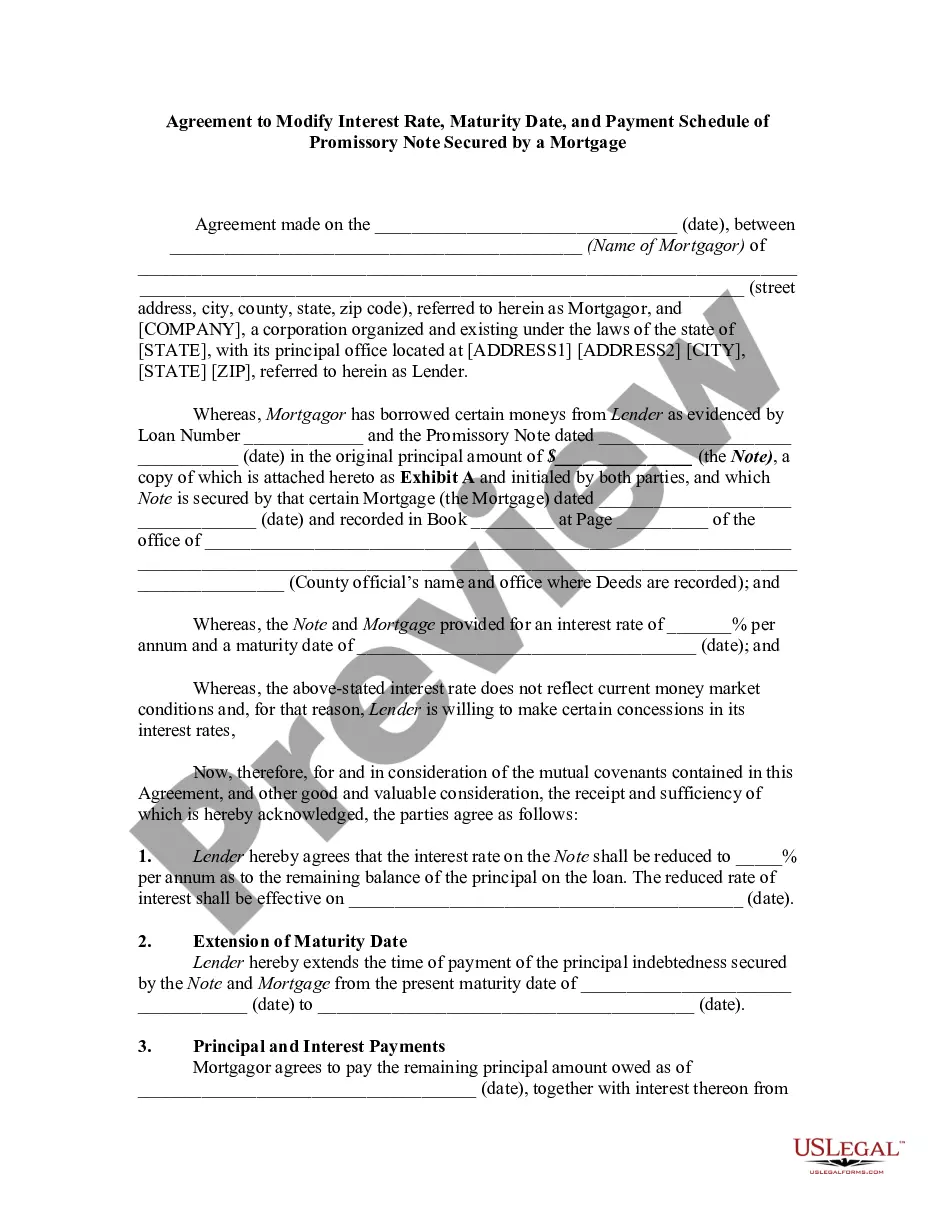
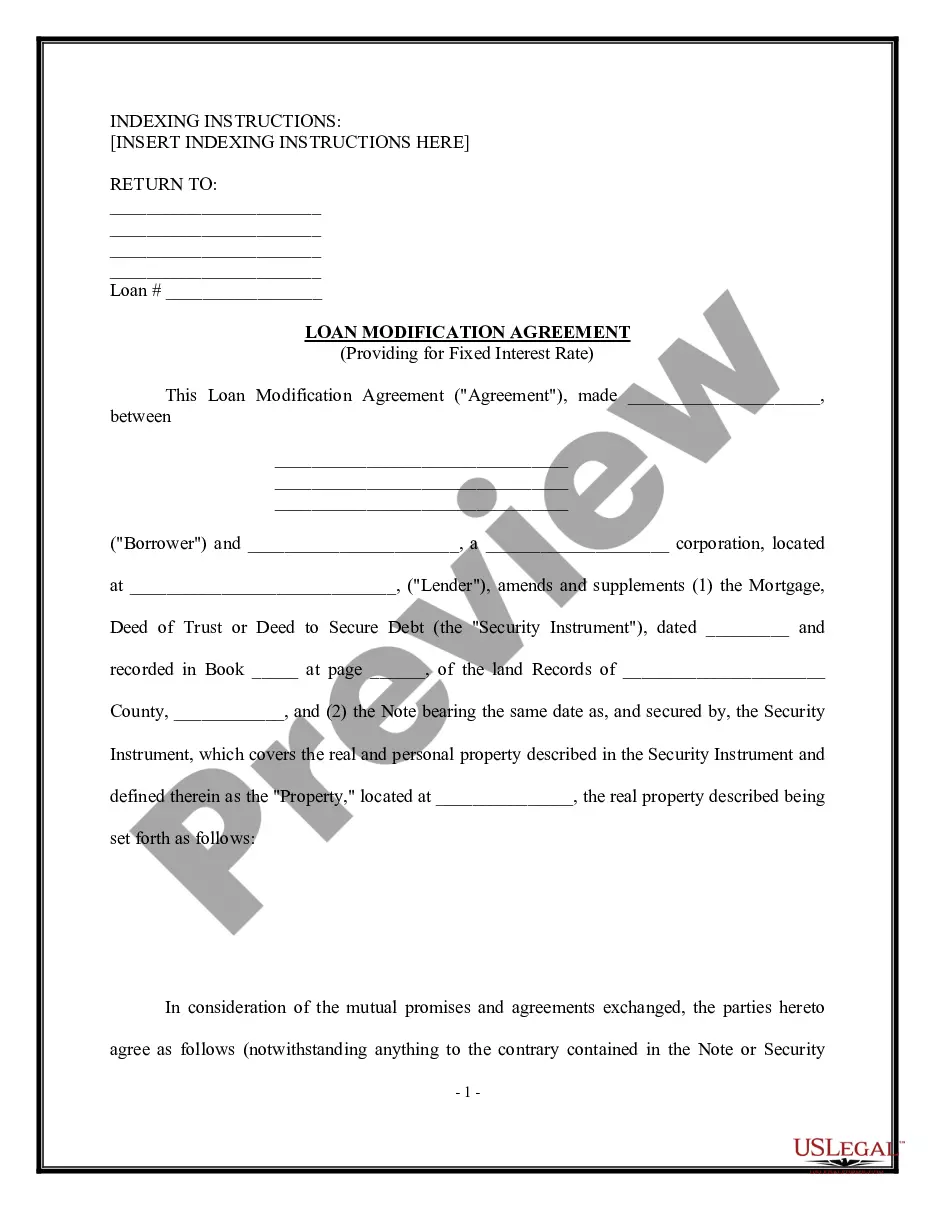
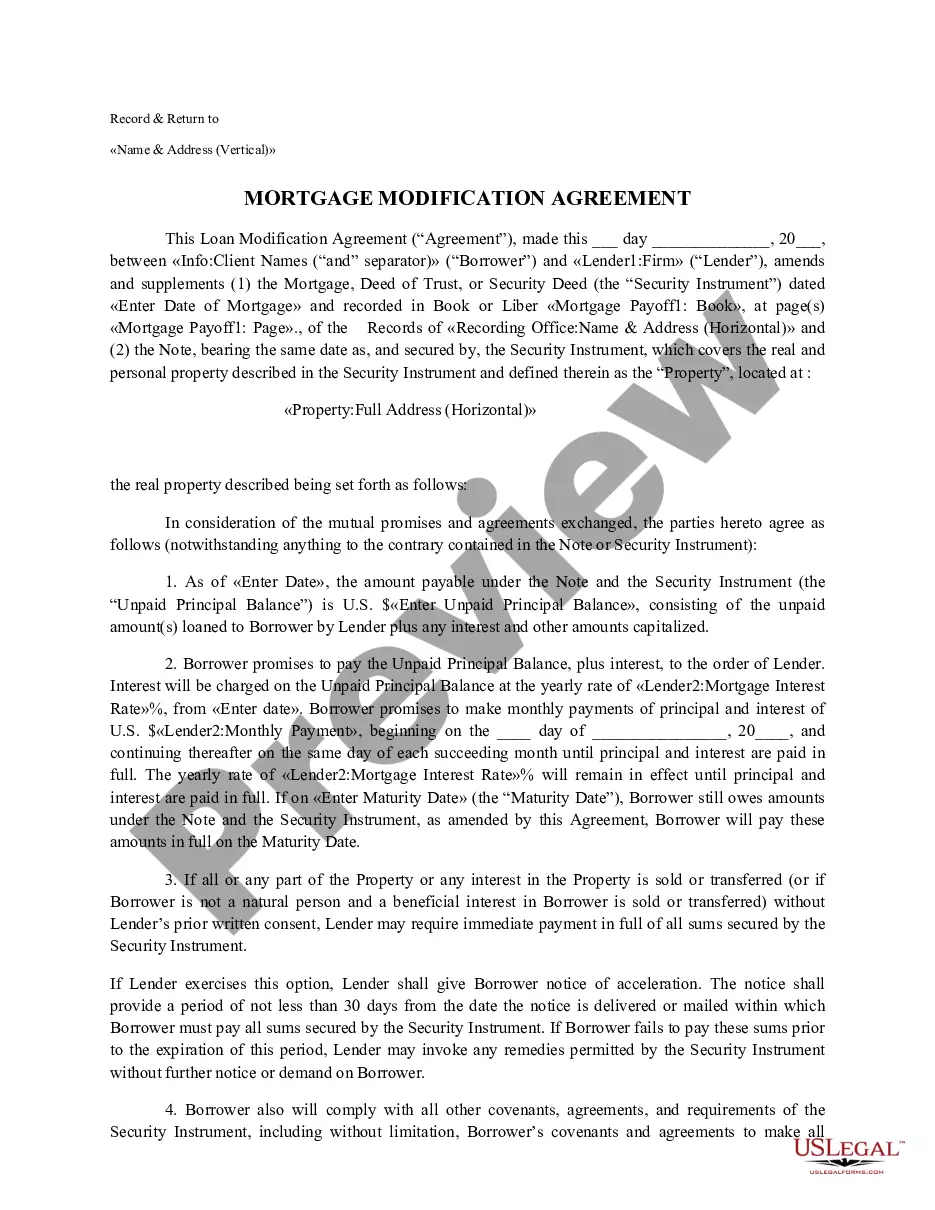
The Loan Modification Agreement is a legal document that allows a borrower and a lender to amend the terms of an existing mortgage or loan. It facilitates changes to the repayment terms, interest rates, or payment schedules, helping borrowers manage their mortgage more effectively. This form differs from refinance agreements as it modifies the current loan without requiring a new loan application or closing process.
Key parts of this document
- Identification of parties involved (borrower and lender).
- Details about the original loan and modification terms.
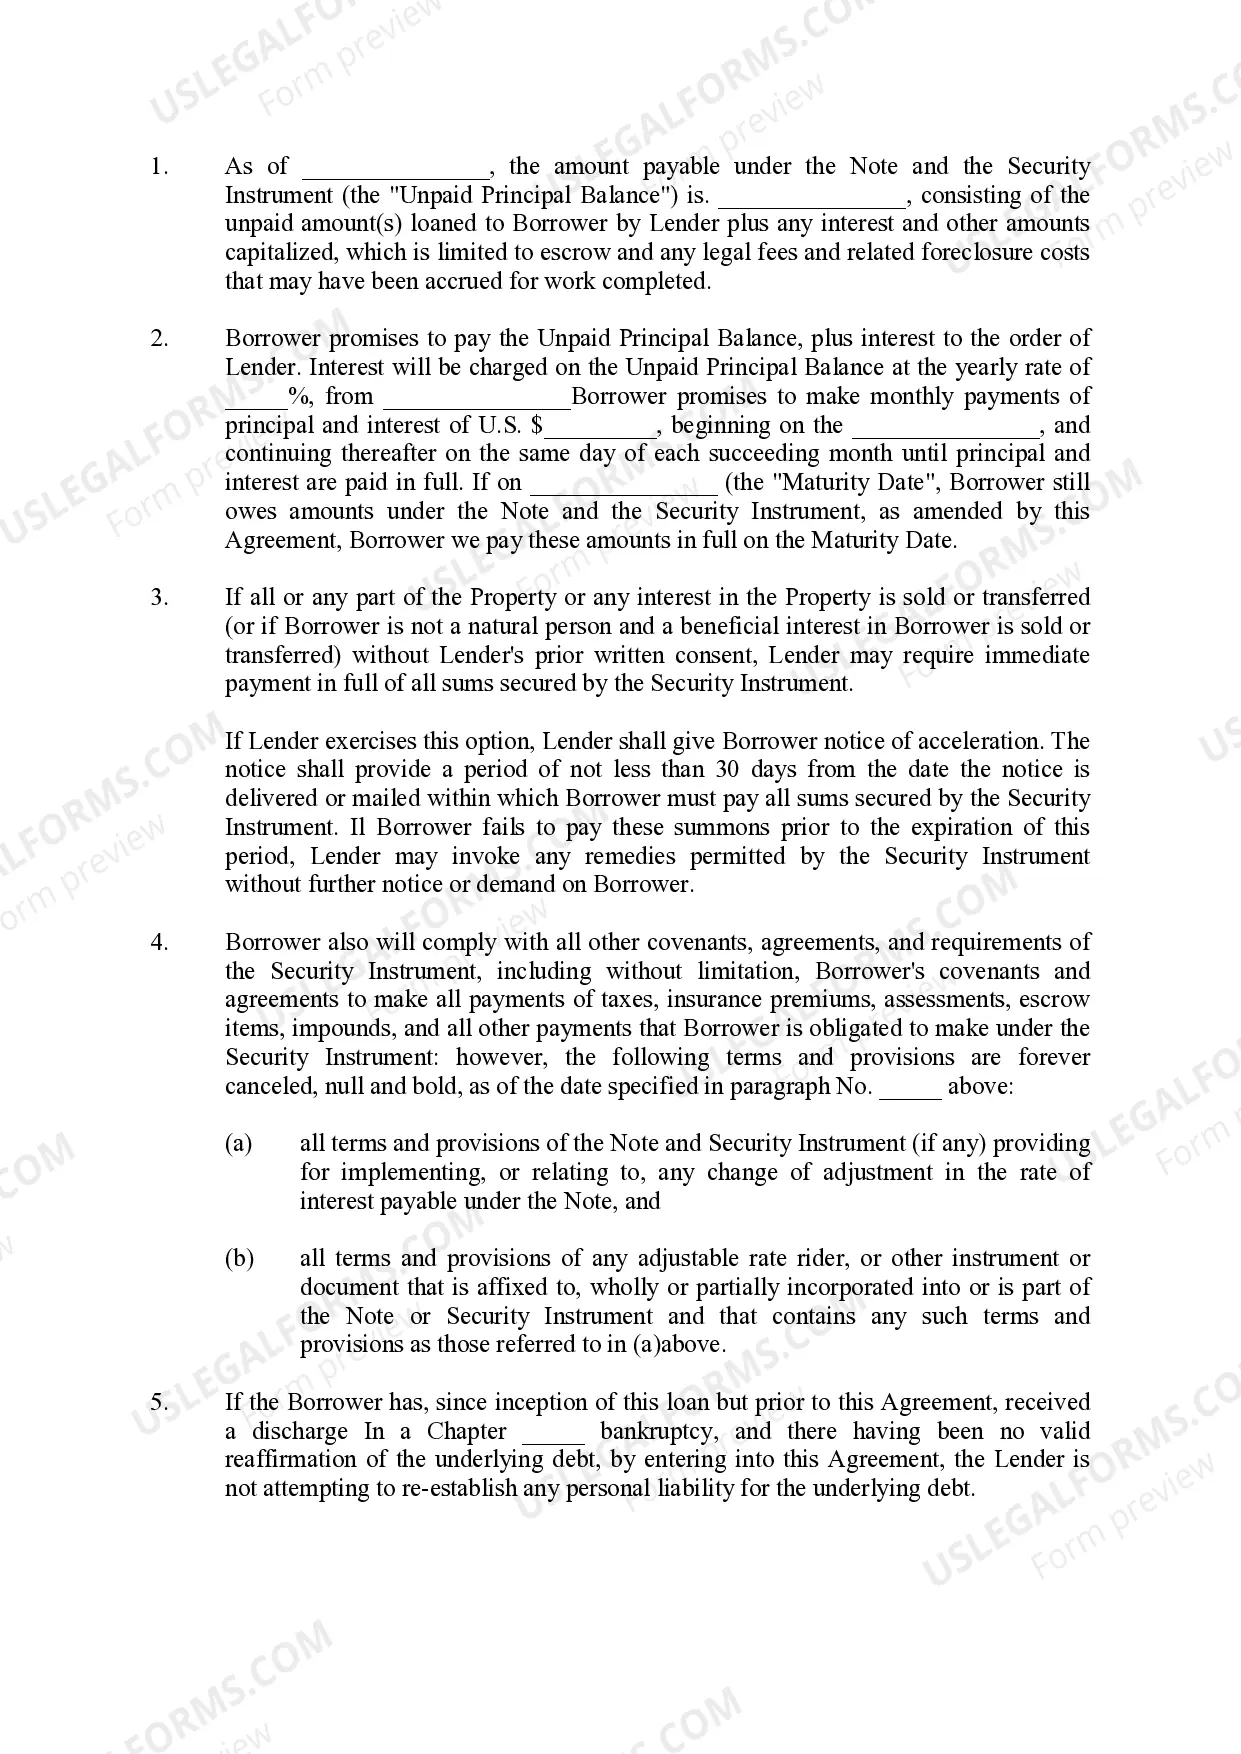
- New payment structure and interest rates.
- Clauses addressing property sale or transfer conditions.
- Provisions regarding compliance with the existing security instrument.
- Notary acknowledgment section to validate the agreement.


Situations where this form applies
This form should be used when a borrower needs to alter the existing mortgage terms due to financial hardship, a shift in interest rates, or a desire for a lower monthly payment. It is particularly useful in situations where homeowners are struggling to keep up with payments and are seeking a legal way to change the terms of their mortgage to avoid foreclosure.
Intended users of this form
- Homeowners looking to modify their existing loan terms.
- Lenders granting modifications to improve borrower repayment ability.
- Legal representatives acting on behalf of borrowers or lenders.
- Individuals who have previously filed for bankruptcy and want to clarify their loan obligations.
Steps to complete this form
- Identify the parties involved: Fill in the names and addresses of both the borrower and the lender.
- Specify the original loan details: Provide the original loan amount, date, and relevant recording information.
- Enter the new terms: Include the modified payment amount, interest rate, and payment schedule.
- Review and initial any changes to terms previously agreed upon in the original security instrument.
- Sign and date the form in the presence of a notary public to ensure legal validity.
Does this form need to be notarized?
Yes, this form must be notarized to be legally valid. US Legal Forms offers integrated online notarization, providing a secure video call option available 24/7, ensuring convenience without the need for travel.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Avoid these common issues
- Failing to include all necessary parties in the agreement.
- Leaving important fields, such as loan amounts and interest rates, blank or incorrectly filled.
- Not obtaining the required notarization of the document.
- Overlooking the clauses that affect both borrower rights and lender remedies.
Why use this form online
- Convenient access from anywhere, allowing users to complete the form at their own pace.
- Editability enables customization for specific needs and circumstances.
- Reliability, as the document is drafted by licensed attorneys to ensure legal compliance.
Looking for another form?

Form popularity
FAQ
Yes, probably. In California, a law called the Homeowner Bill of Rights (HBOR) generally gives borrowers the right to appeal a modification denial. Under HBOR, in most cases, if the servicer denies a borrower's application to modify a first lien loan, the borrower can appeal.
A loan modification is a change that the lender makes to the original terms of your mortgage, typically due to financial hardship. The goal is to reduce your monthly payment to an amount that you can afford, which you can achieve in a variety of ways.
Some of the most common types of hardship are: job loss, pay reduction, underemployment, declining business revenue, death of a coborrower, illness, injury, and divorce.
A lender may agree to a loan modification during a settlement procedure or in the case of a potential foreclosure.A loan modification agreement is a long-term solution. A loan modification may involve a reduced interest rate, a longer period to repay, a different type of loan, or any combination of these.
The loan modification underwriter will analyze and review the particular circumstances which justify a loan modification. The underwriter will evaluate and assess the borrower's financial status, current income and asset situation and ability to pay.
When you've successfully completed your trial modification payments, your mortgage loan servicer will send you a loan modification agreement. That agreement needs to be signed by you, stamped and signed by a notary, and sent back to your servicer.Some banks even offer a notary who will come to your home.
Be at least one regular mortgage payment behind or show that missing a payment is imminent. Provide evidence of significant financial hardship, for reasons such as:
Suspend past due amounts. Bring your account current. Adjust your interest rate. Lower your minimum payments. Modify your loan. Agree to a short sale of a home. Consider a settlement option.