Vermont Living Trust for Husband and Wife with One Child
What this document covers
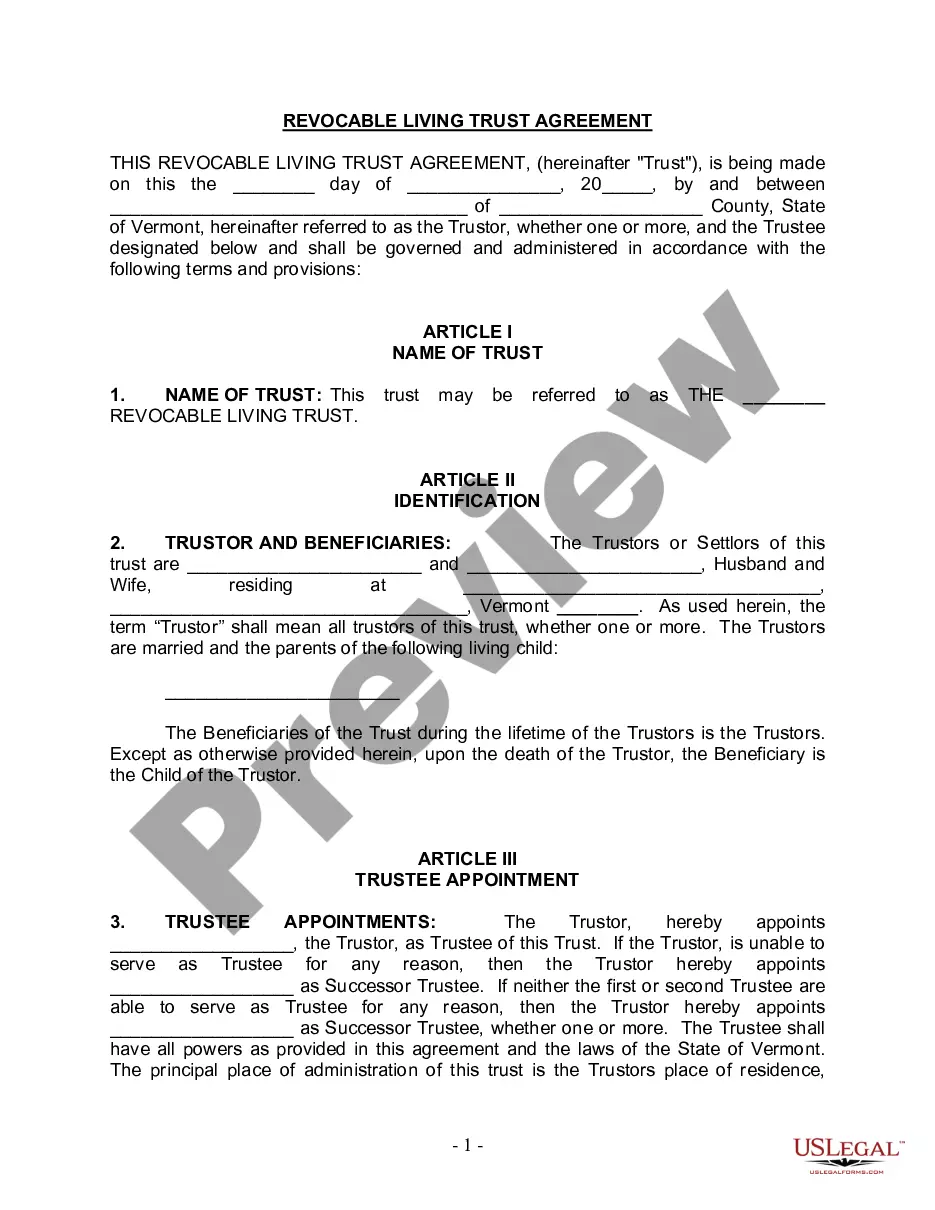
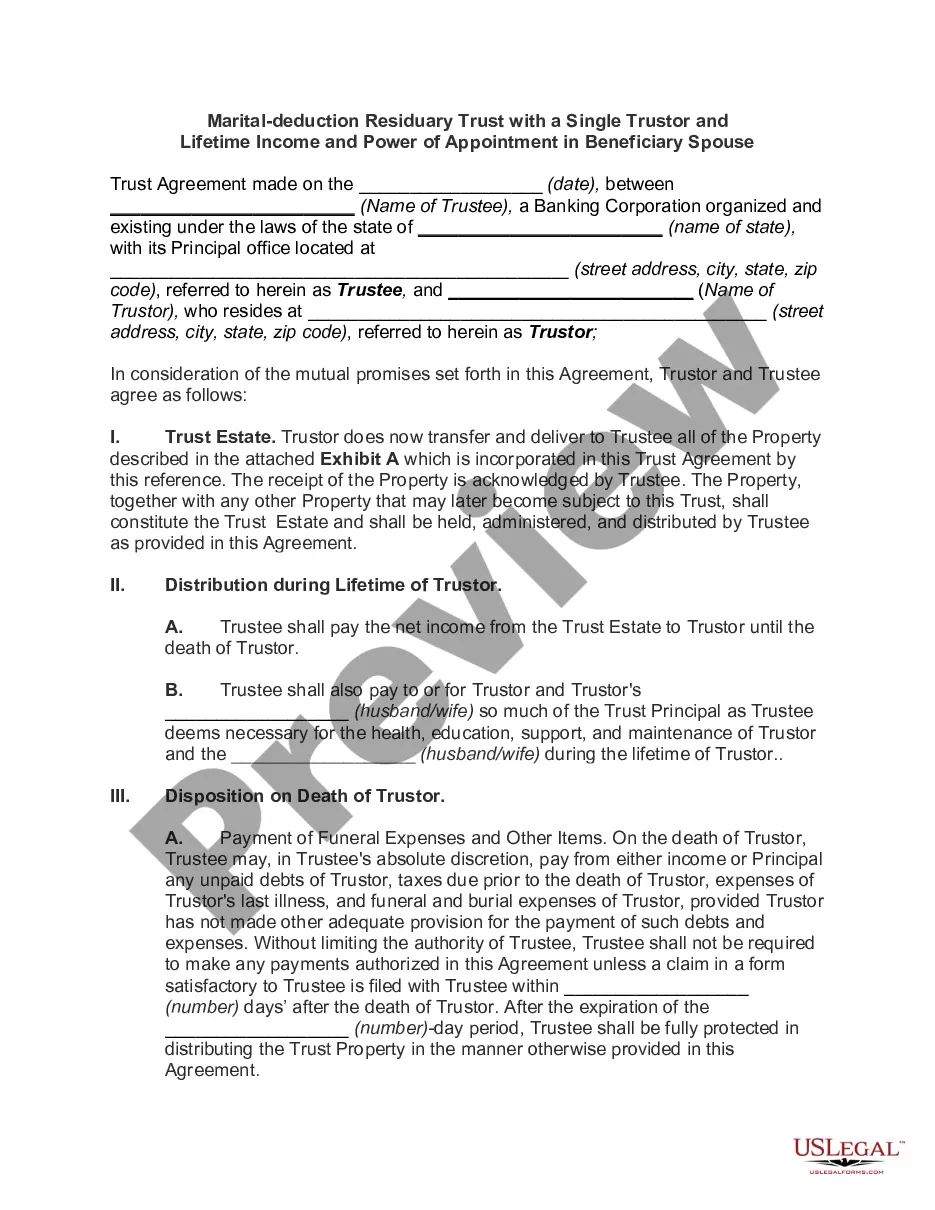
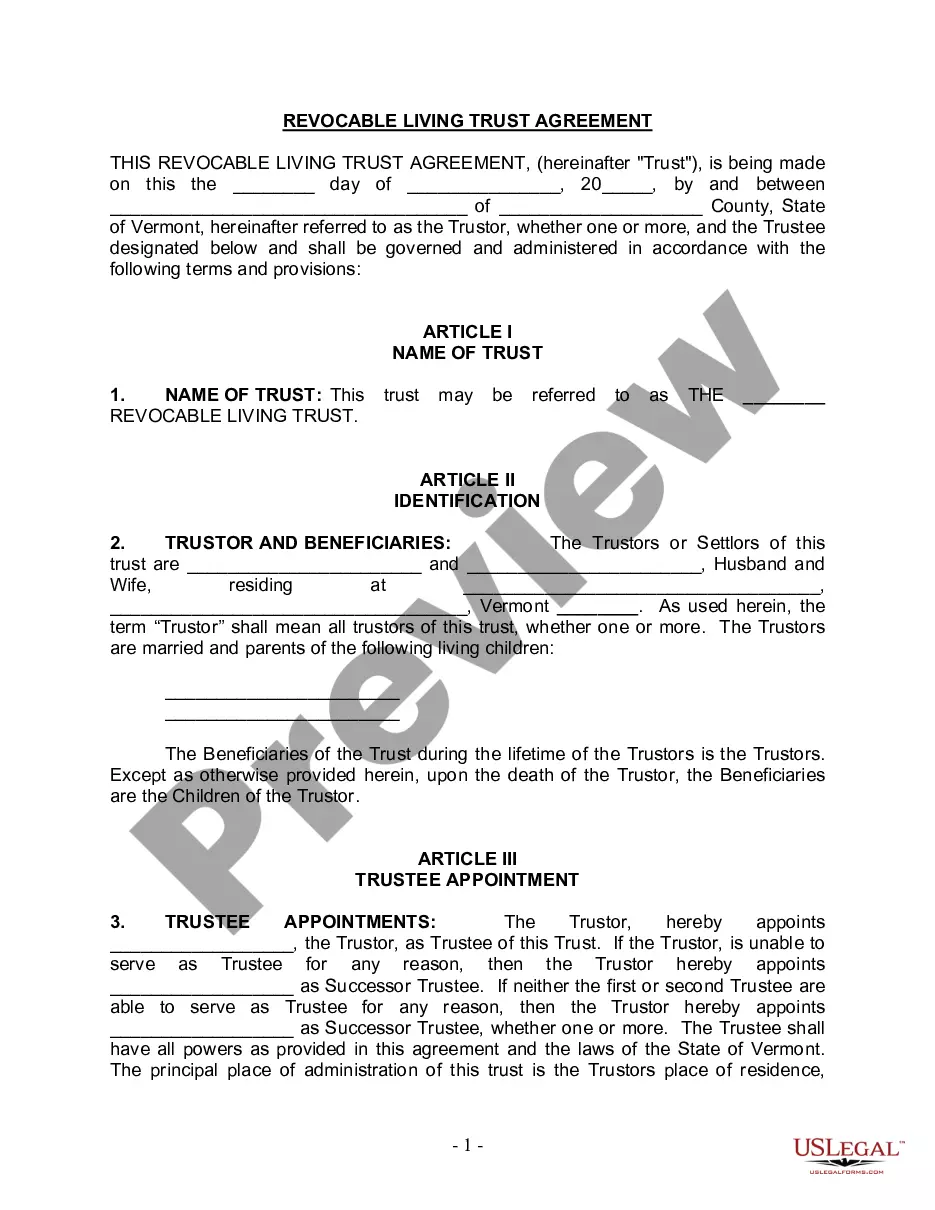
The Living Trust for Husband and Wife with One Child is a legal document that establishes a revocable living trust specifically designed for a married couple who have one child. This form serves the purpose of managing the couple's assets during their lifetime and efficiently transferring those assets to their child upon their death, bypassing the probate process. Unlike a will, which only takes effect after death, this living trust allows the creators to retain control over their assets and provide for their family's needs while they are still living.
What’s included in this form
- Name of Trust: Identifier for the trust created by the couple.
- Trustors and Beneficiaries: Names of the husband and wife as trustors and their child as the primary beneficiary.
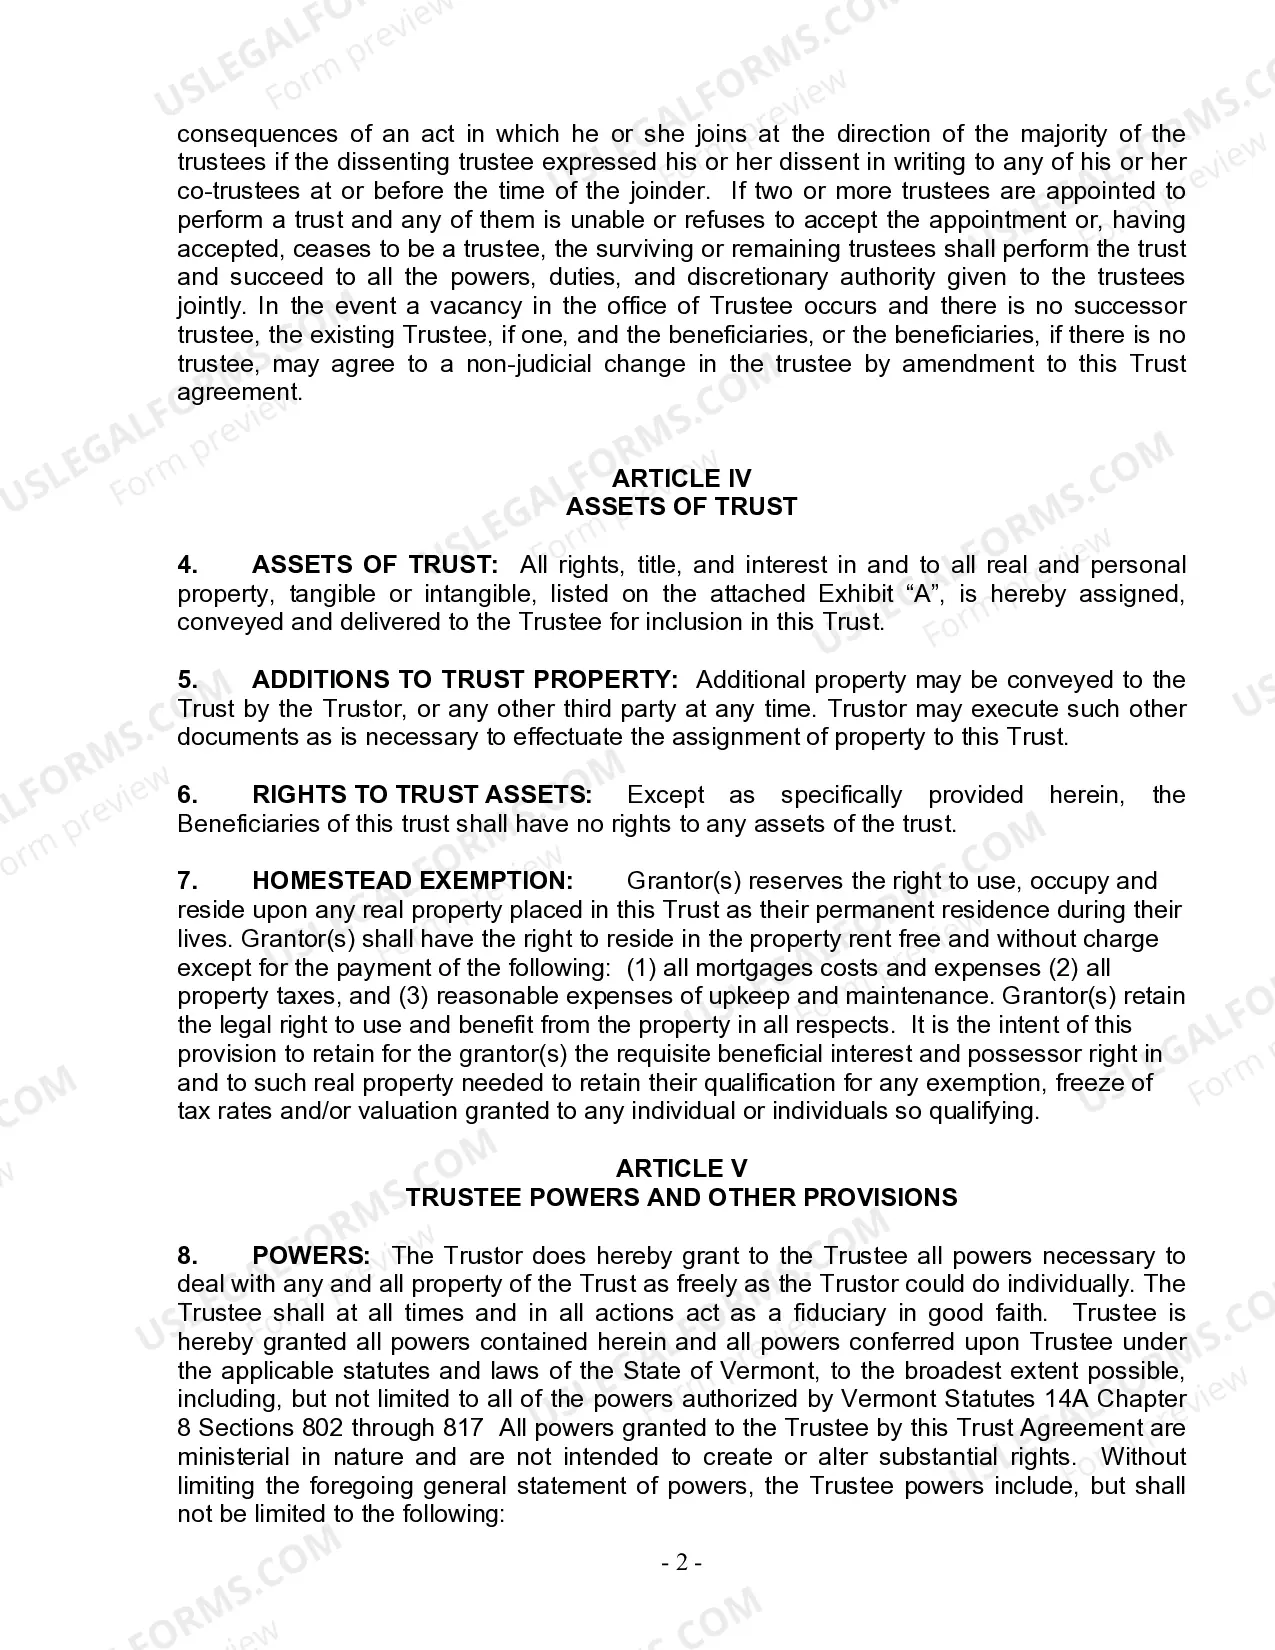
- Assets of Trust: Includes a detailed list of properties and assets placed under the trust.
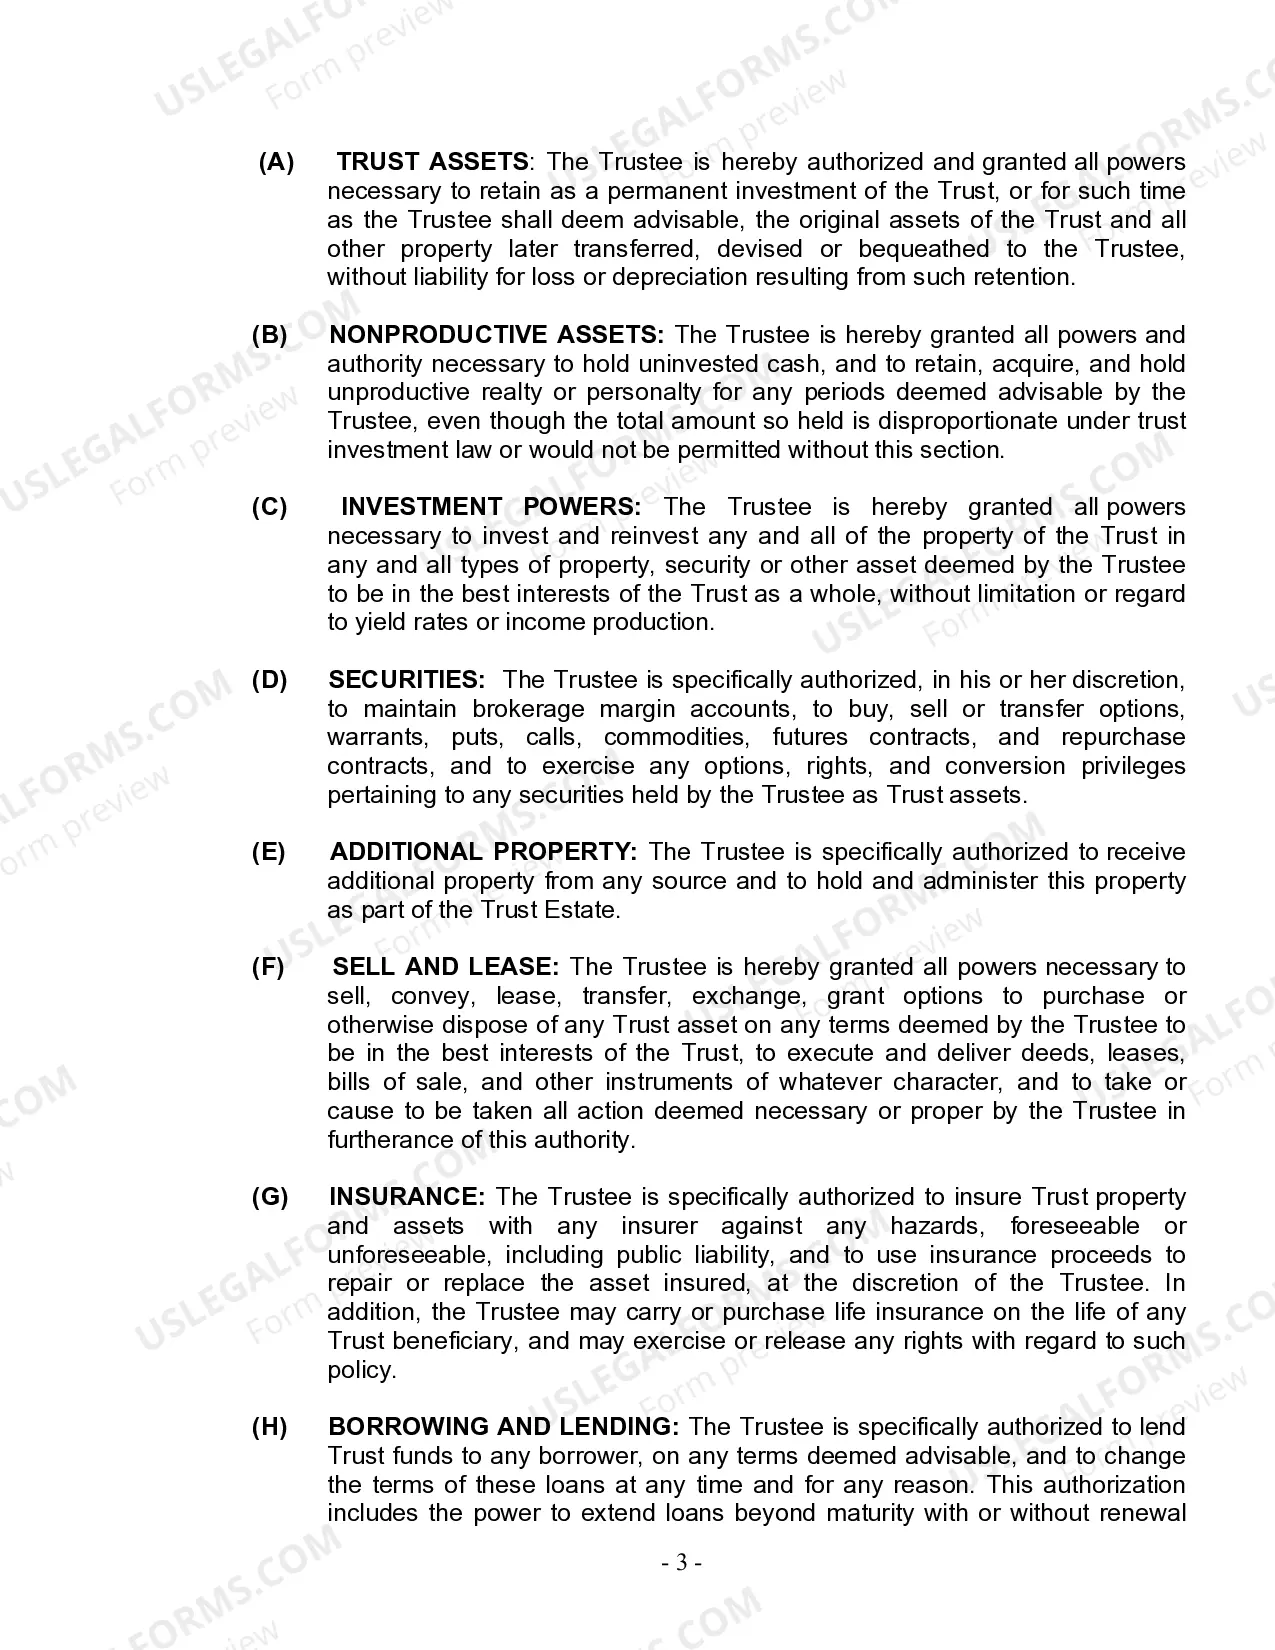
- Trustee Powers: Defines the powers granted to trustees for managing trust assets and disbursing funds.
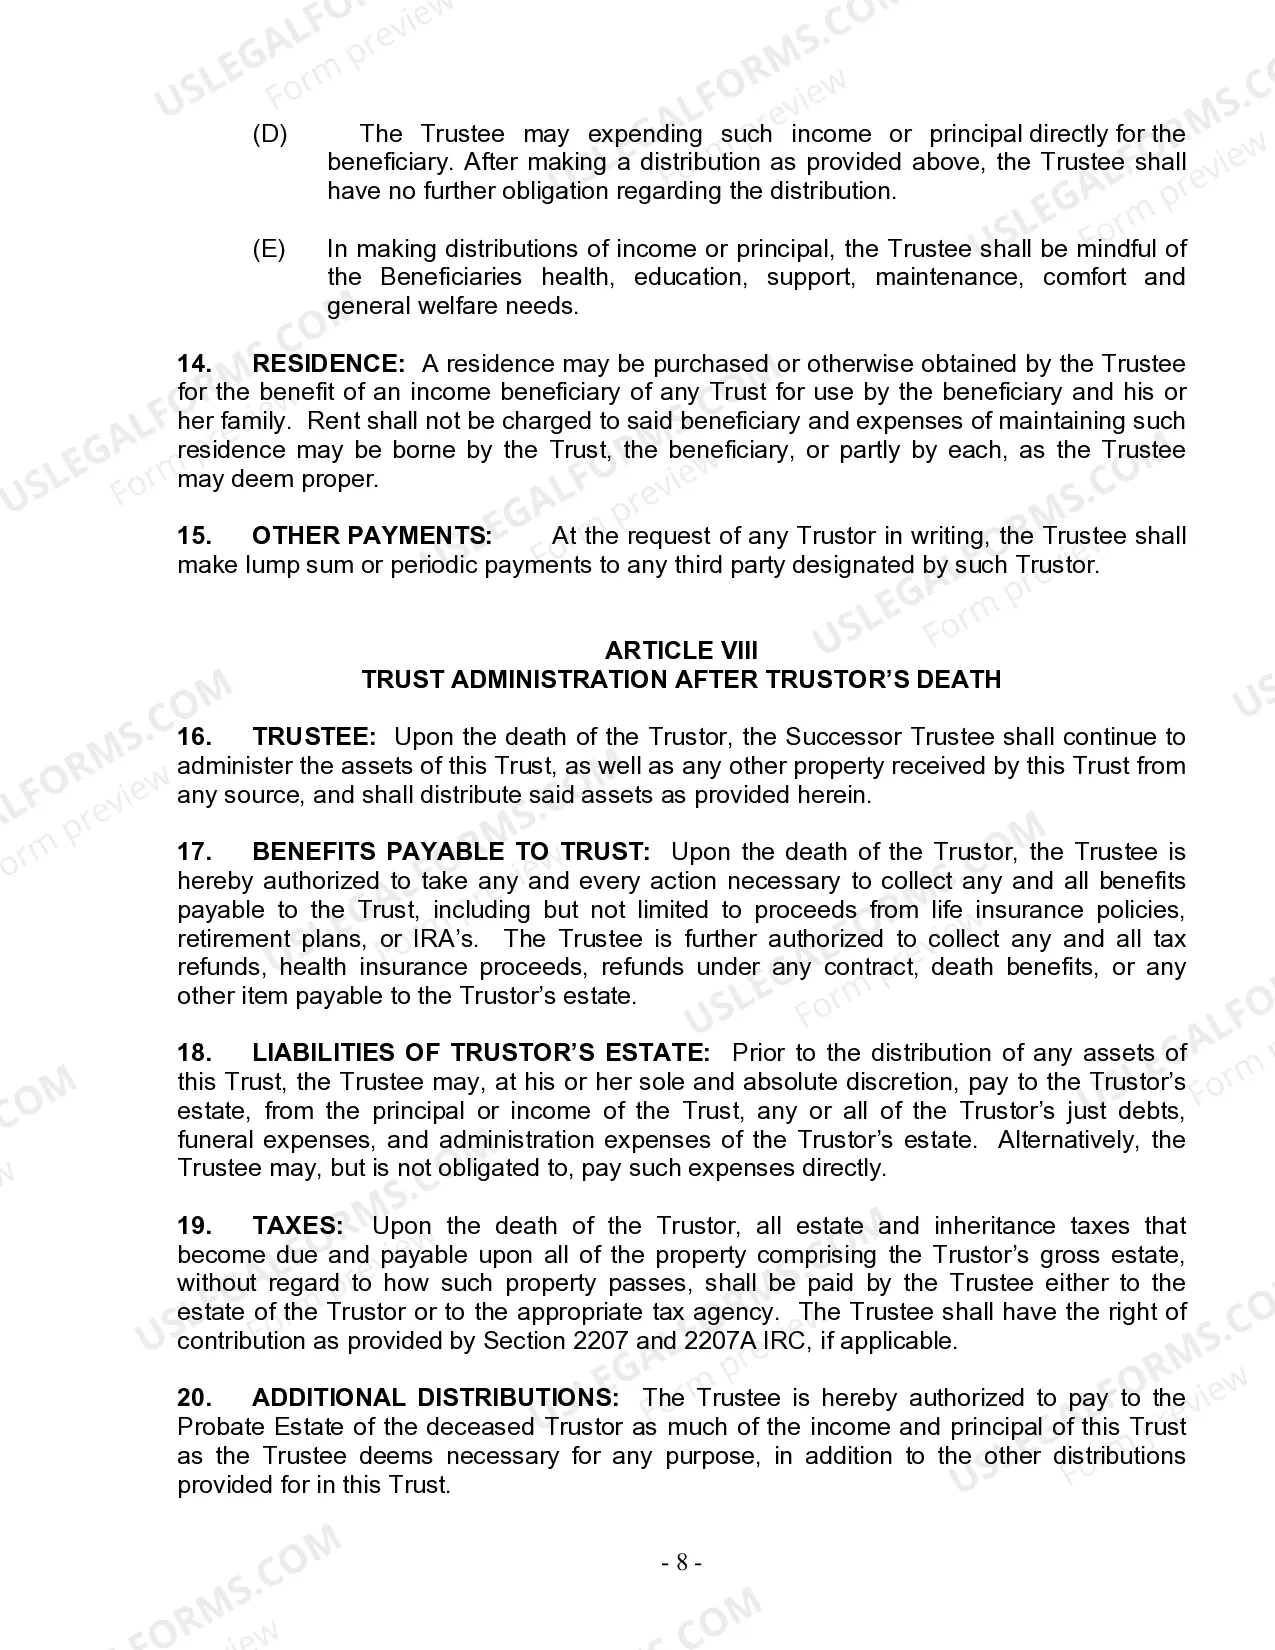
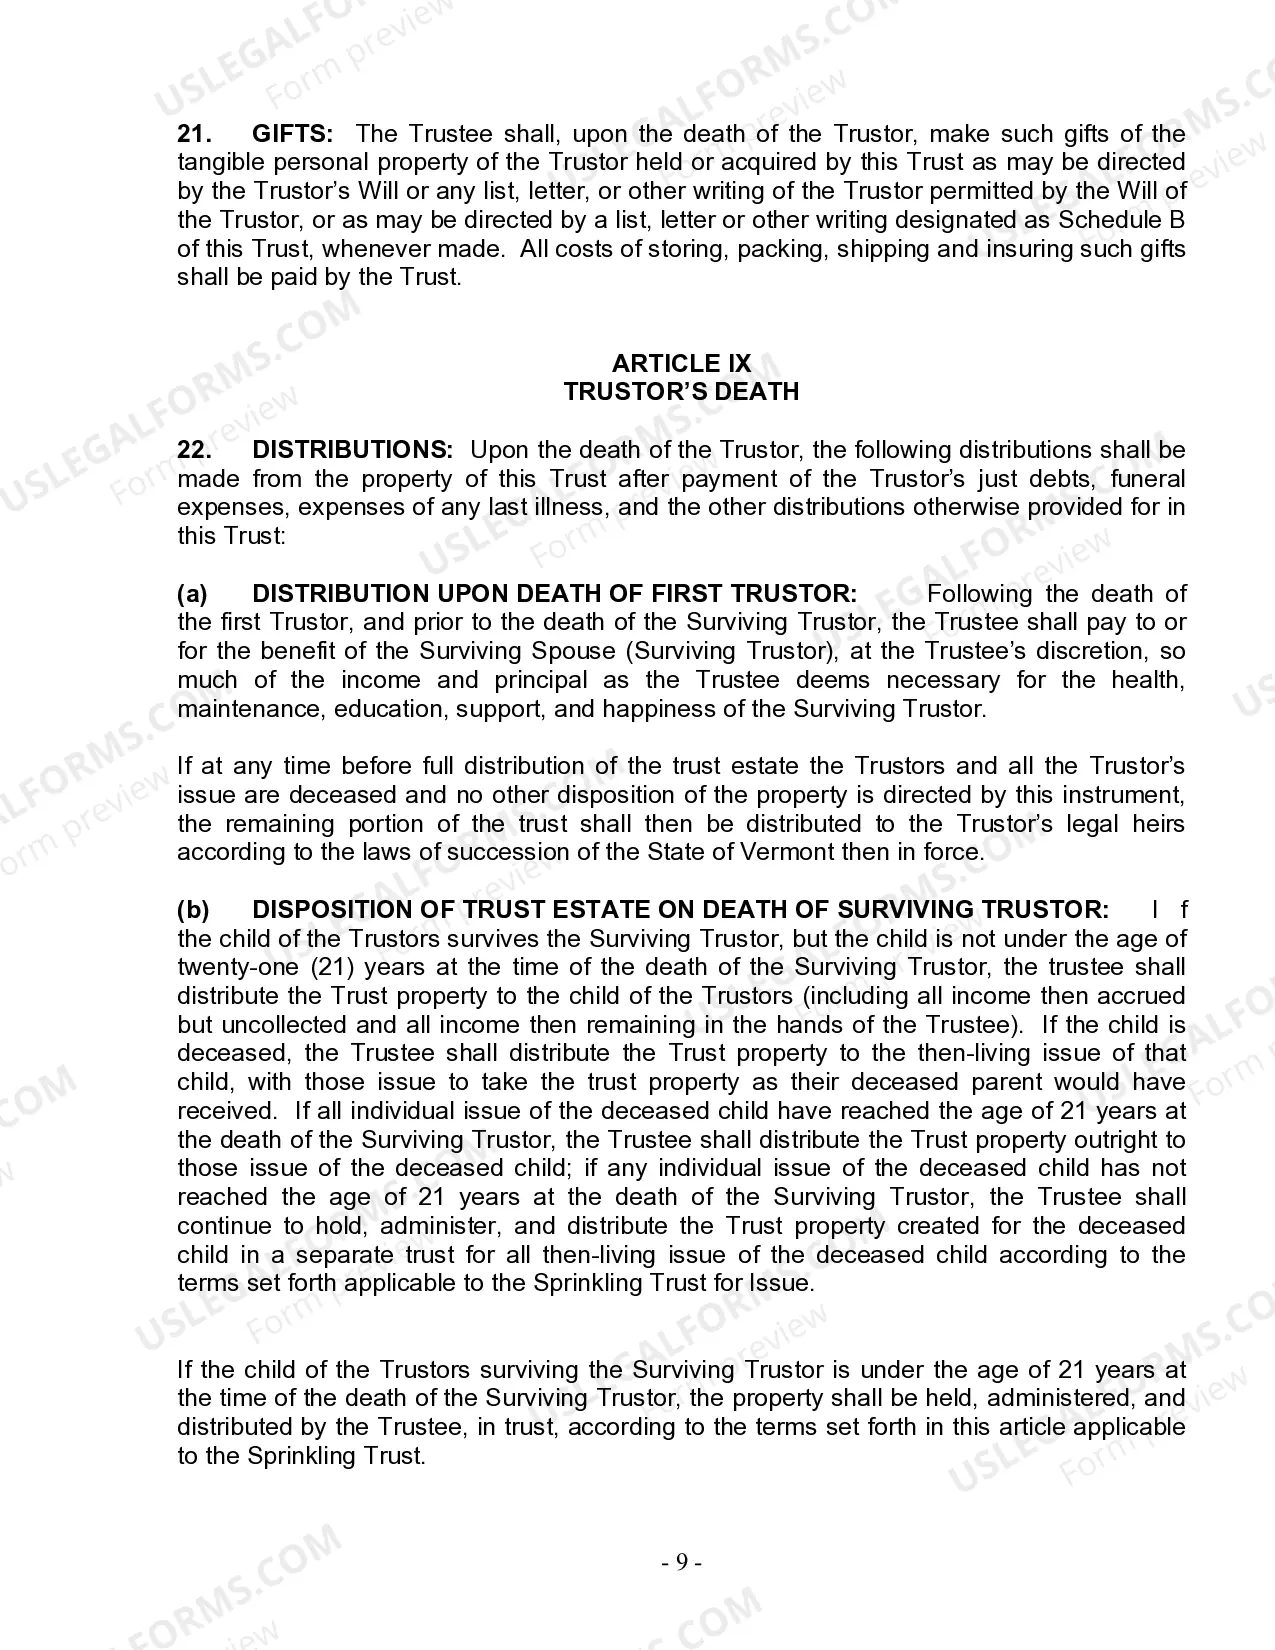
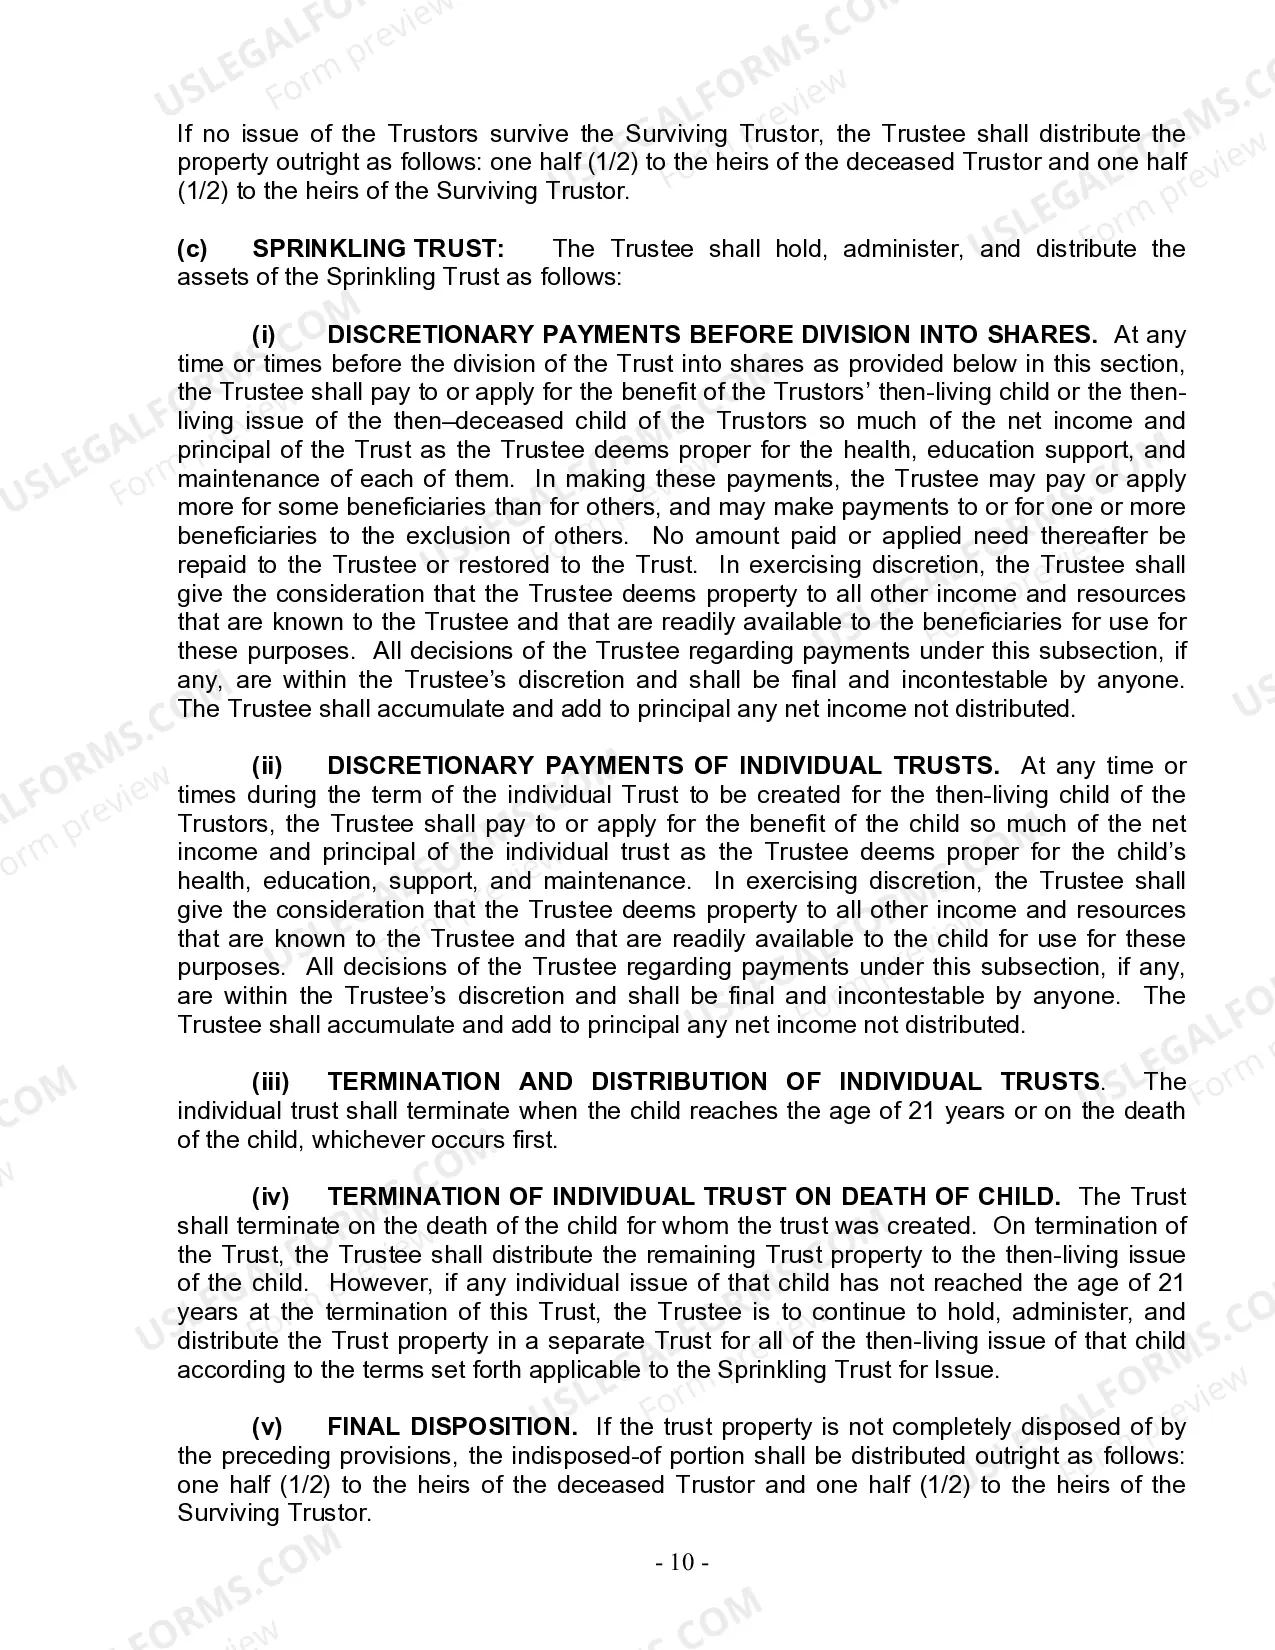
- Distributions Upon Death: Outlines how trust assets are distributed after the death of the trustors.
Situations where this form applies
This form should be used in situations where a husband and wife want to create a structured plan for managing their assets during their lifetime and ensuring a seamless transfer of those assets to their child after passing. It is particularly useful for couples looking to avoid the probate process, protect their child's inheritance, and maintain control over their assets until death. The form is relevant when they wish to address specific concerns related to asset management and distribution.
Who needs this form
- Married couples with one child seeking estate planning solutions.
- Couples who want to ensure that their assets are not subject to probate after their deaths.
- Individuals looking to retain control over their assets while benefiting their child.
- Families wanting to provide a clear structure for asset distribution and management.
Instructions for completing this form
- Identify the parties involved: Enter the names of the husband and wife as Trustors.
- Specify the trustâs name: Choose a name for the trust in the designated section.
- List the assets: Provide a detailed list of all properties and assets included in the trust.
- Appoint a trustee: Designate who will manage the trust assets during the life of the Trustors.
- Sign and notarize: Complete the form with signatures of the Trustors and have it notarized as required.
Is notarization required?
Yes, this form must be notarized to be legally valid. US Legal Forms offers integrated online notarization services that are available 24/7 via secure video calls, ensuring that your trust can be executed promptly and efficiently, without the need for travel.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Avoid these common issues
- Failing to list all assets or property accurately in the trust.
- Not specifying the trustee or successor trustee clearly.
- Omitting signatures or not notarizing the document as required.
- Not reviewing the trust terms with an attorney to ensure compliance with state law.
Benefits of using this form online
- Convenience of completing the form from anywhere, anytime.
- Editable options to customize the trust to your specific needs.
- Secure storage and easy access to your completed documents.
- Drafted by licensed attorneys to ensure legal accuracy and reliability.
Looking for another form?
Form popularity
FAQ
Paperwork. Setting up a living trust isn't difficult or expensive, but it requires some paperwork. Record Keeping. After a revocable living trust is created, little day-to-day record keeping is required. Transfer Taxes. Difficulty Refinancing Trust Property. No Cutoff of Creditors' Claims.
Qualified retirement accounts 401ks, IRAs, 403(b)s, qualified annuities. Health saving accounts (HSAs) Medical saving accounts (MSAs) Uniform Transfers to Minors (UTMAs) Uniform Gifts to Minors (UGMAs) Life insurance. Motor vehicles.
Under California law, a marriage automatically invalidates any pre-existing will or trust as to the new spouse's inheritance rights, unless the documents provide for a new spouse, or clearly indicate a new spouse will receive nothing.
Many people choose to set up different types of trusts to manage their funds for their families, including after they pass away. Generally, a family trust is any trust set up for the benefit of someone's relatives and a living trust is one set up while its creator is still alive.
When Should You Put a Bank Account into a Trust?More specifically, you can hold up to $166,250 of real or personal property outside a trust and avoid full probate in California. However, if you have more than $166,250 in a bank account, you should consider transferring it into your trust.
The trust in no way protects your assets, so that reasoning is simply false. You should put your vehicles into your trust in order to avoid probate. Only those assets held by the trust will avoid probate.
If the ultimate beneficiaries of the Living Trust are family members of the person who created the trust, the trust will often be referred to as a Family Trust. If those beneficiaries include friends, charities, or other non-family members, then the trust is typically called a Living Trust.
Houses and other real estate (even if they're mortgaged) stock, bond, and other security accounts held by brokerages (but think about naming a TOD beneficiary instead) small business interests (stock in a closely held corporation, partnership interests, or limited liability company shares)
With a shared trust, property left by one grantor to the survivor stays in the living trust when the first grantor dies; no transfer is necessary.You can transfer all of it to the trust, and each spouse can name beneficiaries (including each other) to receive his or her separate property.