Oklahoma Chattel Mortgage
Overview of this form
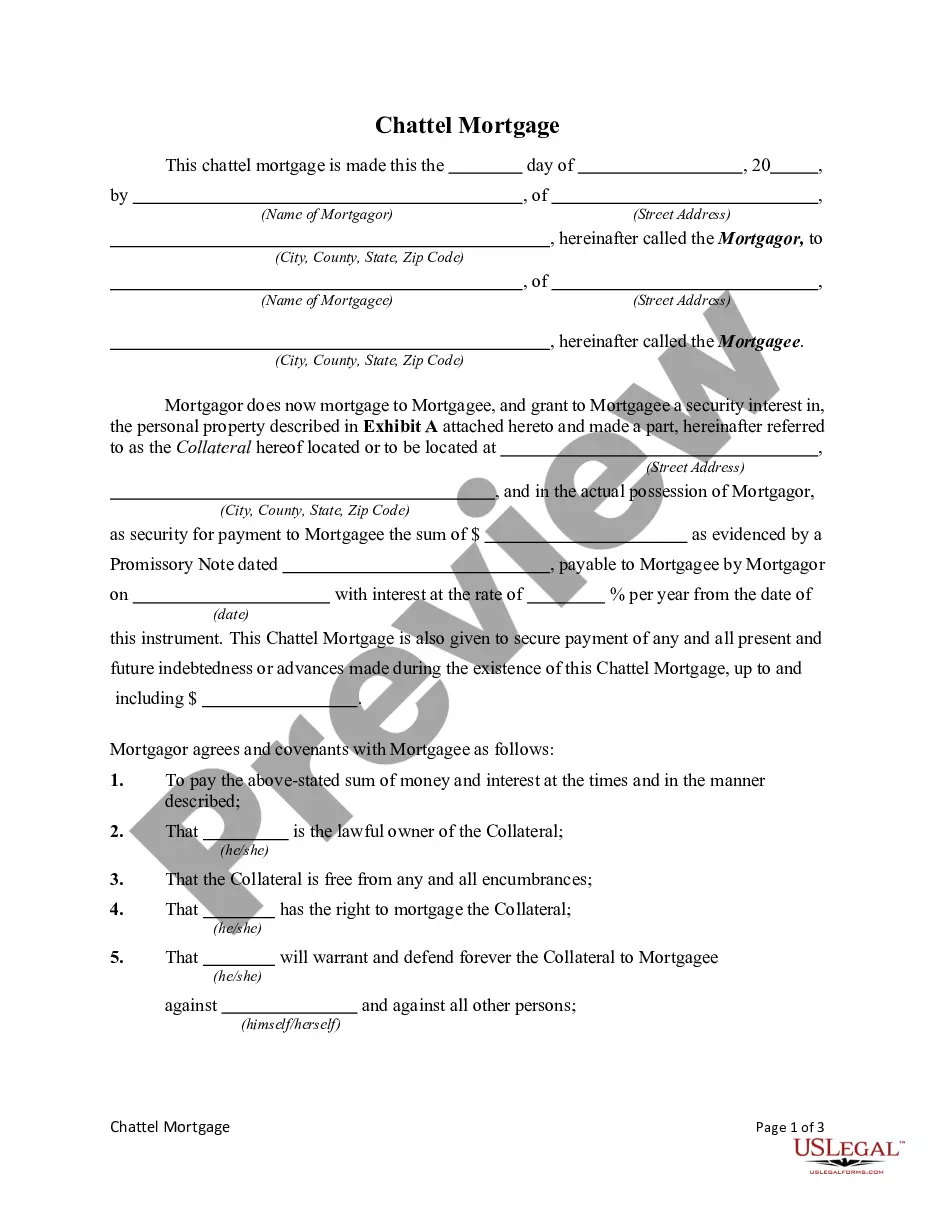
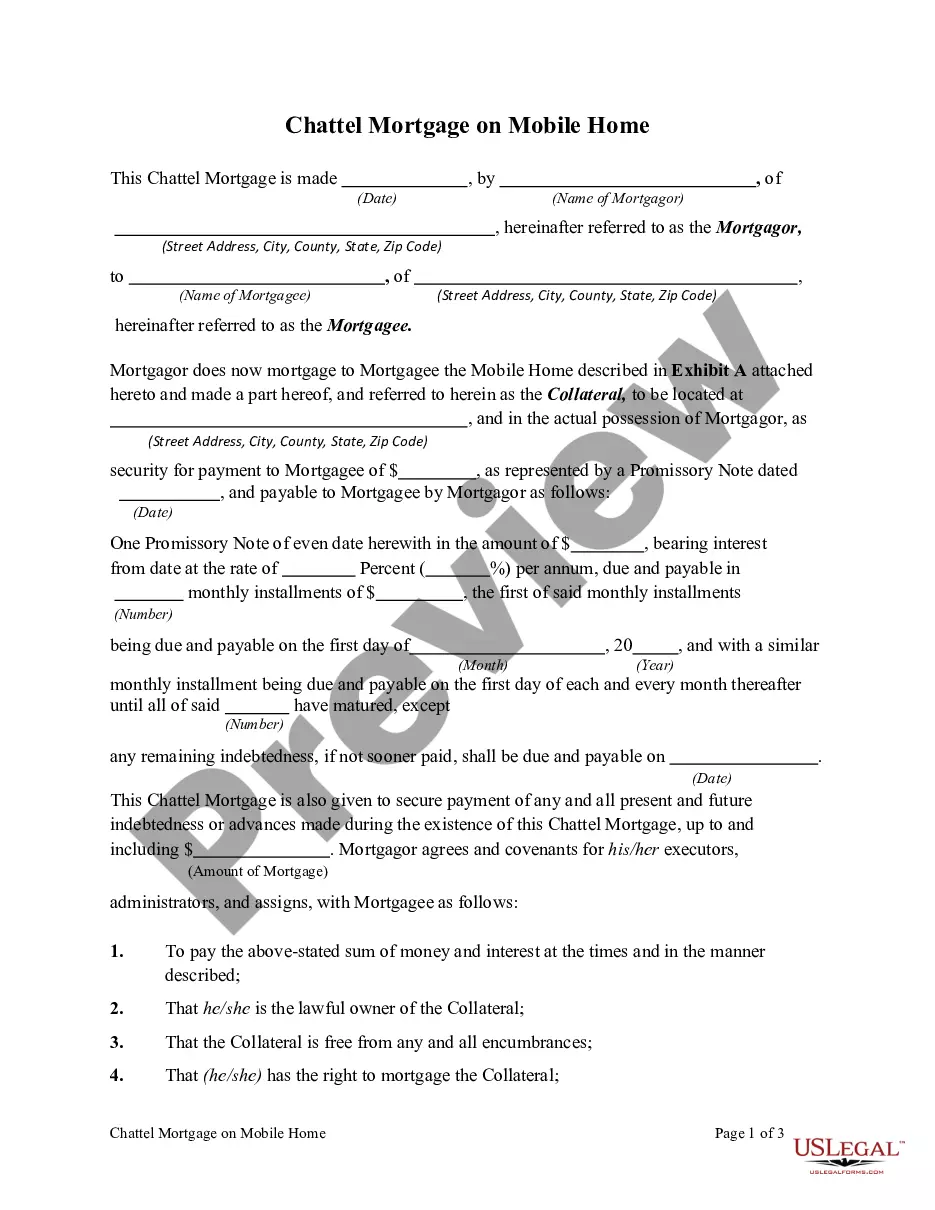
A chattel mortgage is a type of loan secured by personal property, such as equipment or vehicles. Unlike traditional mortgages secured by real estate, a chattel mortgage involves movable property. This legal document offers protection to the lender by allowing them to claim the property if the borrower defaults on repayment.
What’s included in this form
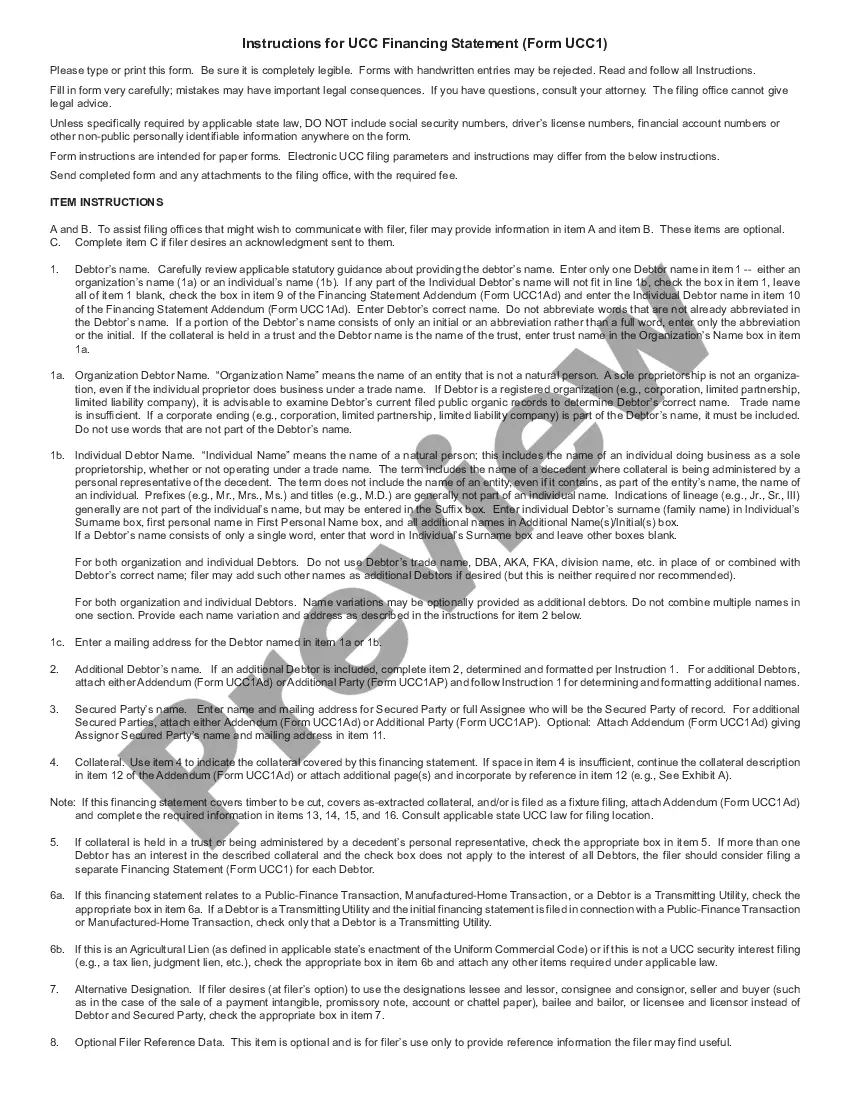
- Name and address of the Mortgagor (borrower) and Mortgagee (lender)
- Description of the personal property being mortgaged, referred to as the collateral
- Details regarding the loan amount and payment terms, including interest rates
- Covenants and agreements set forth by the Mortgagor
- Conditions for default and remedies available to the Mortgagee
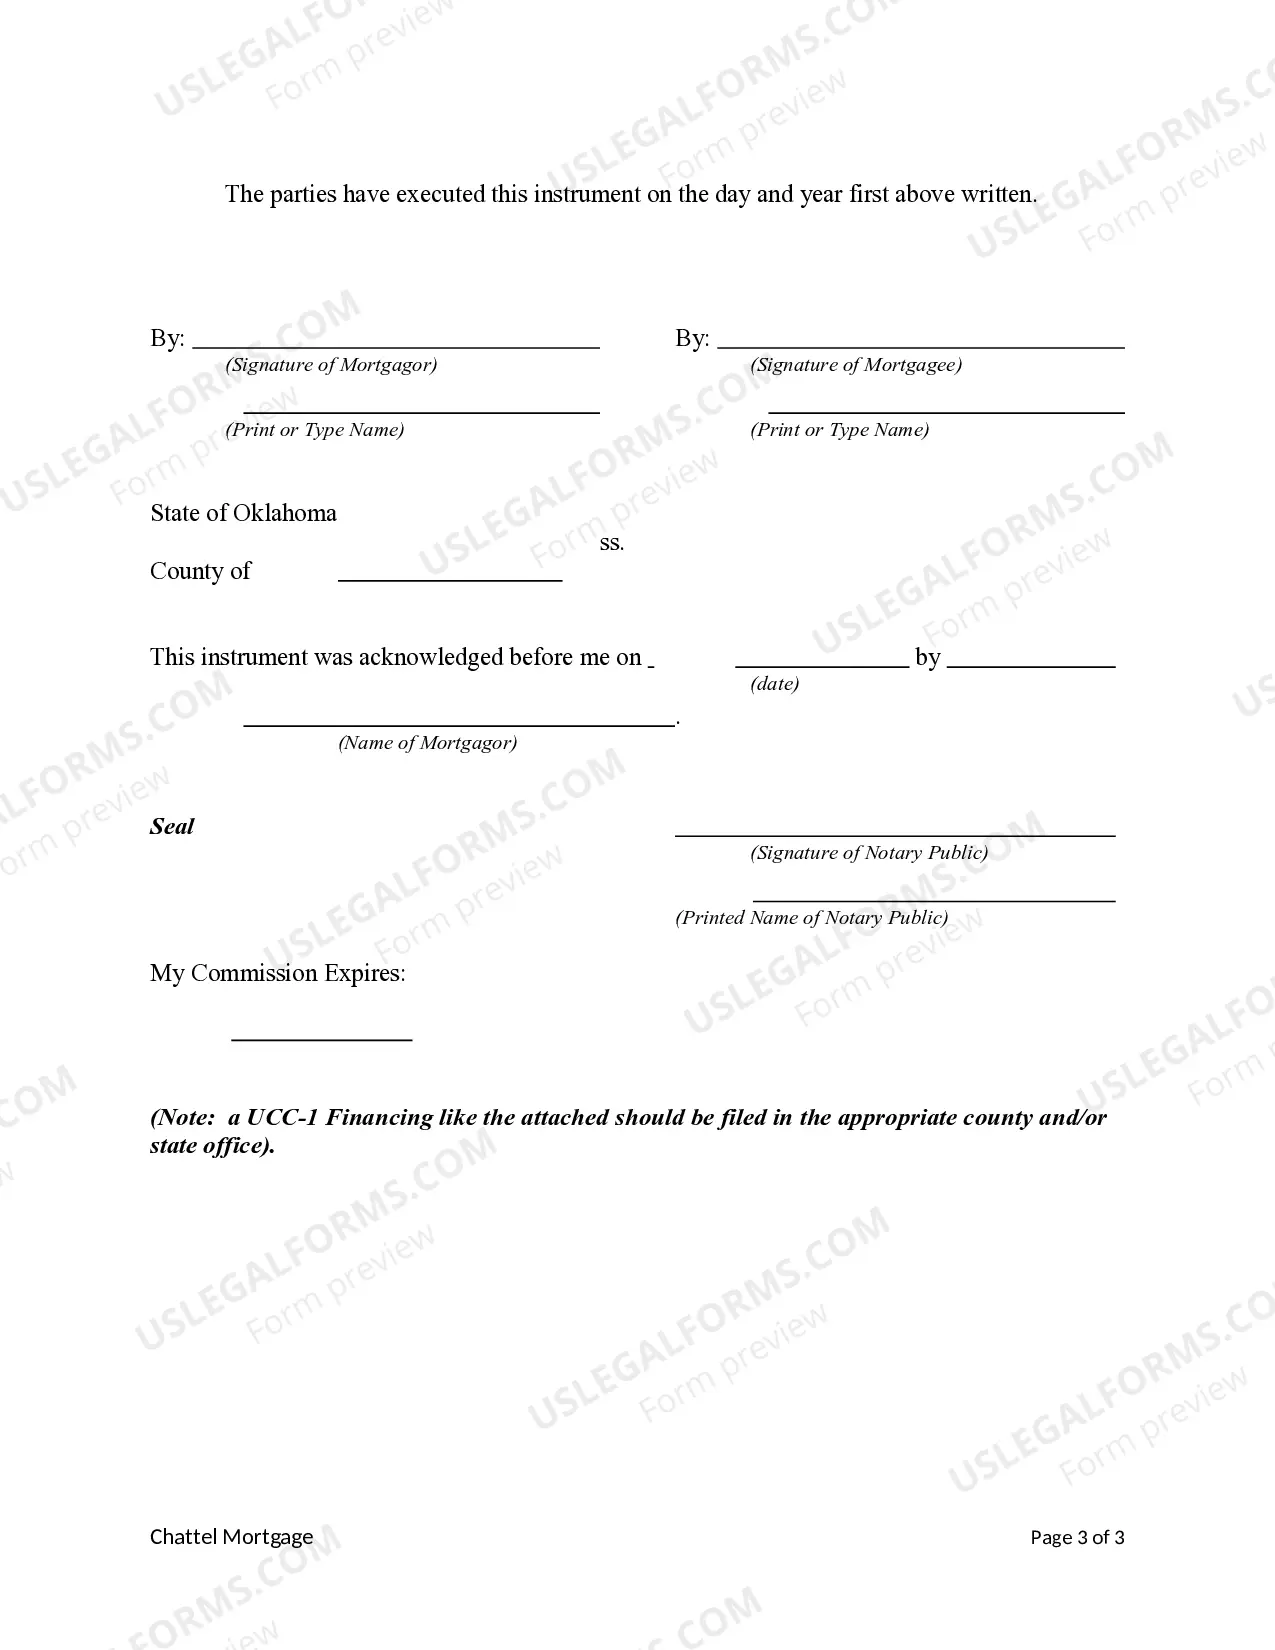
- Notarization and jurisdiction specifications

When this form is needed
This form is typically used when a borrower wishes to secure a loan with personal property rather than real estate. It may be appropriate in situations such as financing a vehicle, machinery, or other movable assets. If the borrower is unable to repay the loan, the lender has the right to repossess the specified collateral.
Who should use this form
- Individuals or businesses seeking financing secured by personal property
- Lenders who wish to ensure their loans are backed by specific assets
- Parties involved in buying or leasing movable assets that require a structured loan agreement
Instructions for completing this form
- Identify the Mortgagor and Mortgagee by providing full names and addresses.
- Describe the collateral in detail as specified in Exhibit A.
- Enter the loan amount and the interest rate agreed upon.
- Specify the payment due dates and any additional conditions for the loan.
- Both parties should sign and date the document in the presence of a notary public.
Is notarization required?
Yes, this form must be notarized to be legally valid. US Legal Forms offers integrated online notarization, allowing you to complete this step securely and conveniently without needing to travel.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Common mistakes to avoid
- Failing to accurately describe the collateral can lead to disputes.
- Not including all necessary signatures, including the lender's.
- Omitting details about the loan amount or interest rate.
- Neglecting to have the document notarized when required.
Advantages of online completion
- Convenient access to professionally drafted legal documents.
- Editable templates allow users to customize the document to their needs.
- Available for immediate download and use, saving time compared to traditional methods.
Looking for another form?
Form popularity
FAQ
There are only two types of manufactured home financing: a traditional mortgage and a chattel mortgage. Most people understand the traditional mortgage: find an existing home or build one, then apply for a 30-year fixed mortgage or another mortgage type and lock in a highly favorable interest rate.
Advantages of a Home Equity Loan They include:Access to a lot of Funds: You can get more funds to meet your financial issues by taking out a mobile home equity loan than a credit card or a personal loan. Tax Benefits: You can deduct the interest rate when itemizing your taxes if you use the loan to renovate your home.
If you need help buying a mobile home, you'll want to secure financing. Because mobile homes are not traditional real estate, obtaining financing for one can be a challenge. Most traditional lenders won't give you a mortgage to buy a mobile home, but there are other options to obtain loans for mobile homes.
There are only two types of manufactured home financing: a traditional mortgage and a chattel mortgage. Most people understand the traditional mortgage: find an existing home or build one, then apply for a 30-year fixed mortgage or another mortgage type and lock in a highly favorable interest rate.
Chattel Mortgage refers to a contract by virtue, which involves recording the personal property in the Chattel Mortgage Register as security for the performance of an obligation. The Chattel Mortgage can either be a formal contract or an accessory contract. It is required if the debtor has to retain the property.
You typically cannot get a home equity loan on a double-wide mobile home unless you own the land it resides on or you convert it to a home that is attached to the property beneath it.
A chattel mortgage is a loan for a movable piece of personal property, such as machinery, a vehicle or a manufactured home.
A conventional mortgage is a home loan that's not insured by the federal government. There are two types of conventional loans: conforming and non-conforming loans. A conforming loan simply means the loan amount falls within maximum limits set by the Federal Housing Finance Agency.
A chattel mortgage differs from a traditional mortgage in that the lender can take possession of the property that serves as security when a conventional loan is in default. The legal relationship is reversed with a chattel mortgage. The lender does not hold a lien against the movable propertythe chattel.