Acknowledgment by Debtor of Correctness of Account Stated
What this document covers
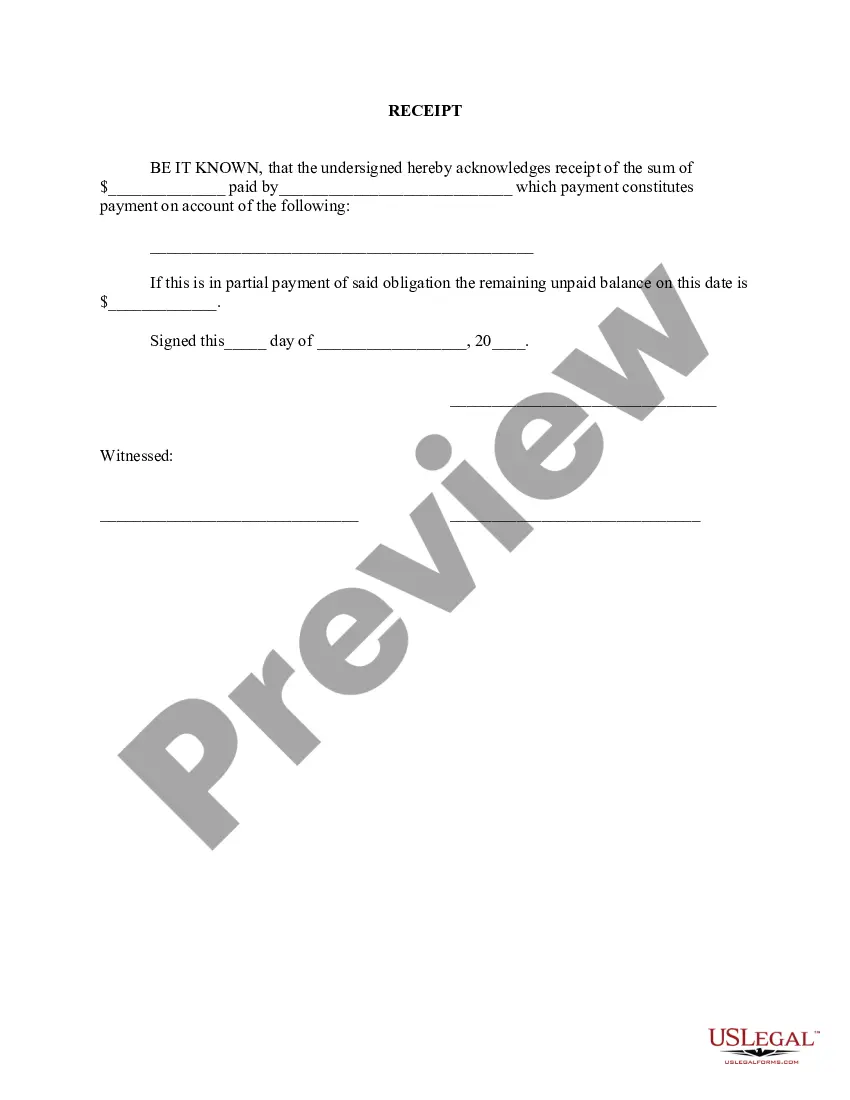
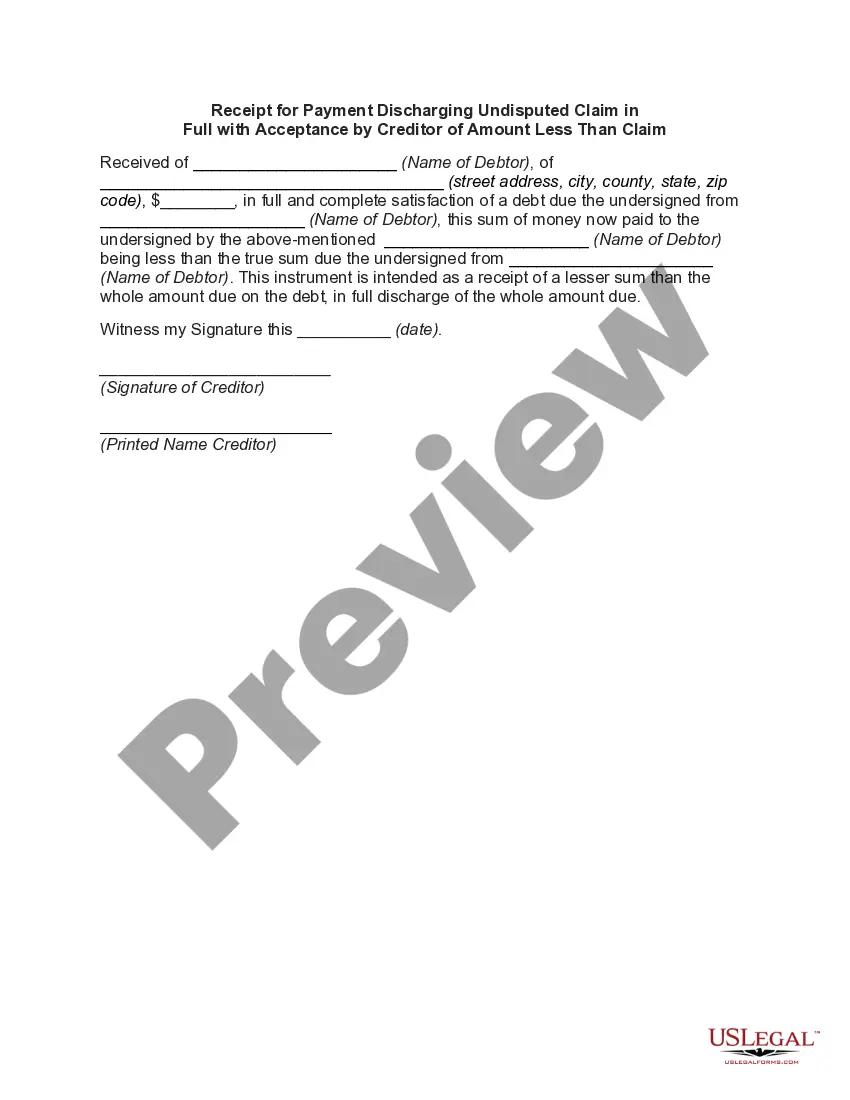
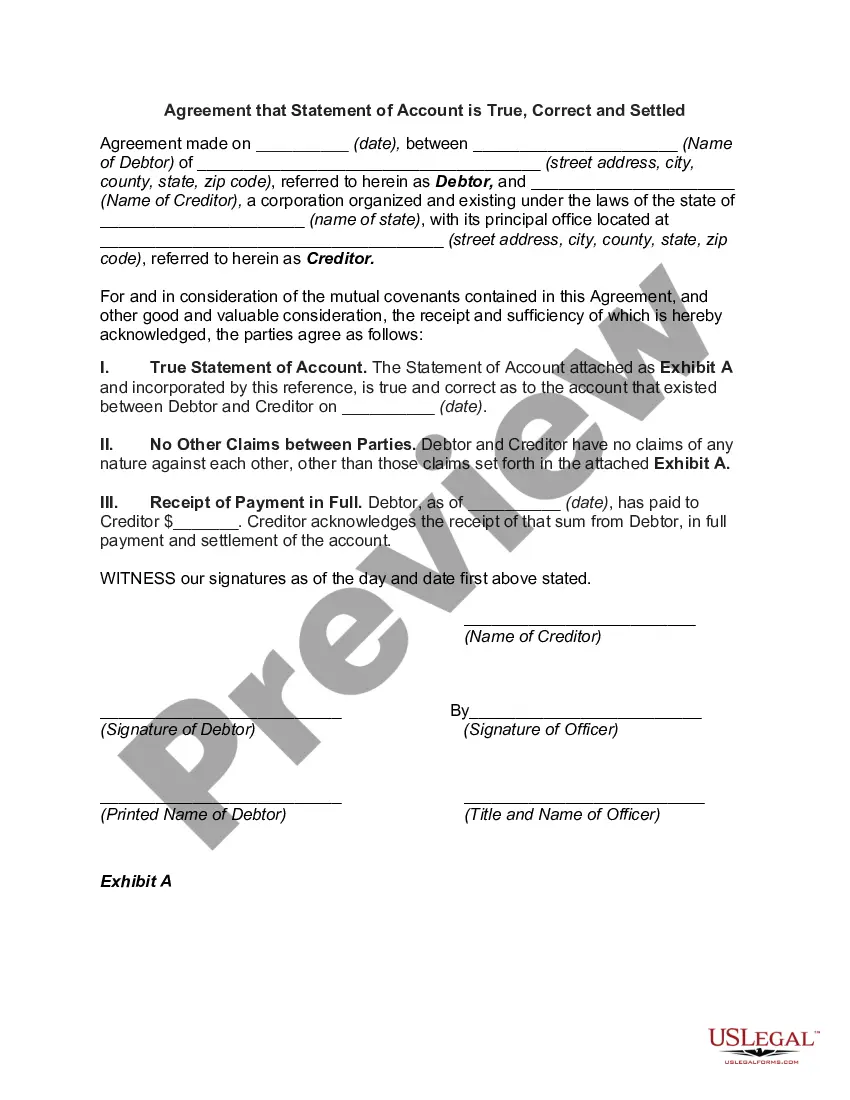
The Acknowledgment by Debtor of Correctness of Account Stated is a legal document used by a debtor to confirm the accuracy of a financial statement or balance owed to a creditor. This form reflects the mutual assent of both parties and verifies that the debtor agrees to the specified amount due. It differs from other debt acknowledgment forms by focusing specifically on a previously agreed-upon balance, ensuring clarity in financial obligations between the debtor and creditor.
What’s included in this form
- Identification of the debtor and creditor
- Statement of the agreed-upon balance
- Confirmation of mutual agreement and assent
- Signatures of the parties involved with dates
When to use this document
This form is useful in situations where a debtor needs to formally acknowledge a specific amount owed after financial transactions have occurred. It is particularly applicable when both parties have previously agreed on the total amount due but require documentation to confirm this agreement, such as before a refinancing or during a dispute resolution process.
Who should use this form
- Debtors wanting to confirm the correctness of a debt account
- Creditors seeking formal acknowledgment of the owed amount
- Individuals or businesses involved in financial agreements
Completing this form step by step
- Identify the debtor and creditor by entering their names and contact details.
- Clearly state the previously agreed-upon balance that the debtor acknowledges.
- Include a declaration that confirms mutual agreement between both parties.
- Sign and date the document to formalize the acknowledgment.
Does this form need to be notarized?
In most cases, this form does not require notarization. However, some jurisdictions or signing circumstances might. US Legal Forms offers online notarization powered by Notarize, accessible 24/7 for a quick, remote process.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Avoid these common issues
- Failing to include both parties' names and contact information.
- Not stating the exact amount acknowledged as owing.
- Omitting signatures or dates, which can invalidate the form.
Benefits of completing this form online
- Convenience of downloading and filling out the form anytime.
- Editability allows for easy changes before finalizing.
- Access to templates drafted by licensed attorneys for reliability.
What to keep in mind
- The form is crucial for confirming the debt amount between parties.
- Both debtor and creditor must mutually agree on the terms stated.
- Proper completion ensures legal enforceability in future disputes.
Looking for another form?
Form popularity
FAQ
An open book account is one where, at the time of filing the suit, the creditor still has an open or ongoing financial relationship with the debtor. For example, if your credit card has not yet been closed. The date of last entry for open book accounts is the date of your last payment.
An action for an accounting is an equitable cause of action. As discussed below, for statute of limitations purposes, the cause of action for an accounting must sometimes be distinguished from the remedy of an accounting.
Definition. A statement between a creditor and a debtor that settles the total amount of debt owed to the creditor.
In California, a common count is proper whenever the plaintiff claims a sum of money due, either as an indebtedness in a sum certain, or for the reasonable value of services or goods furnished.
A person is enriched if he receives a benefit at another's expense.") (citations omitted). California does not recognize unjust enrichment as a claim for relief.
N. an account of a customer kept in a business ledger of debits and credits (charges and payments), which shows the amount due at any given time. This can provide a clear basis for suing for a debt. ( See: account stated)
The most common way to defeat an action for account stated is to show that the debt claimed is new, i.e., that there was no prior course of dealing between the parties or, at best, only a very short period with very few transactions.
An account-stated claim requires a plaintiff to show three things: (1) a prior relationship as debtor and creditor, (2) a showing of mutual assent between the parties as to the correct balance of the account, and. (3) a promise by the debtor to pay the balance of the account.