Nebraska Loan Modification Agreement
Overview of this form
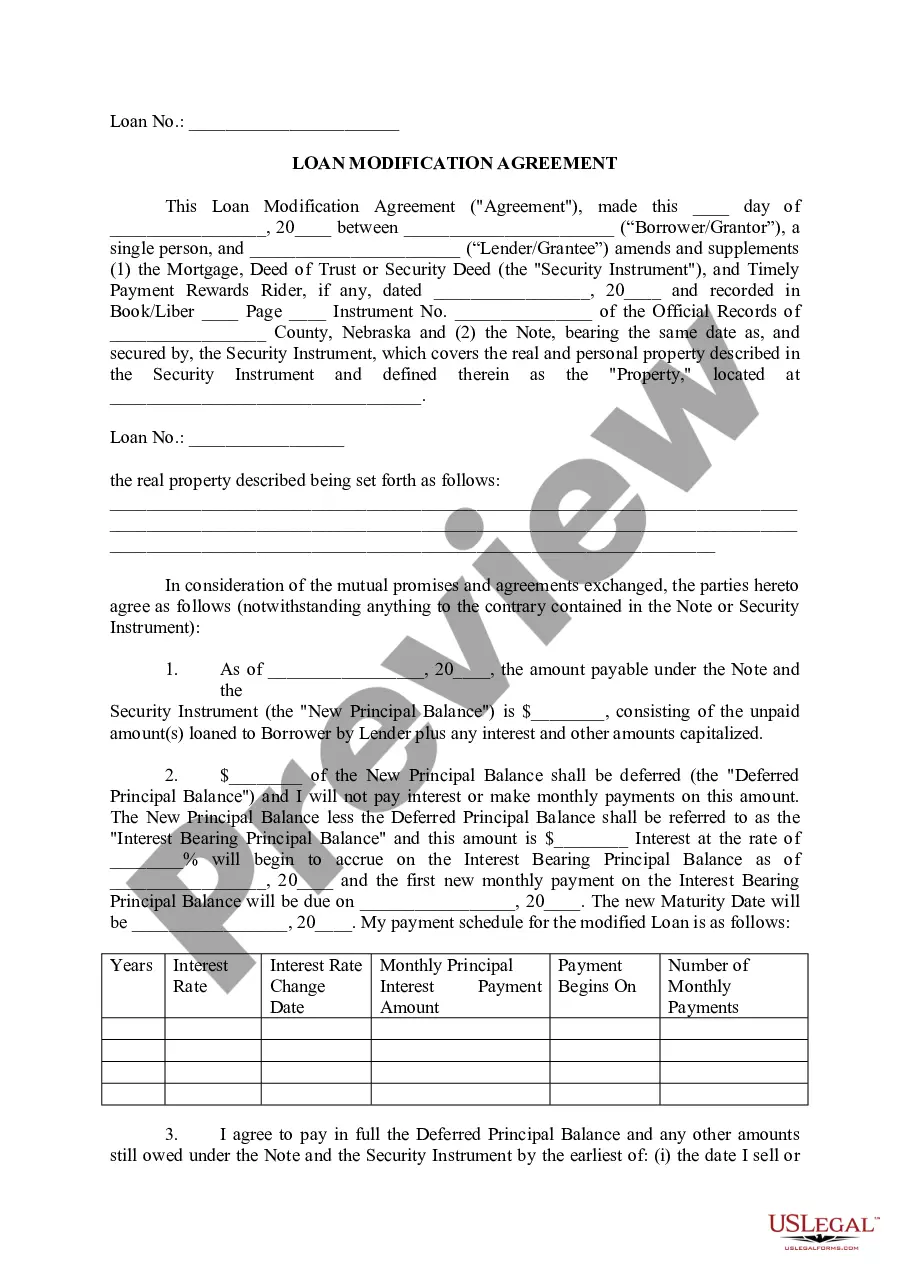
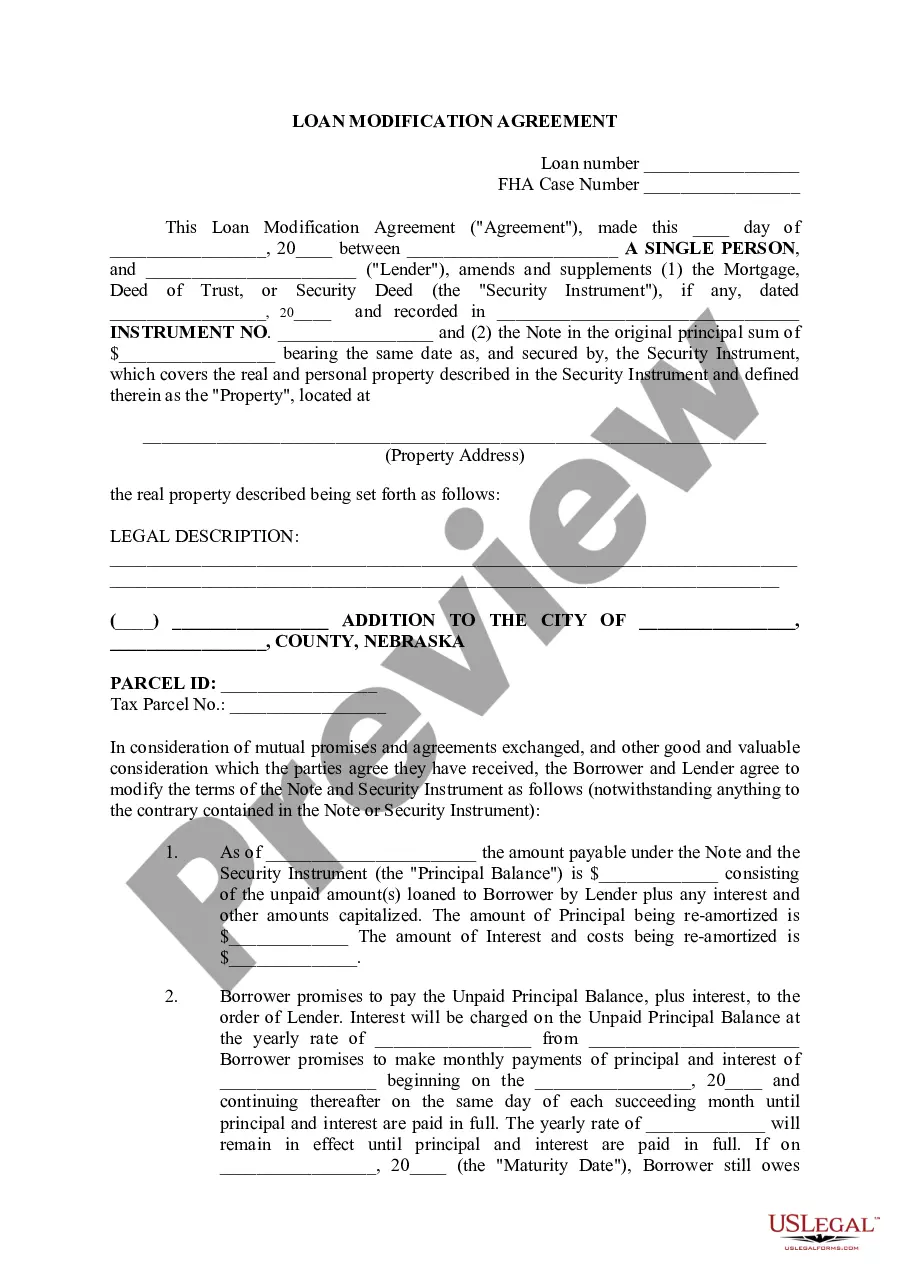
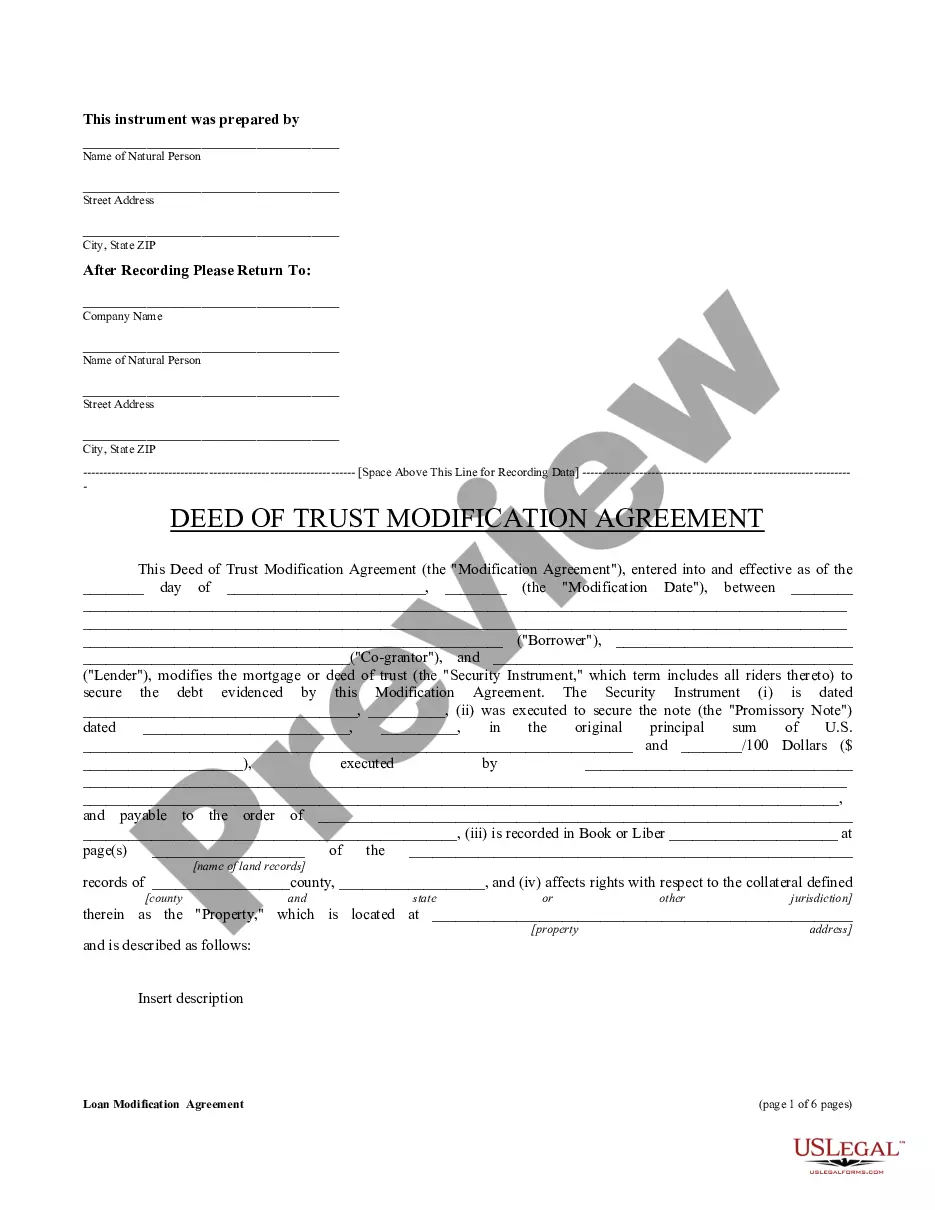
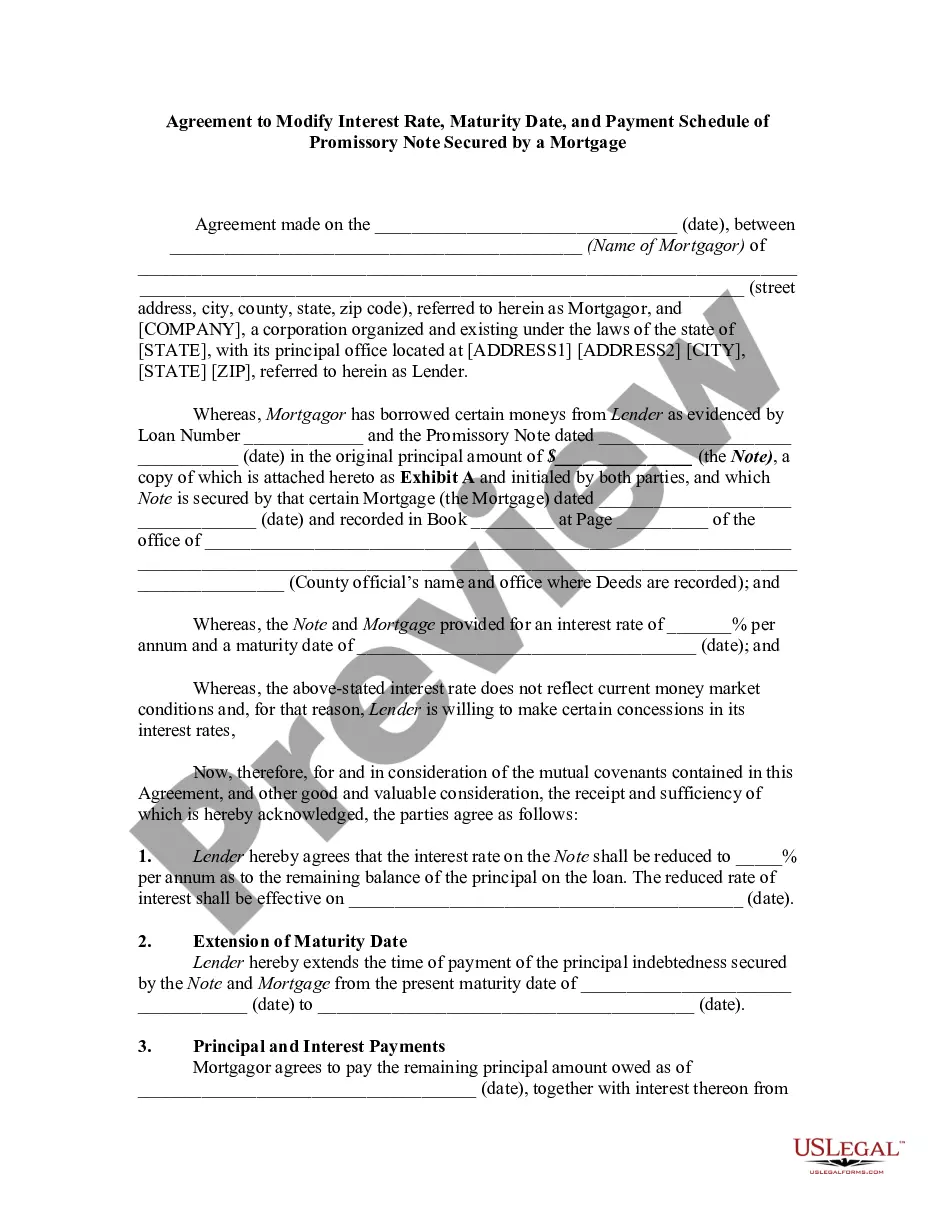
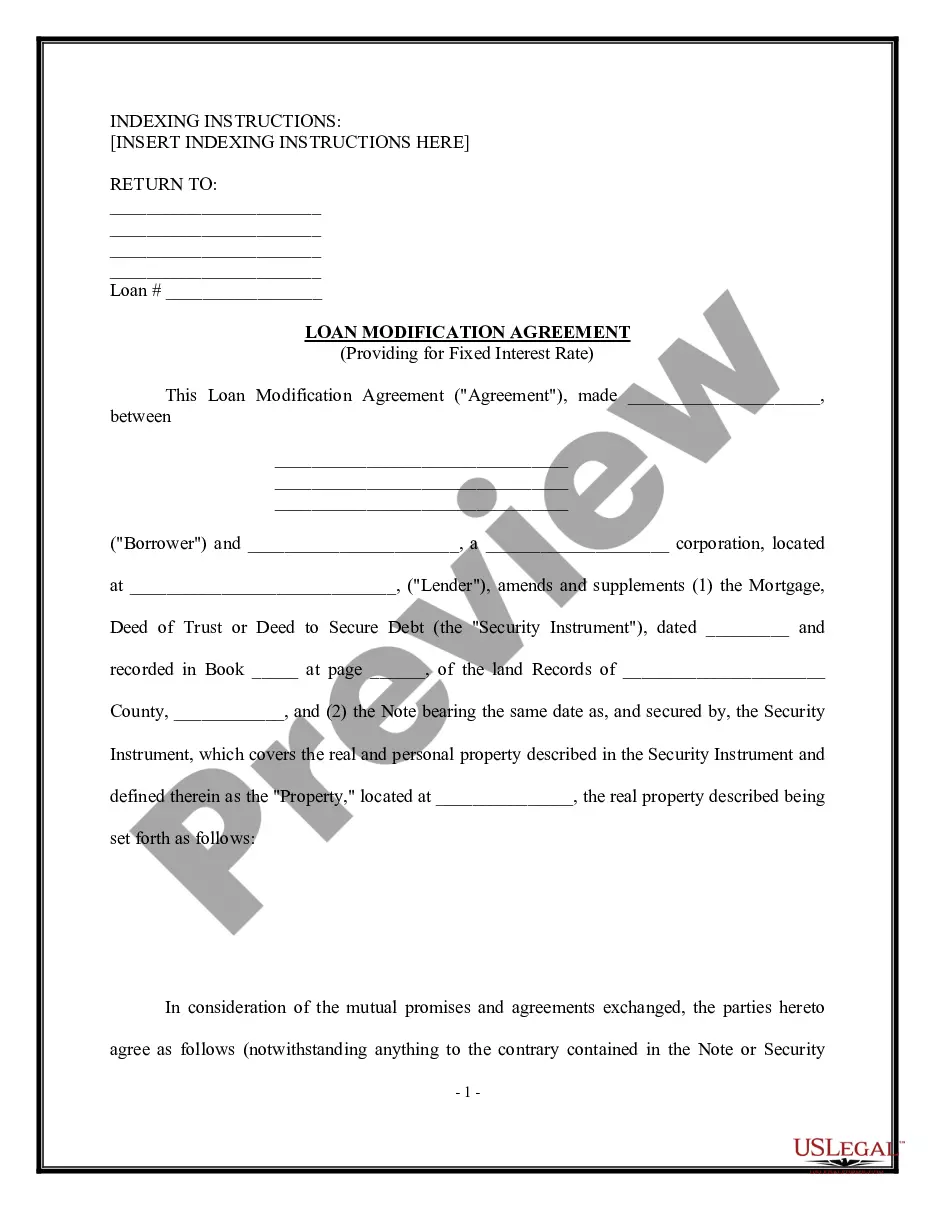
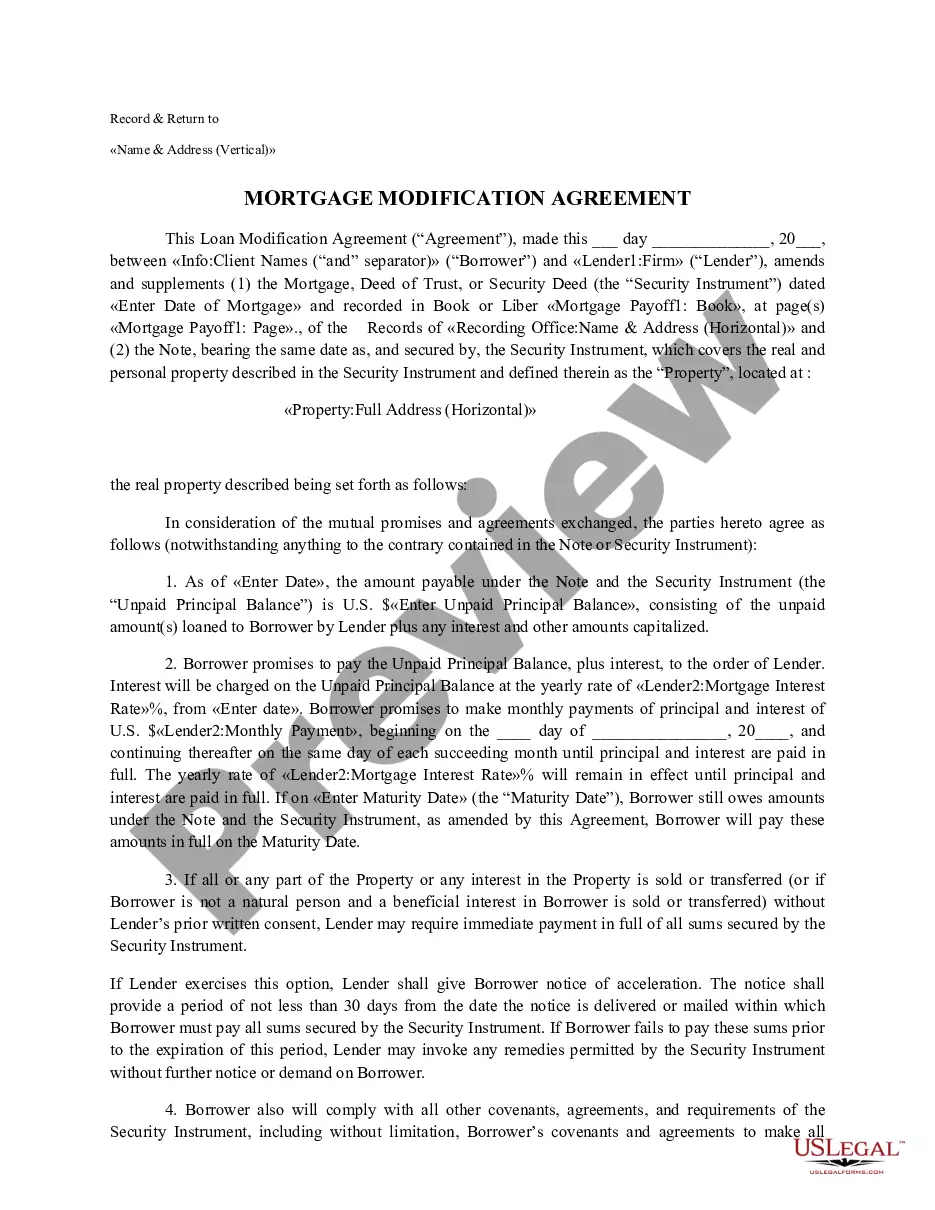
The Loan Modification Agreement is a legal document that allows borrowers and lenders to make changes to existing mortgage terms. It allows parties to amend their original agreement concerning a mortgage, Deed of Trust, or related security instrument. This modification may involve changes to interest rates, payment schedules, or principal amounts, offering borrowers a chance to manage their mortgage more favorably in financial hardship situations.
Key components of this form
- Identification of the borrower and lender, including names and addresses.
- Details of the existing loan, including loan number and property description.
- Amended terms, including new principal balance and interest rates.
- Payment schedule for the modified loan, including due dates and amounts.
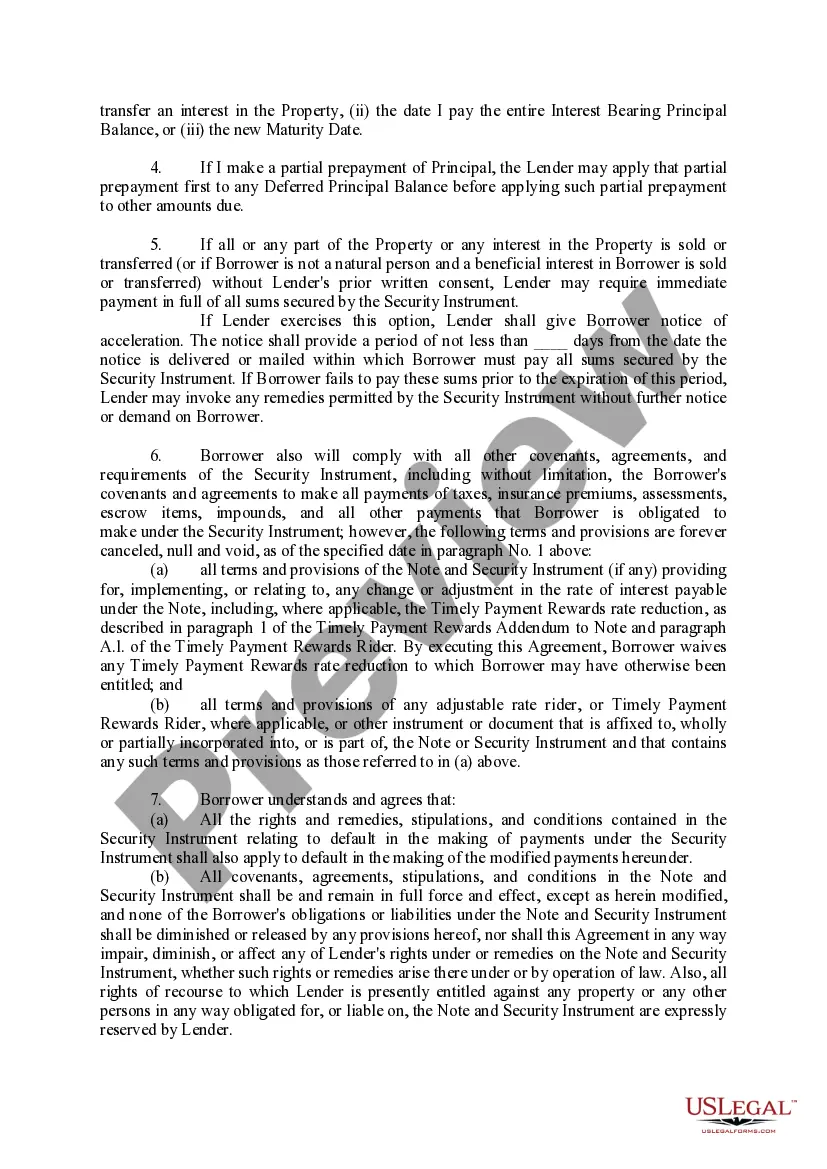
- Conditions for deferred principal balance and consequences of property transfer.
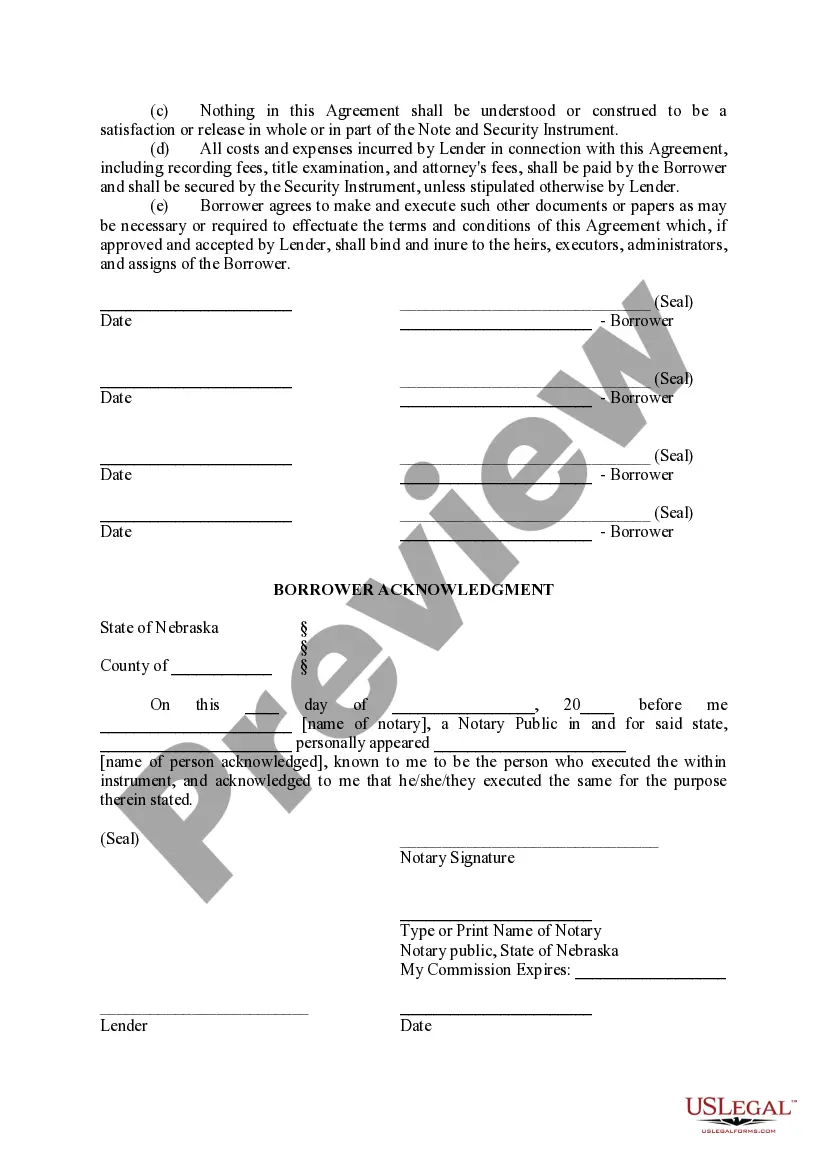
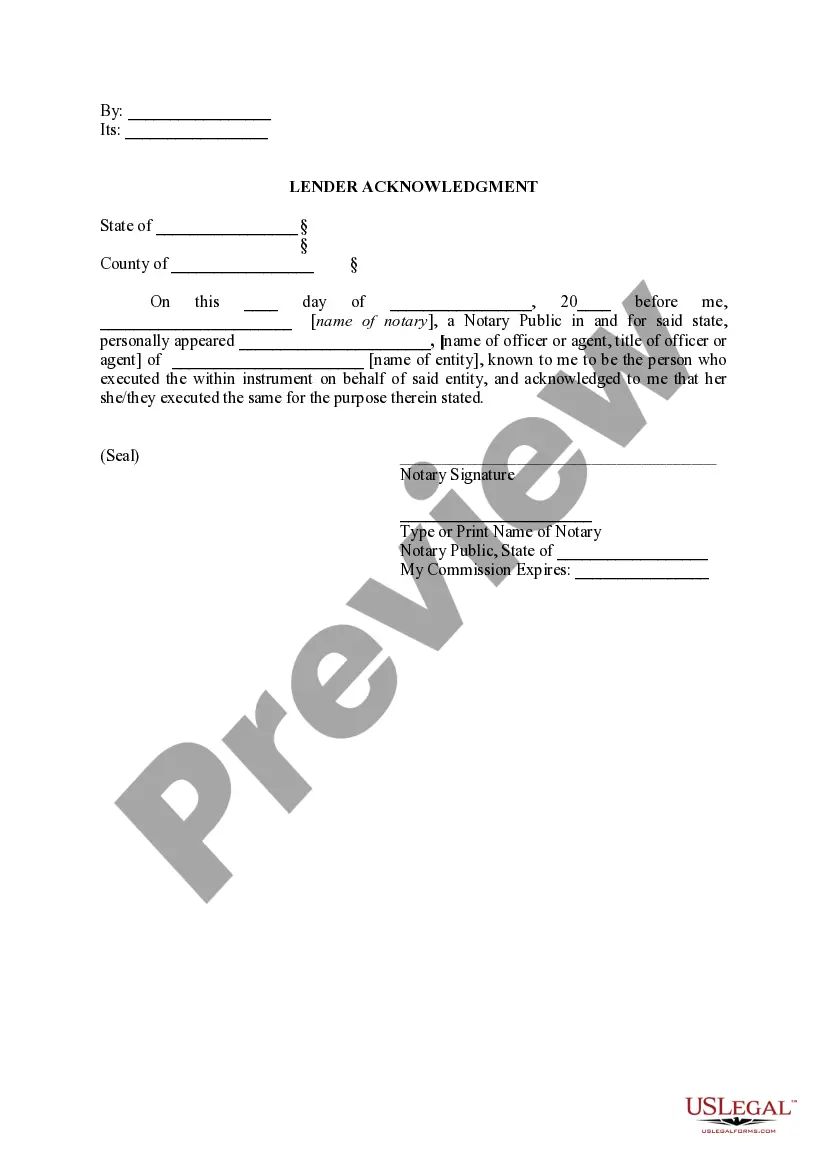
- Notary acknowledgment section for both borrower and lender.
When this form is needed
This form is used when a borrower needs to alter the terms of their existing mortgage due to financial changes. It may be suitable for individuals who are struggling to make monthly payments, those who want to reduce their interest rates, or homeowners looking to extend the repayment terms of their mortgage. Using this form can help borrowers avoid foreclosure and manage payments more effectively.
Intended users of this form
- Homeowners facing financial difficulties impacting their ability to make mortgage payments.
- Borrowers looking to modify the terms of their current mortgage or loan.
- Lenders who need to formalize changes in loan agreements with borrowers.
- Individuals seeking to clarify conditions regarding property transfer and loan obligations.
How to complete this form
- Identify the parties involved by filling in the names of the borrower and lender.
- Enter the details of the original loan, including the loan number and property description.
- Specify the new principal balance and set the terms of the modified loan.
- List the new payment schedule, detailing interest rates and payment due dates.
- Both parties must sign and have their signatures notarized.
Does this document require notarization?
Yes, this form must be notarized to be legally valid. Both the borrower and lender are required to sign the agreement in the presence of a notary public, ensuring authenticity and compliance with legal standards. US Legal Forms offers integrated online notarization services, allowing you to meet this requirement easily and securely through a video call, without the need for travel.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Avoid these common issues
- Failing to properly identify all parties involved in the agreement.
- Omitting crucial financial details, such as the new principal balance or interest rate.
- Not including required signatures and notarization, which can invalidate the agreement.
- Forgetting to specify when payments on the modified loan begin.
Why complete this form online
- Easy access to legally binding templates drafted by licensed attorneys.
- Convenience of completing the form online at your own pace.
- Edit and customize the form as necessary without needing to start from scratch.
- Secure storage of your completed forms for future reference.
Looking for another form?
Form popularity
FAQ
Be at least one regular mortgage payment behind or show that missing a payment is imminent. Provide evidence of significant financial hardship, for reasons such as:
Some of the most common types of hardship are: job loss, pay reduction, underemployment, declining business revenue, death of a coborrower, illness, injury, and divorce.
A lender may agree to a loan modification during a settlement procedure or in the case of a potential foreclosure.A loan modification agreement is a long-term solution. A loan modification may involve a reduced interest rate, a longer period to repay, a different type of loan, or any combination of these.
You should contact the lender's loss and mitigation department to discuss the reason of you loan modification rejection. Possible reasons for a modification rejection include insufficient income, high debt-to-income ratio, missing documents, or delinquent credit history.
Yes, probably. In California, a law called the Homeowner Bill of Rights (HBOR) generally gives borrowers the right to appeal a modification denial. Under HBOR, in most cases, if the servicer denies a borrower's application to modify a first lien loan, the borrower can appeal.