Connecticut Undertaking and Indemnity for Payoff of Existing Mortgage
What is this form?
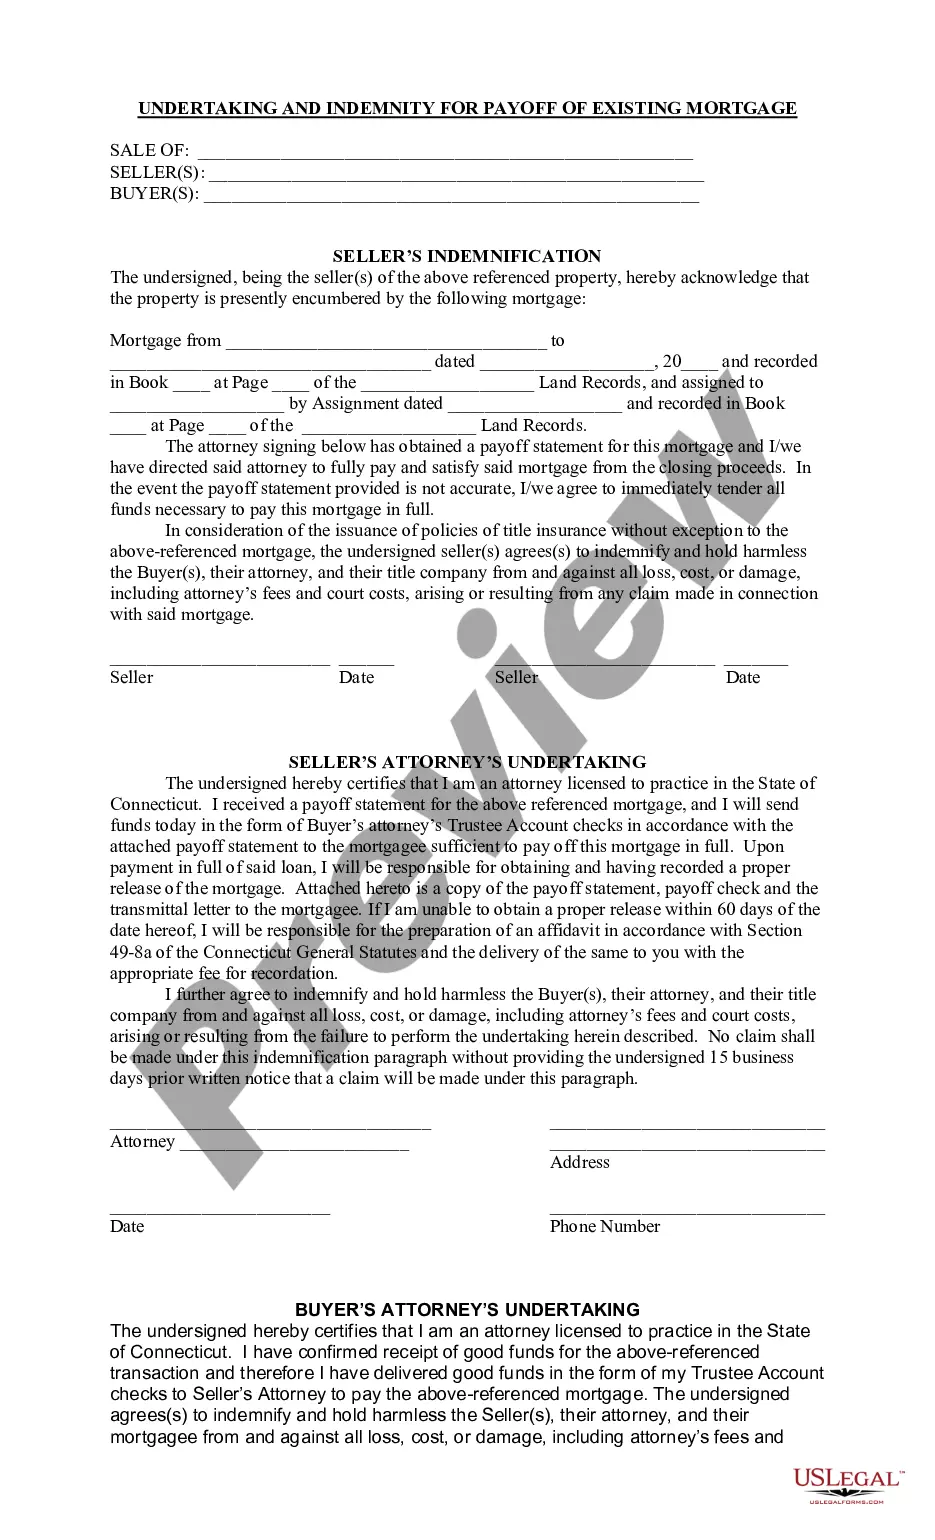
The Undertaking and Indemnity for Payoff of Existing Mortgage is a legal document used in real estate transactions. It enables the seller to acknowledge existing mortgage obligations on a property while ensuring that these debts are paid off at closing. This form is crucial because it protects both the buyer and the seller from any future claims arising from the unpaid mortgage, ensuring a clear title transfer. Unlike other forms related to mortgage discharges, this one specifically includes indemnification clauses to shield the parties involved.
Main sections of this form
- Identification of the property being sold and the seller(s) and buyer(s).
- Details of the existing mortgage, including dates and recording information.
- Sellerâs acknowledgment of the mortgage and instructions for payoff.
- Indemnification provisions protecting the buyer and their attorney.
- Declaration by both attorneys regarding their responsibilities in the payoff process.
Common use cases
This form is used during the sale of real estate when the property has an existing mortgage that requires payoff at the closing. It is essential to utilize this form when the seller's mortgage must be satisfied using the proceeds from the sale, ensuring both parties understand their financial responsibilities and legal protections.
Who can use this document
- Real estate sellers who have an outstanding mortgage on the property.
- Real estate buyers who require assurance that the mortgage will be paid off at closing.
- Attorneys representing either party in the transaction to ensure compliance with legal obligations.
How to complete this form
- Identify the parties involved: fill in the names of the seller(s) and buyer(s).
- Specify the property: include the address and details of the property being sold.
- Provide mortgage details: enter information about the existing mortgage including dates and recording details.
- Sign and date the form: ensure all parties, including attorneys, sign and date the document.
- Attach necessary documents: include the payoff statement and any related correspondence as indicated.
Notarization guidance
This form does not typically require notarization unless specified by local law. However, it is recommended to check state-specific regulations to ensure compliance.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Common mistakes
- Failing to include complete and accurate mortgage information.
- Not having all required parties sign the document.
- Omitting necessary attachments like the payoff statement.
- Not following state-specific requirements for execution or submission.
Why use this form online
- Convenience of downloading and completing the form at your own pace.
- Editability allows for easy corrections and adjustments before finalizing.
- Access to professionally drafted legal templates ensures compliance with legal standards.
Looking for another form?
Form popularity
FAQ
To obtain a release of liability on your mortgage, you must complete the payoff process and request a release from your lender. This release signifies that you are no longer responsible for the mortgage after the payoff. This is essential for your Connecticut Undertaking and Indemnity for Payoff of Existing Mortgage, ensuring you have no ongoing obligations.
A mortgage payoff request form is a document you fill out to formally request a payoff statement from your lender. This form typically requires your mortgage account information and may ask for your contact details. Using this form ensures that your request for a Connecticut Undertaking and Indemnity for Payoff of Existing Mortgage is processed efficiently.
To obtain a payoff letter from your lender, you can Contact them directly through their customer service line or portal. Provide your account details and specify that you need a mortgage payoff letter for your records. This letter plays a crucial role in your Connecticut Undertaking and Indemnity for Payoff of Existing Mortgage.
The time it takes to receive a mortgage payoff letter varies by lender but typically ranges from a few days to a couple of weeks. It's advisable to request this letter well in advance of your intended payoff date to avoid delays. This mortgage payoff letter is essential for your Connecticut Undertaking and Indemnity for Payoff of Existing Mortgage.
To indemnify means that the seller will reimburse the buyer for a loss or liability. To defend means that the seller will pay the buyer's legal fees for suits that arise from specific risks articulated in the contract.
The letter of indemnity will indemnify the buyer's title insurer from any losses incurred due to the title defect and will typically also contain an ?undertaking clause? which means that your title insurance company will resolve the title defect after your closing.
A more thorough explanation: Definition: An indemnity mortgage is a type of mortgage where the borrower is responsible for repaying the loan, but the lender has the right to take possession of the property if the borrower fails to repay the loan.
You should sign an indemnity agreement when there is a high degree of likelihood that you could incur third-party risk in a transaction. For example , when you run a construction company, you likely hire contractors that represent they complete work to specific standards ? standards that you are happy with.
Indemnification, also referred to as indemnity, is an undertaking by one party (the indemnifying party) to compensate the other party (the indemnified party) for certain costs and expenses, typically stemming from third-party claims.
An indemnification agreement, also called an indemnity agreement, hold harmless agreement, waiver of liability, or release of liability, is a contract that provides a business or a company with protection against damages, loss, or other burdens.