Arkansas Mortgagee's Notice of Default And Intention to Sell
Overview of this form
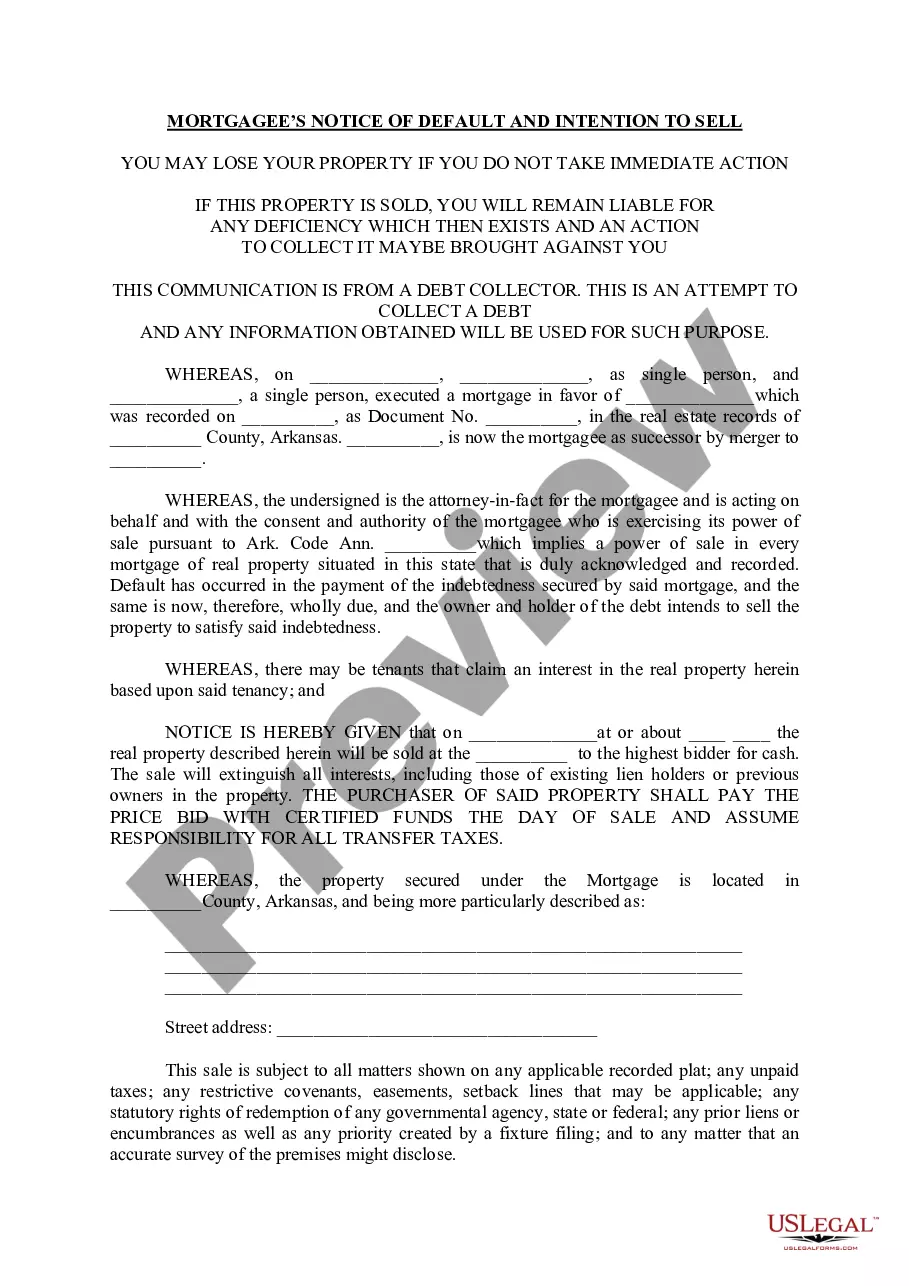
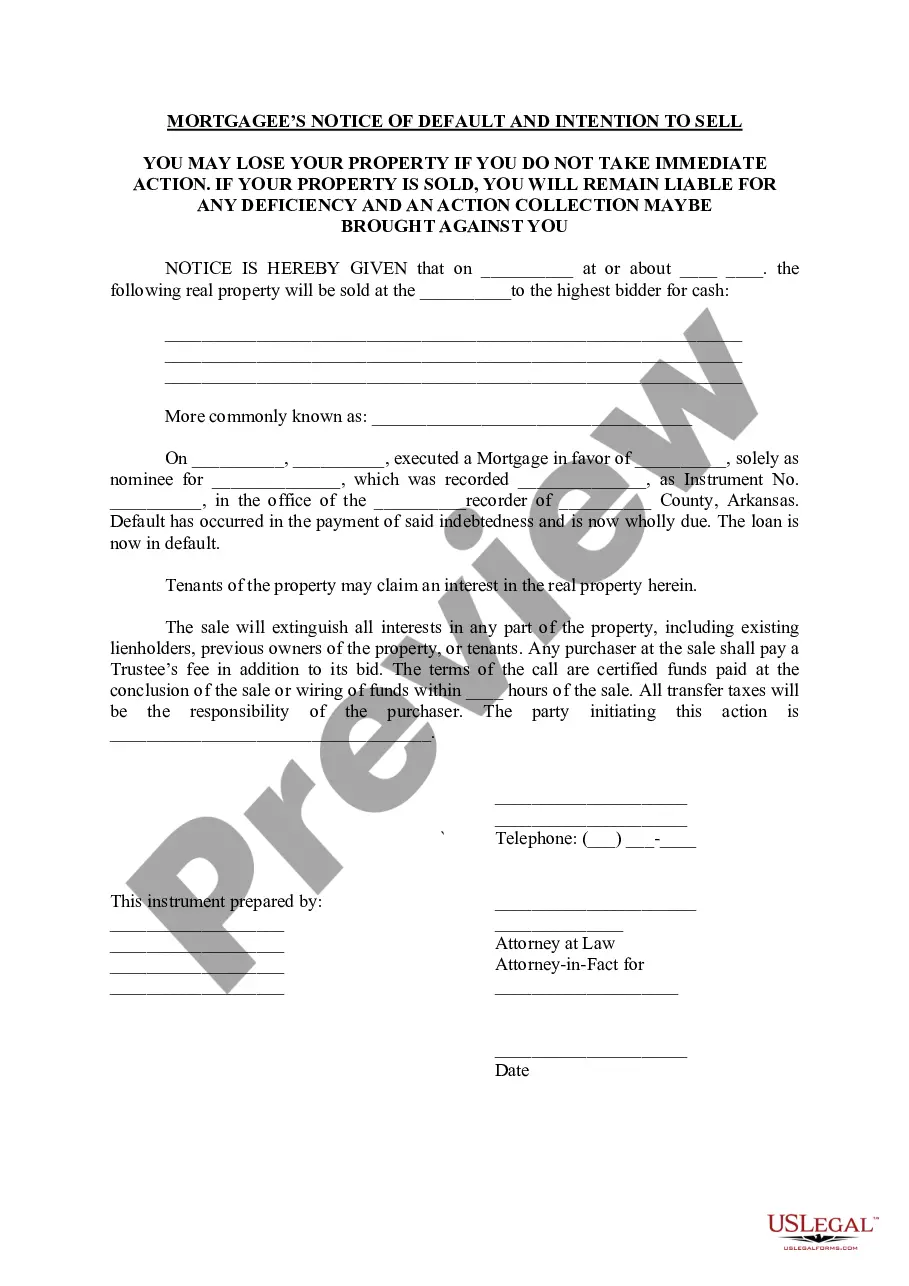
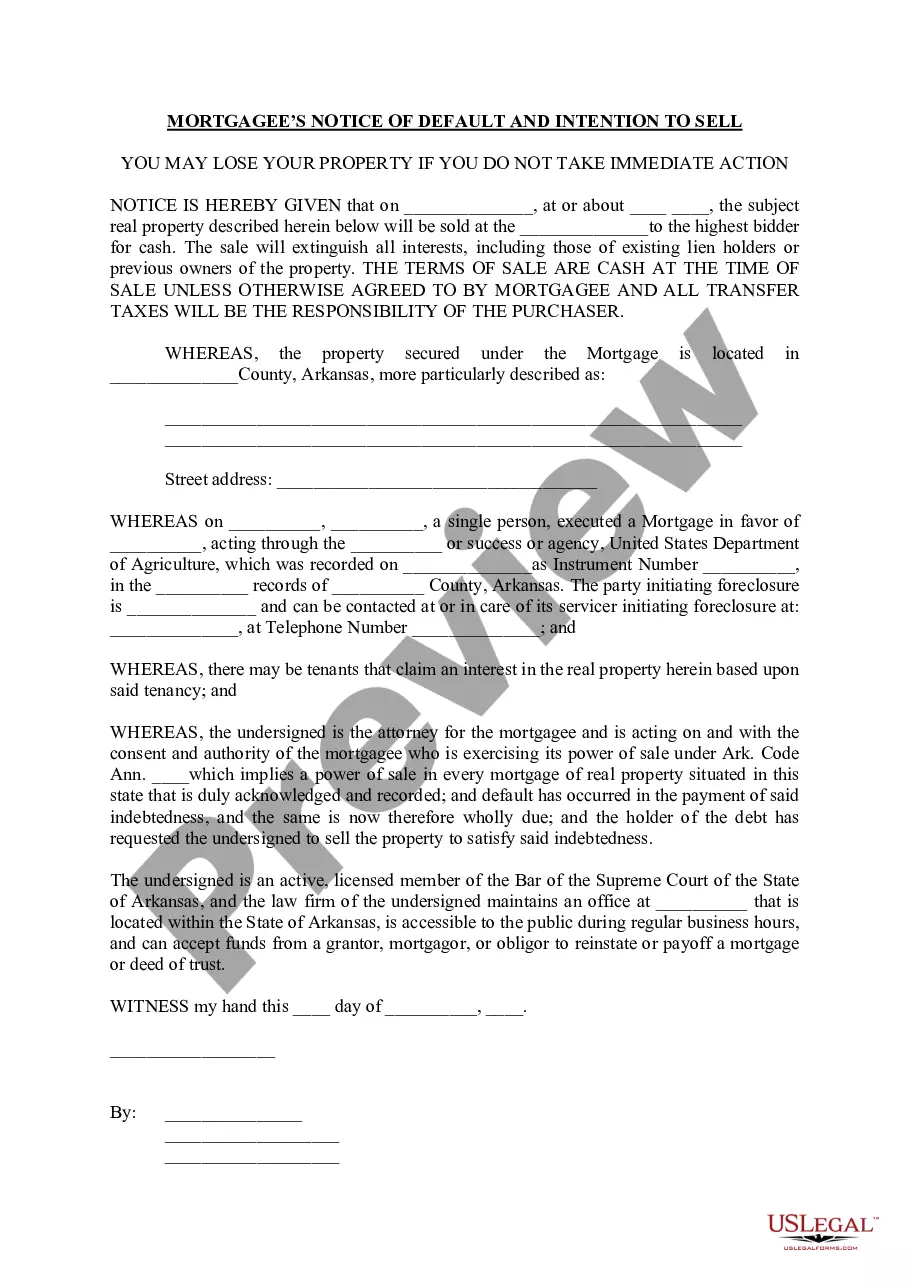
The Mortgagee's Notice of Default and Intention to Sell is a formal notification used by a mortgagee (the lender) to inform a borrower (the buyer) that they have defaulted on their mortgage payments. This notice serves as an important step in the foreclosure process, indicating the lender's intention to sell the property if the borrower fails to remedy the default. Unlike other notices, this form specifically outlines the details of the default and the impending sale of the property, making it essential for both parties to understand the consequences of non-compliance.
Key components of this form
- Identification of the mortgagor(s) and mortgagee
- Statement of the default on mortgage payments
- Details about the property including address and legal description
- Time and place of the proposed sale of the property
- Consequences of the sale, including liability for any deficiency
- Notarization and acknowledgment section
When this form is needed
This form should be used when a borrower has defaulted on their mortgage payments, and the lender intends to initiate the foreclosure process. It is crucial when the lender wants to officially notify the borrower of their default status and the impending sale of the property to recover the outstanding debt. This notice is typically sent after several missed payments and serves as a final warning before foreclosure proceedings begin.
Intended users of this form
This form is intended for:
- Mortgagees (lenders) seeking to notify borrowers of default
- Real estate attorneys representing lenders in foreclosure actions
- Property owners who have received a notice of default and wish to understand the implications
- Investors considering purchasing properties that are in default
How to prepare this document
- Identify the parties: Fill in the names of the mortgagee and the mortgagor(s).
- Provide mortgage details: Include the date of the mortgage, document number, and recording details.
- Specify the property: Enter the property's legal description and street address.
- Enter the date and time of the planned sale of the property.
- Sign and date the notice: Ensure an authorized representative signs the document.
- Complete the notary section: If required, have the notice notarized for legal validity.
Is notarization required?
Yes, this form must be notarized to be legally valid. US Legal Forms provides integrated online notarization, allowing you to securely notarize your forms through a video call at your convenience, ensuring you can comply with legal requirements without the need for travel.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Common mistakes
- Failing to include the correct legal description of the property.
- Not providing accurate names and addresses of the mortgagee and mortgagor(s).
- Missing the deadline for issuing the notice after default occurs.
- Neglecting to have the document notarized if required.
Benefits of completing this form online
- Instant access to professionally drafted documents that comply with current laws.
- Convenient online editing options to tailor the form to specific situations.
- Easy downloading and printing for immediate use.
- Guidelines and support available to assist with completion.
Looking for another form?
Form popularity
FAQ
In Arkansas, a lender typically files an Arkansas Mortgagee's Notice of Default And Intention to Sell after three missed payments. However, this can vary depending on the lender's policies. It's crucial to look into your mortgage agreement for specific terms. Ignoring the situation may lead to serious consequences, including foreclosure.
Yes, Arkansas allows a redemption period after foreclosure. Under the Arkansas Mortgagee's Notice of Default And Intention to Sell, homeowners typically have up to one year to redeem the property by paying off the debt. This period offers a crucial opportunity for homeowners to reclaim their property even after a foreclosure sale has been completed.
The foreclosure process in Arkansas begins with the issuance of the Arkansas Mortgagee's Notice of Default And Intention to Sell. This notice informs the homeowner of the default and the intention to proceed with foreclosure. Generally, the lender must follow legal steps, including giving notice, conducting a sale, and allowing a redemption period, all aimed at resolving the mortgage default.
In a foreclosure, the homeowner typically bears the greatest loss, facing potential homelessness and damage to their credit score. Additionally, the lender loses the investment made in the property, especially during the foreclosure process following the Arkansas Mortgagee's Notice of Default And Intention to Sell. Both parties endure financial stresses, highlighting the importance of exploring options early on.
The notice of default doesn't affect your credit file, but when the account defaults this will be recorded.If the debt is regulated by the Consumer Credit Act, you must be sent a default notice warning letter and have time to act on it before the default is recorded on your credit file.
A notice of default is the first step to a bank or mortgage lender's foreclosure process.If the mortgage is not paid up to date, the lender will seize the home. A notice of default is also known as a reinstatement period, notice of public auction, or notice of foreclosure.
A few potential ways to stop a foreclosure include reinstating the loan, redeeming the property before the sale, or filing for bankruptcy. (Of course, if you're able to work out a loss mitigation option, like a loan modification, that will also stop a foreclosure.)
After the lender files the Notice of Default, you get 90 days to bring your past-due bill current. After the 90 days pass, the lender files a Notice of Sale with the clerk. The Notice of Sale displays the location, date and time of the sale. It lists the trustee's name and contact information.
In Arkansas, lenders may foreclose on deeds of trusts or mortgages in default using either a judicial or non-judicial foreclosure process. However, an appraisal of the property must be made prior to the schedule date of foreclosure.