Utah Deed in Lieu of Foreclosure
Understanding this form
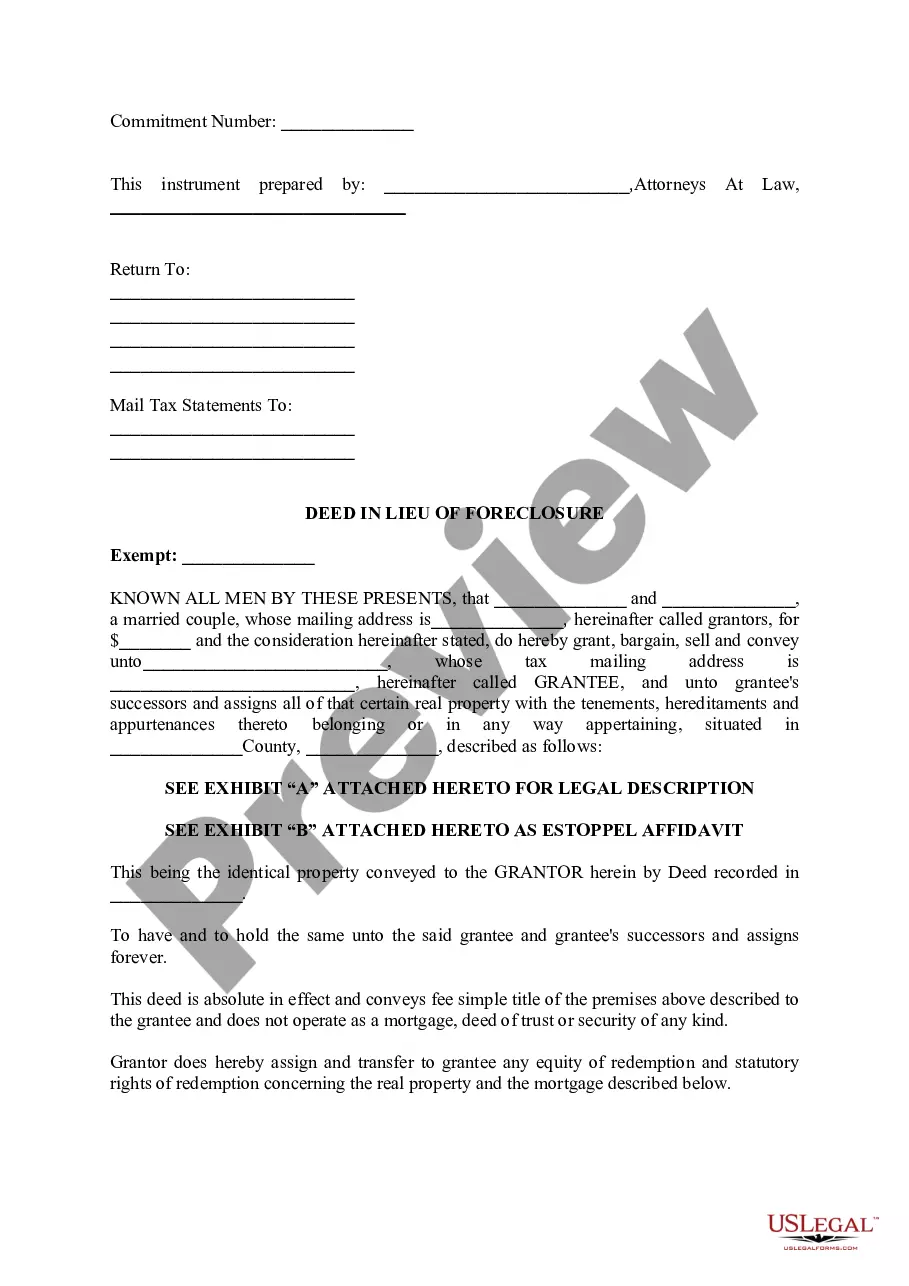
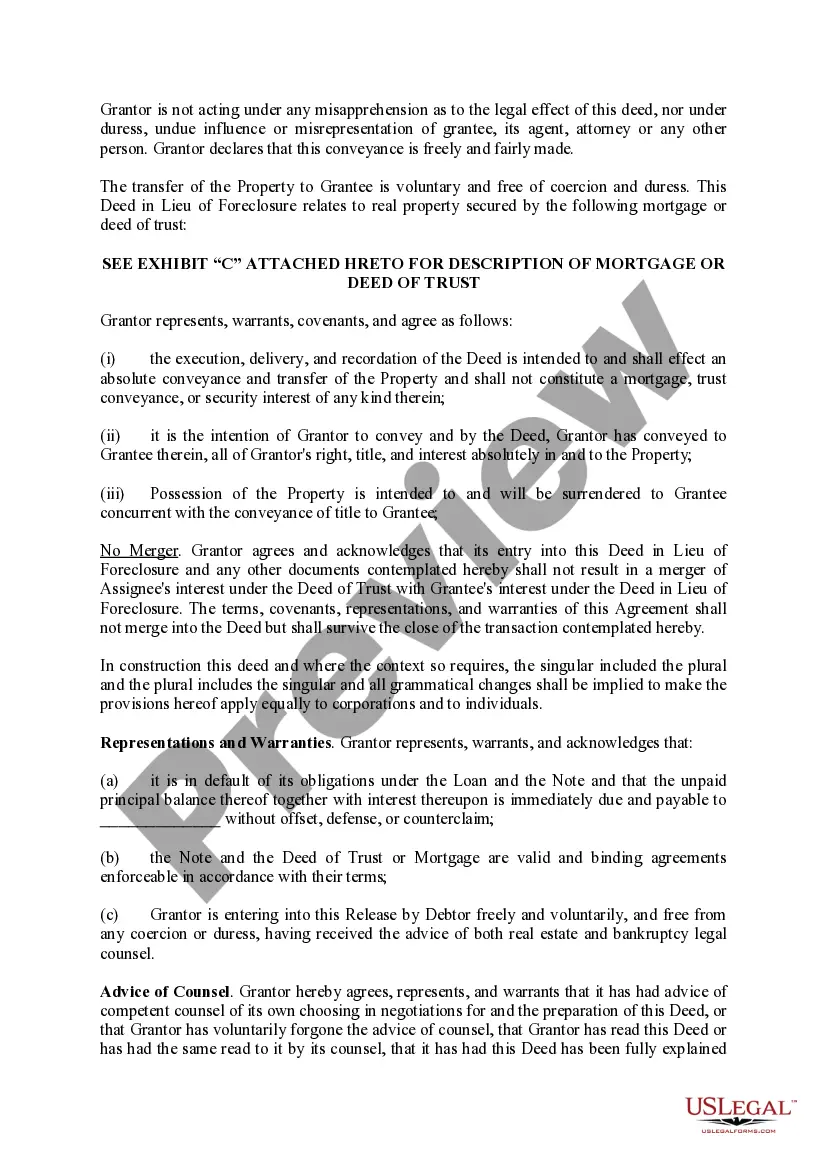
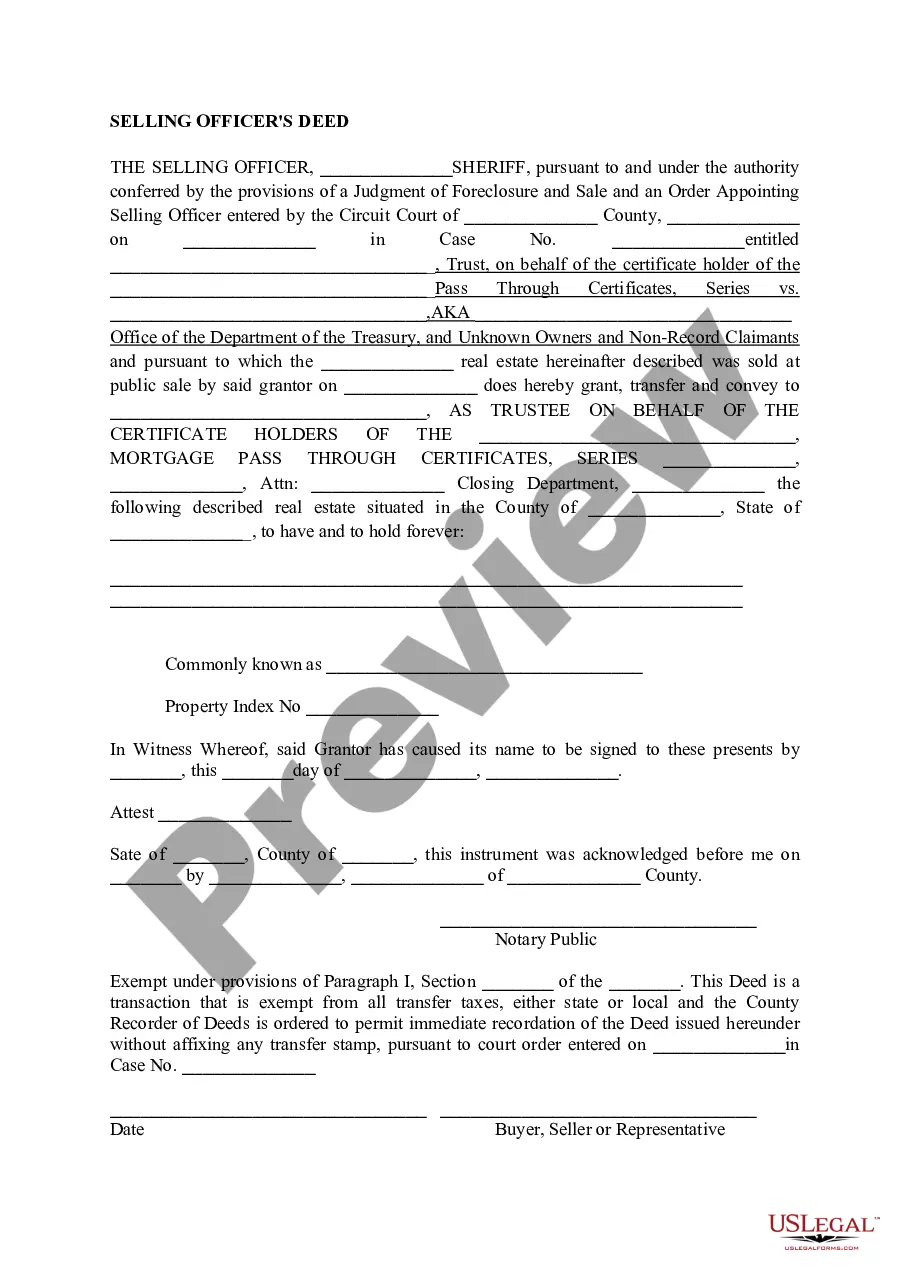
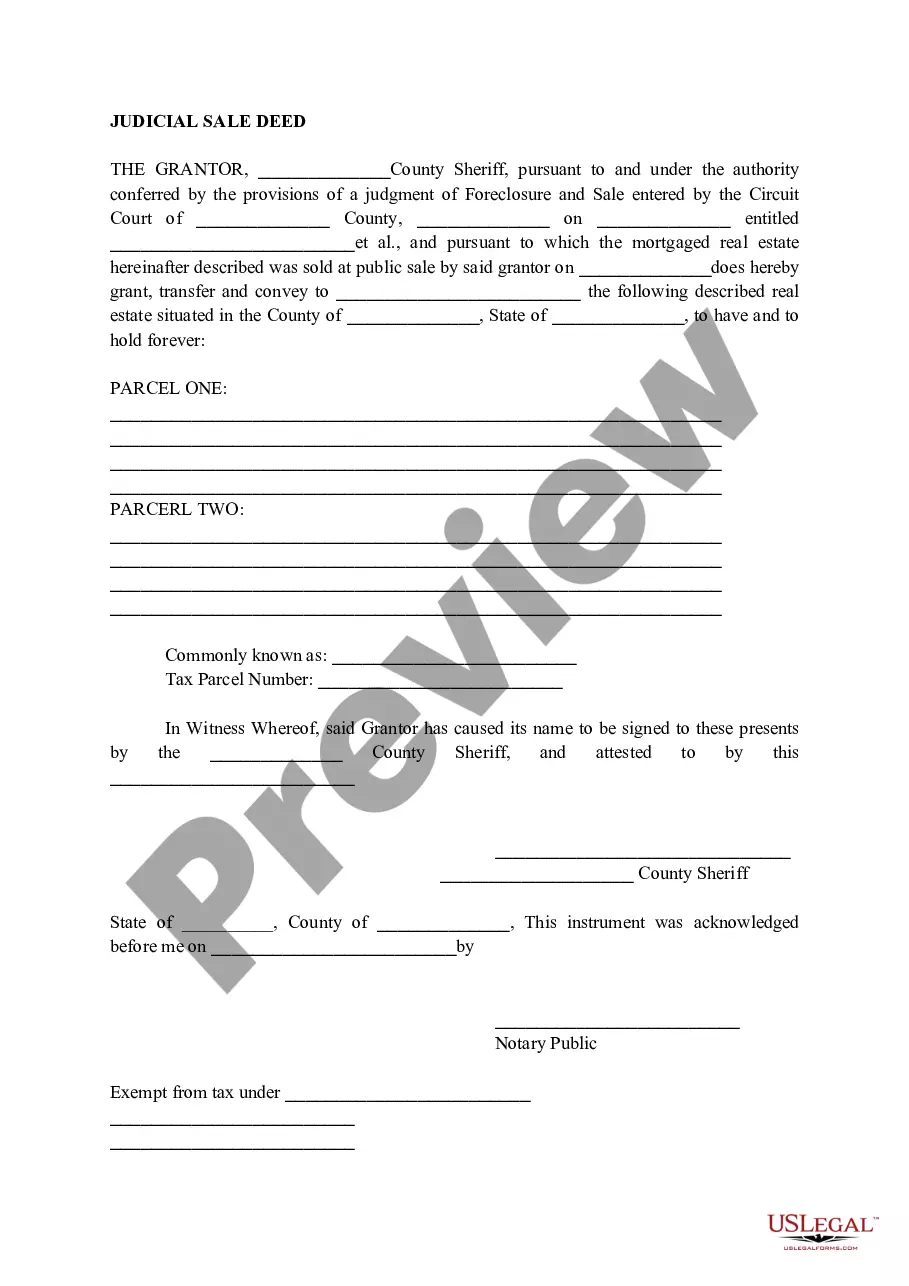
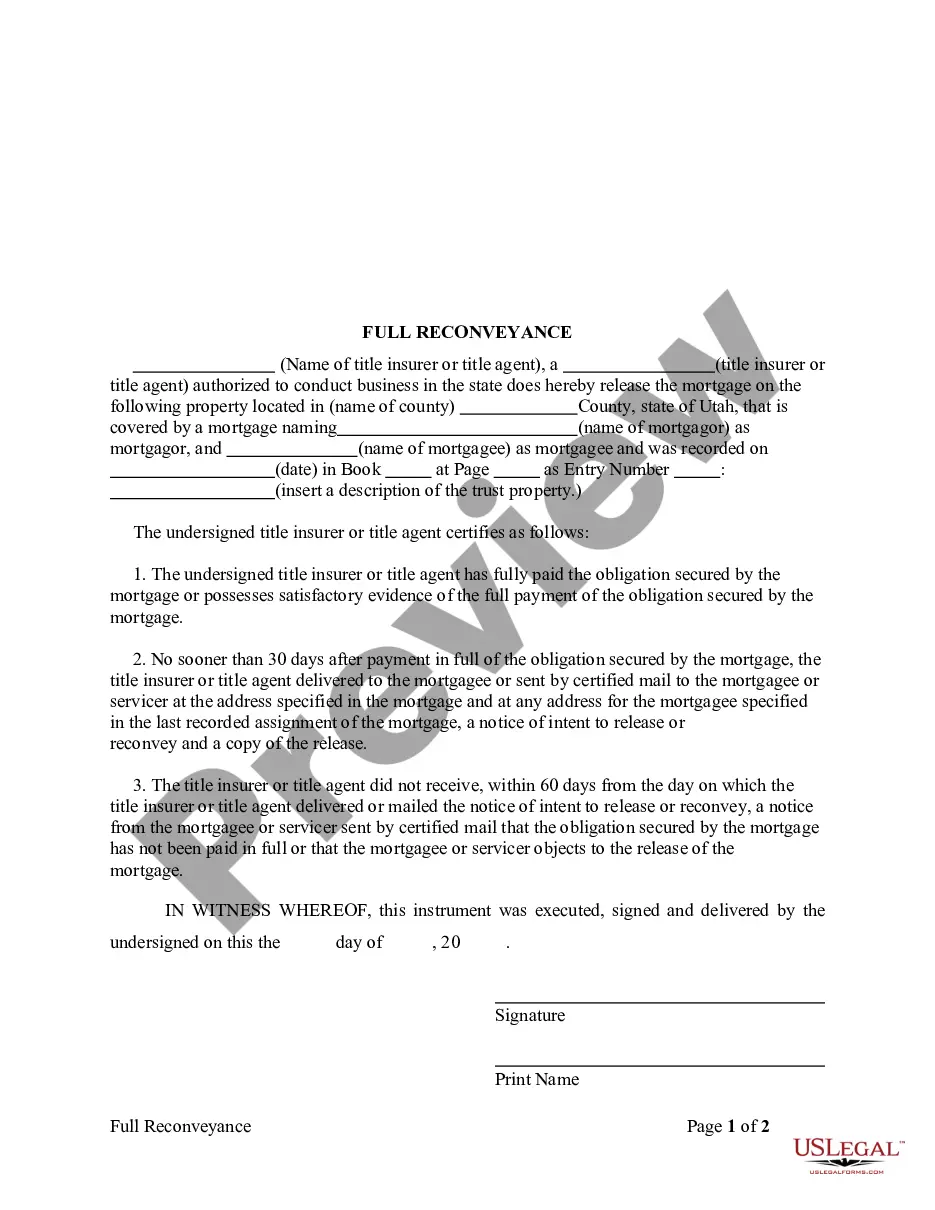
A Deed in Lieu of Foreclosure is a legal document that allows a property owner to transfer ownership of their property to the lender to avoid foreclosure. This process can help both the borrower and the lender save time and money compared to a traditional foreclosure. Unlike a foreclosure, which is a lengthy court process, a deed in lieu enables the homeowner to voluntarily hand over the property, eliminating the need for foreclosure proceedings.
What’s included in this form
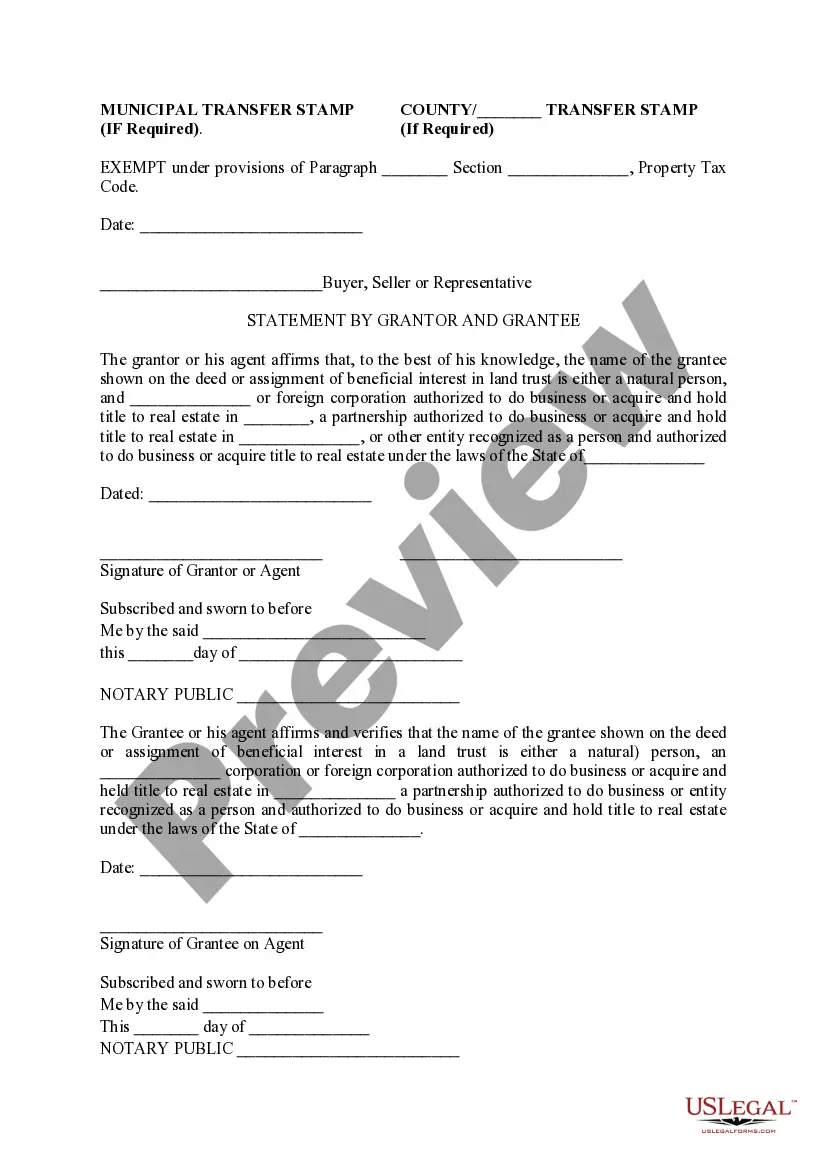
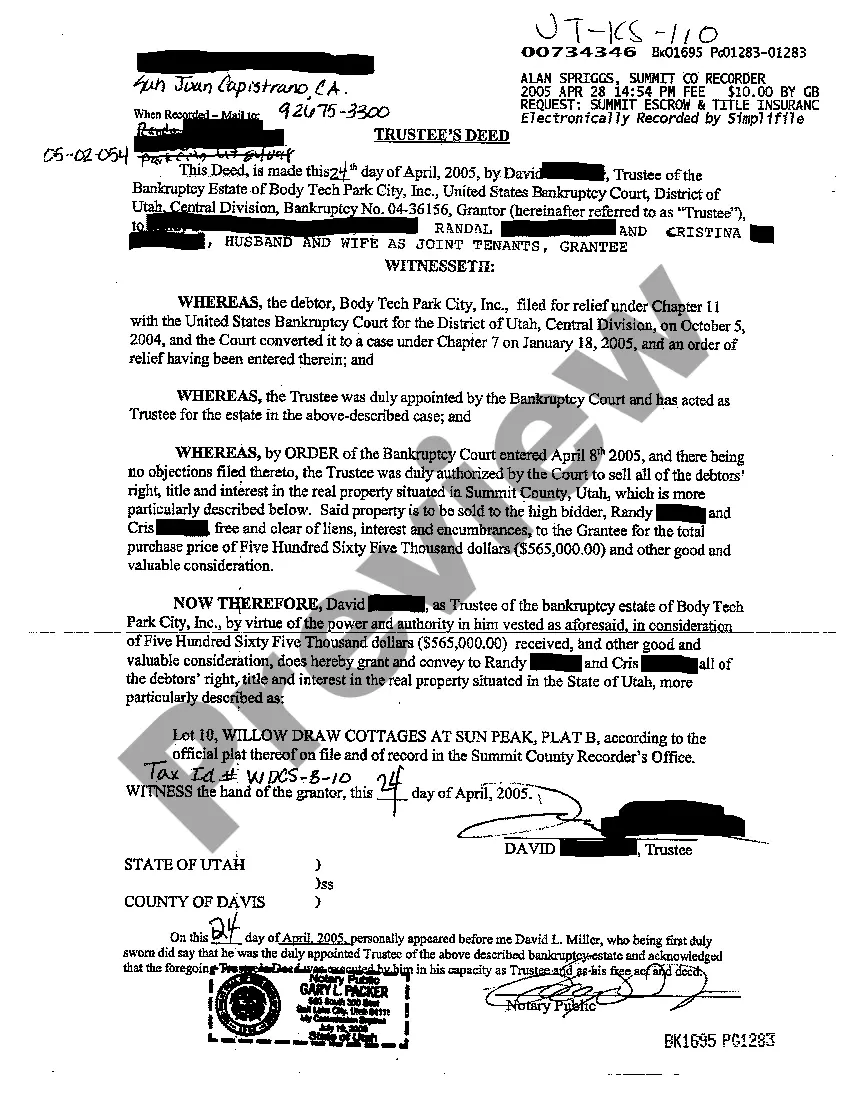
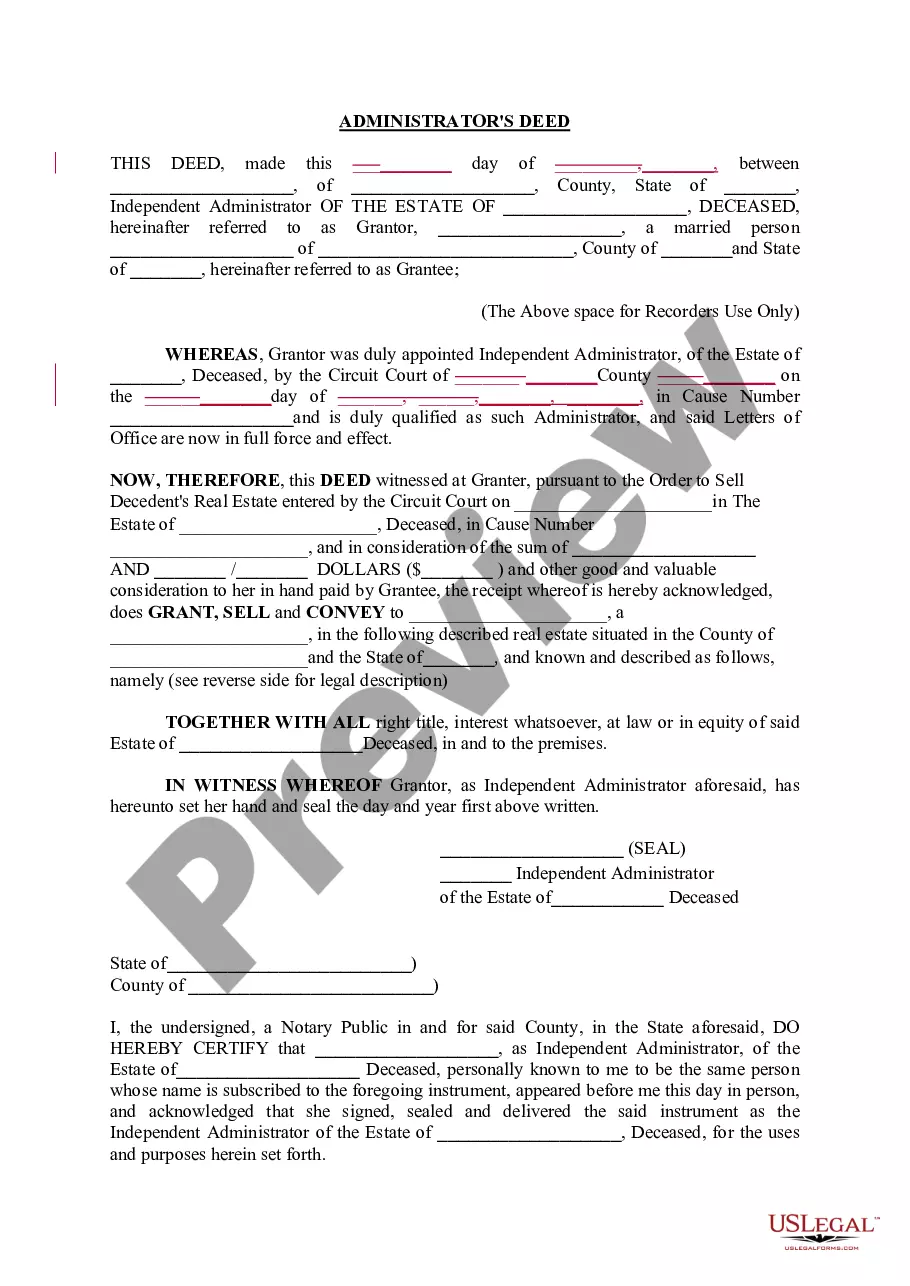
- Identification of grantor and grantee, including legal names and addresses.
- Consideration amount, indicating any financial settlement or agreement.
- Description of the property being transferred, including legal descriptions in attached exhibits.
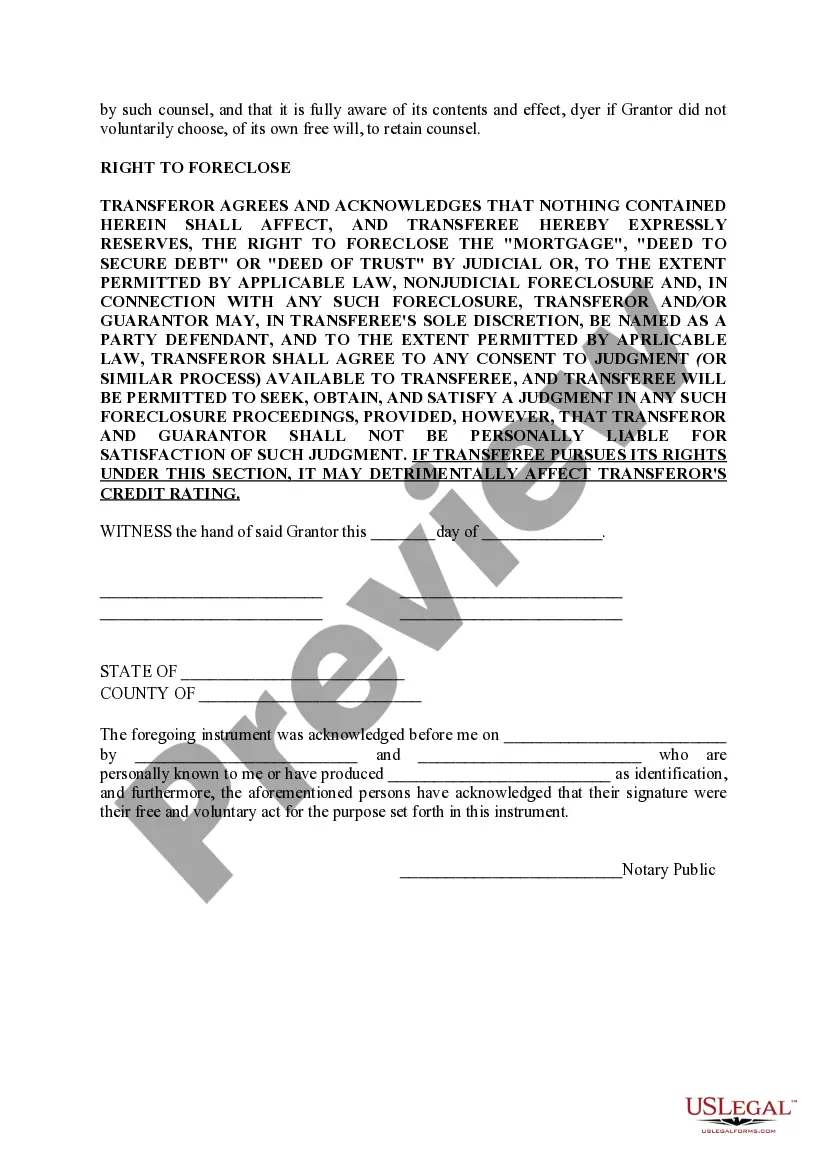
- Warranties and representations by the grantor regarding their authority to execute the deed.
- Notary section for acknowledgment and verification of signatures.
When this form is needed
This form is typically used when a homeowner is unable to continue making mortgage payments and wishes to avoid the complexities and costs of foreclosure. It can be beneficial in situations where the propertyâs value is less than the mortgage owed or when the homeowner seeks a quick resolution to their financial difficulties.
Who this form is for
- Homeowners facing financial hardship who can no longer meet mortgage obligations.
- Lenders looking to simplify the transfer of property ownership instead of pursuing foreclosure.
- Real estate professionals assisting clients in managing distressed properties.
How to prepare this document
- Identify the parties: Fill in the names and addresses of the grantor(s) and grantee.
- Specify the property: Clearly describe the real estate involved, referencing any attached legal descriptions.
- Enter the consideration amount: Provide the amount agreed upon for the deed transfer.
- Complete warranties: Ensure all required warranties and representations are accurately filled out by the grantor.
- Sign and notarize: Ensure all parties sign the document in the presence of a notary public to validate the transfer.
Is notarization required?
Yes, this form must be notarized to be legally valid. Notarization confirms the identity of the parties and ensures that the document is executed willingly. US Legal Forms offers integrated online notarization services, allowing for secure video calls to complete this process without the need for in-person meetings.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Mistakes to watch out for
- Failing to include accurate property descriptions, which can lead to complications in the transfer.
- Not having the document notarized, which may render it invalid in some jurisdictions.
- Missing signatures from all necessary parties involved in the transfer.
Benefits of using this form online
- Convenience of completing the form from home, avoiding trips to legal offices.
- Editable fields that allow for easy customization based on specific needs.
- Access to professionally drafted documents reviewed by licensed attorneys, ensuring legal compliance.
Looking for another form?
Form popularity
FAQ
Both short sales and deeds in lieu can help homeowners avoid foreclosure.One benefit to these options is that that you won't have a foreclosure on your credit history. But your credit score will still take a major hit. A short sale or deed in lieu is almost as bad as a foreclosure when it comes to credit scores.
A deed in lieu can eliminate your deficiency if you owe more on your home than the home is worth. In exchange for giving the lender your deed voluntarily and keeping the home in good condition, your lender may agree to forgive your deficiency or greatly reduce it.
The impact that a deed in lieu has on your score depends primarily on your credit history.According to FICO, if you start with a score of around 780, a deed in lieu (without a deficiency balance) shaves 105 to 125 points off your score; but if you start with a score of 680, you'll lose 50 to 70 points.
A deed in lieu of foreclosure is different from a short sale because it transfers the property to the lender instead of selling it to a new buyer.Similar to a short sale, a deed in lieu of foreclosure likely will not damage your credit as severely as a foreclosure or a bankruptcy.
If your lender agrees to a short sale or to accept a deed in lieu of foreclosure, you might owe federal income tax on any forgiven deficiency. The IRS learns of the deficiency when the lender sends it a Form 1099-C, which reports the forgiven debt as income to you.
C. The purchaser must pay off both the mortgage and junior lienholders after the sale. What is a major disadvantage to lenders of accepting a deed in lieu of foreclosure?The lender gains rights to private mortgage insurance.
The deed in lieu of foreclosure offers several advantages to both the borrower and the lender. The principal advantage to the borrower is that it immediately releases him/her from most or all of the personal indebtedness associated with the defaulted loan.