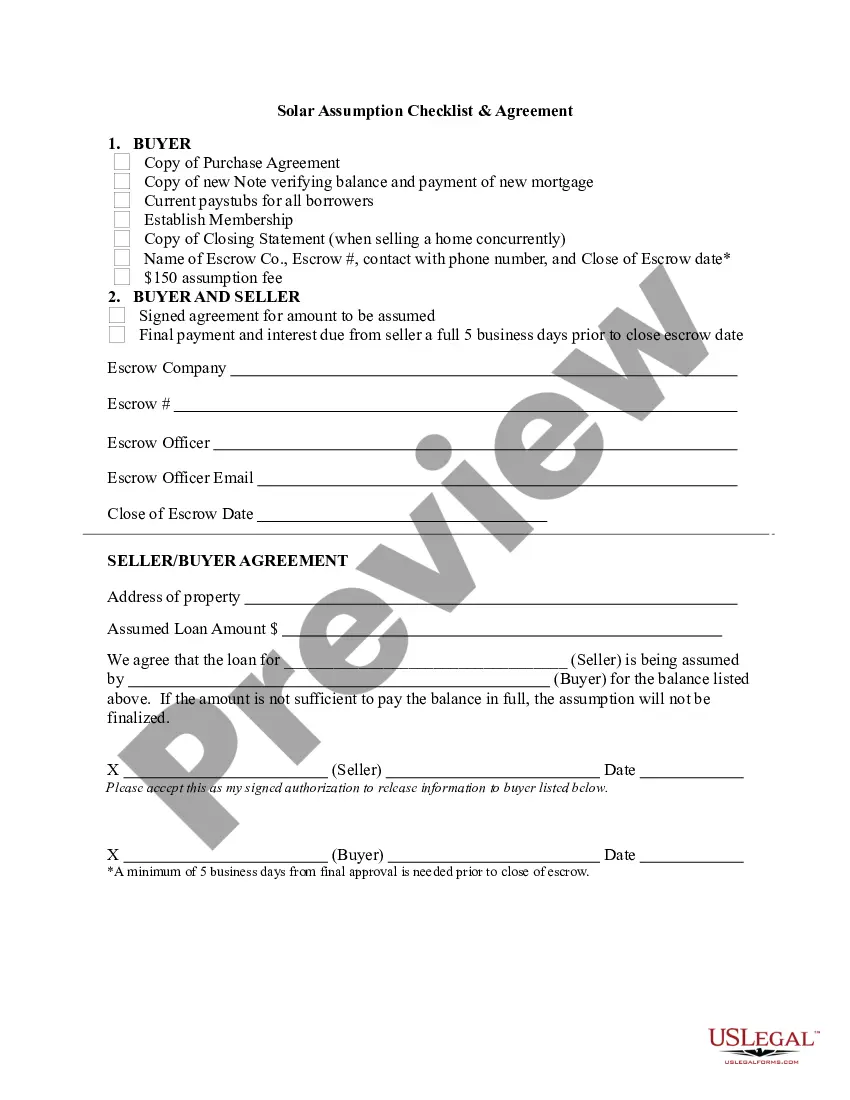
Solar Assumption Checklist and Agreement
What this document covers
The Solar Assumption Checklist and Agreement is a legal document that allows a new borrower (referred to as the Buyer) to take over an existing solar loan from the previous borrower (the Seller). This form outlines the necessary steps and requirements for successfully assuming a solar loan, making it distinct from other financing agreements. It serves to clarify the responsibilities of both parties in the transaction and ensures compliance with legal standards applicable to solar financing.
Key parts of this document
- Identification of the Buyer and Seller, including relevant agreements and documentation.
- Financial disclosures such as pay stubs, mortgage balance, and payment details.
- Details of the escrow process, including contact information and escrow number.
- Written consent between Buyer and Seller for the loan amount to be assumed.
- Signatures of both parties to validate the agreement.
When this form is needed
This form is needed when a Buyer wishes to assume a solar loan of the Seller as part of a property transfer. It is particularly useful in transactions involving homes with existing solar financing arrangements, ensuring that all legalities are addressed and the loan is properly transferred to the new owner.
Who this form is for
- Home buyers who want to take over a solar loan from the seller.
- Home sellers who are transferring their solar financing to a new borrower.
- Real estate agents or brokers facilitating the sale of a property with a solar loan.
- Legal professionals assisting clients with solar loan assumptions.
How to prepare this document
- Identify the parties involved by including names and contact information for both the Buyer and Seller.
- Gather and attach the necessary documentation such as the purchase agreement and pay stubs.
- Specify loan details, including the assumed loan amount and the location of the property.
- Ensure all signatures and dates are correctly filled out for both Buyer and Seller.
- Submit the completed checklist along with the assumption fee to the escrow company.
Notarization guidance
This form does not typically require notarization unless specified by local law. Users should check state regulations for any additional requirements that may apply to their specific situation.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Mistakes to watch out for
- Failing to gather required documentation before submitting the form.
- Not providing accurate financial information or assumptions details.
- Neglecting to obtain the necessary signatures from both parties.
- Missing the five-business-day requirement for final approval before closing.
Why use this form online
- Convenience of downloading and completing the form anytime and anywhere.
- Editability allows users to easily customize the form to their specific transaction.
- Access to attorney-drafted content ensures reliability and compliance with state laws.
Looking for another form?
Form popularity
FAQ
Monthly rent or house payment. Monthly alimony or child support payments. Student, auto, and other monthly loan payments. Credit card monthly payments (use the minimum payment)
How do solar panel payments potentially affect qualifications? If there is a production guarantee in your lease agreement or the ownership agreement, the lender will not count the loan payment or the lease payment against you.
Two popular types of home loans that accept high DTIs are FHA and VA loans. FHA loans may take a DTI up to 50%. Also, you don't need to have an excellent credit score to qualify for an FHA loan. VA loans are recognized as the most lenient.
What is a Solar Assumption? A Solar Assumption, or Solar Loan Assumption, is a type of financing arrangement whereby a new borrower (the ?buyer?) takes over the existing solar loan of another borrower (the ?seller?).
Yes ? all loans or lease payments change your debt to income ratio.
Most conventional loans allow for a DTI of no more than 45 percent, but some lenders will accept ratios as high as 50 percent if the borrower has compensating factors, such as a savings account with a balance equal to six months' worth of housing expenses.