Qualified Subchapter-S Trust for Benefit of Child with Crummey Trust Agreement
Overview of this form
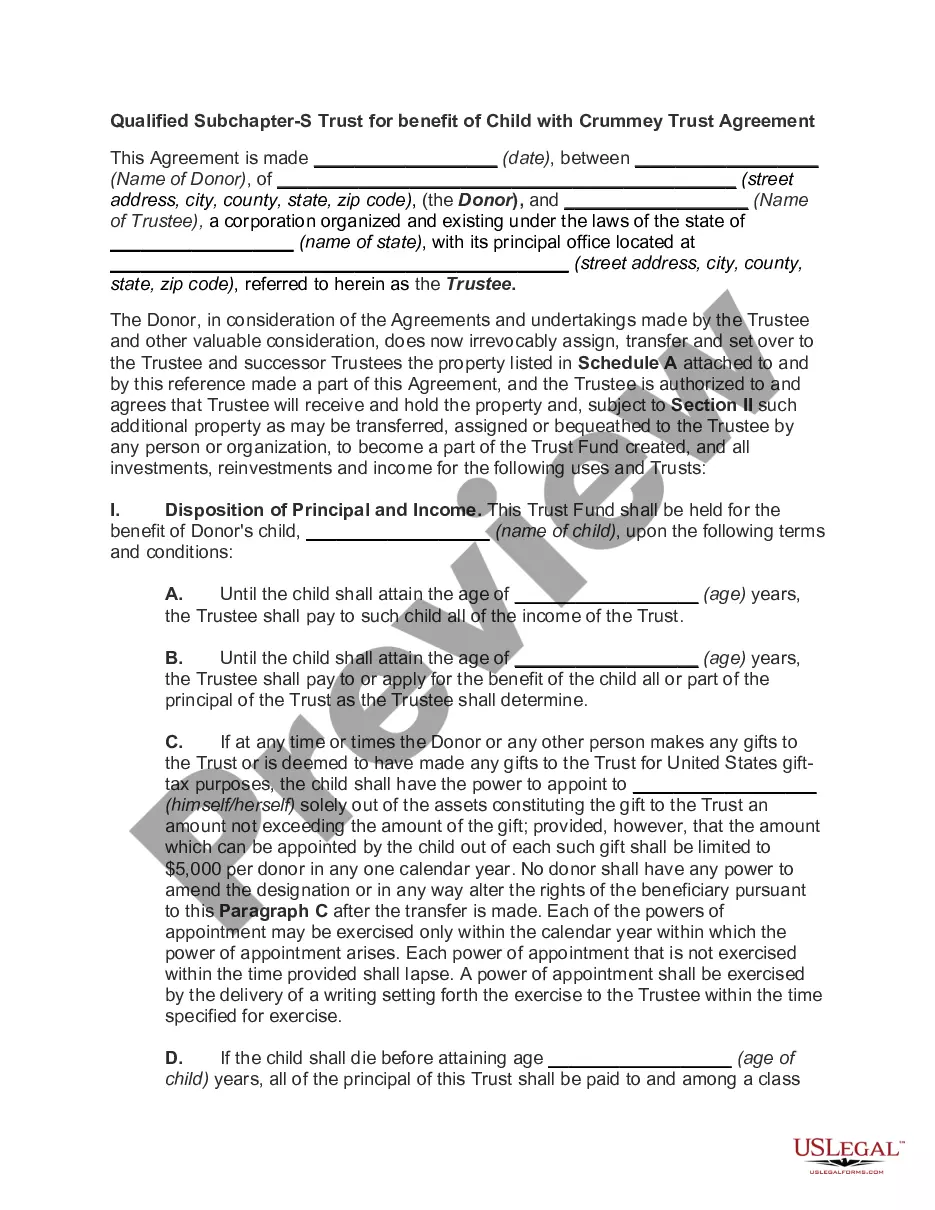
The Qualified Subchapter-S Trust for Benefit of Child with Crummey Trust Agreement is a legal document designed to manage assets for a minor child while allowing for specific tax benefits under U.S. tax law. This type of trust allows the child to receive income and principal distributions at specified ages while also holding potential tax advantages associated with a Subchapter-S corporation. Unlike standard trusts, this agreement incorporates a Crummey provision, which gives the beneficiary a limited right to withdraw contributions, ensuring compliance with gift tax regulations.
Key components of this form
- Identification of the donor and trustee, including contact details.
- Schedule A listing the property being transferred into the trust.
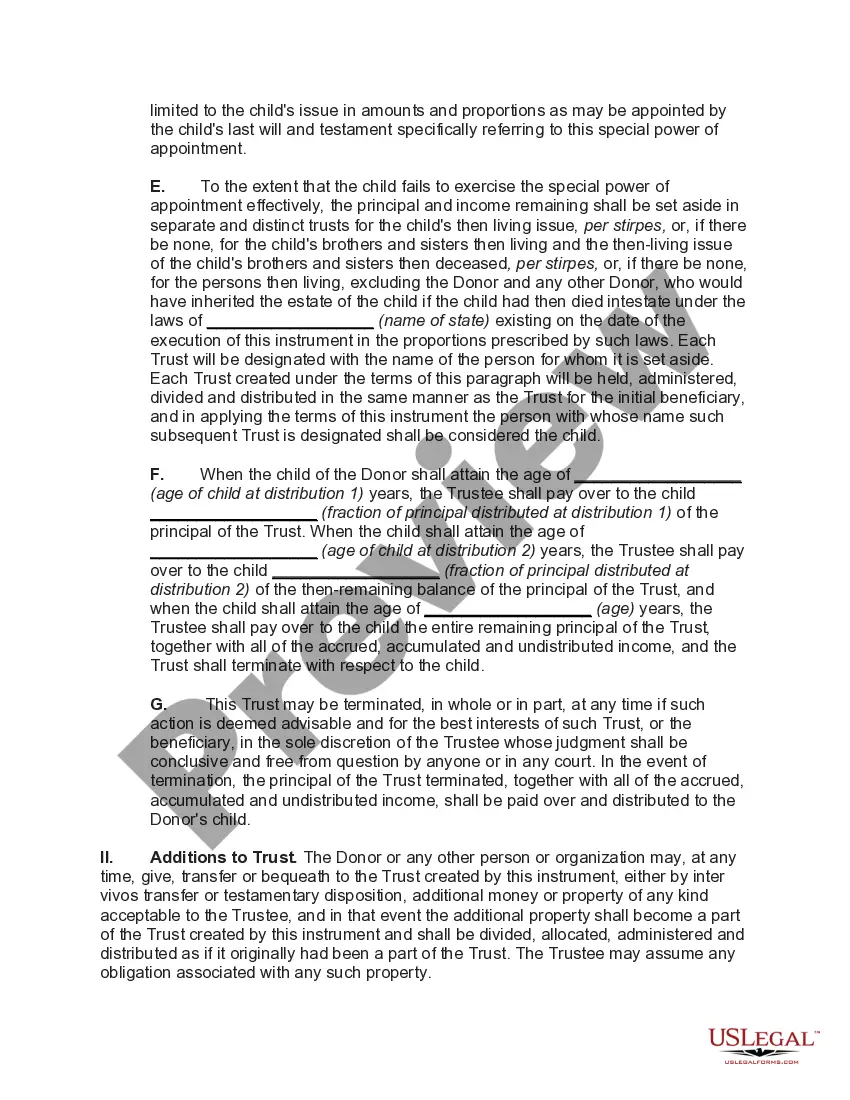
- Terms for the disposition of principal and income for the child.
- Special power of appointment allowing the child to control certain gifts.
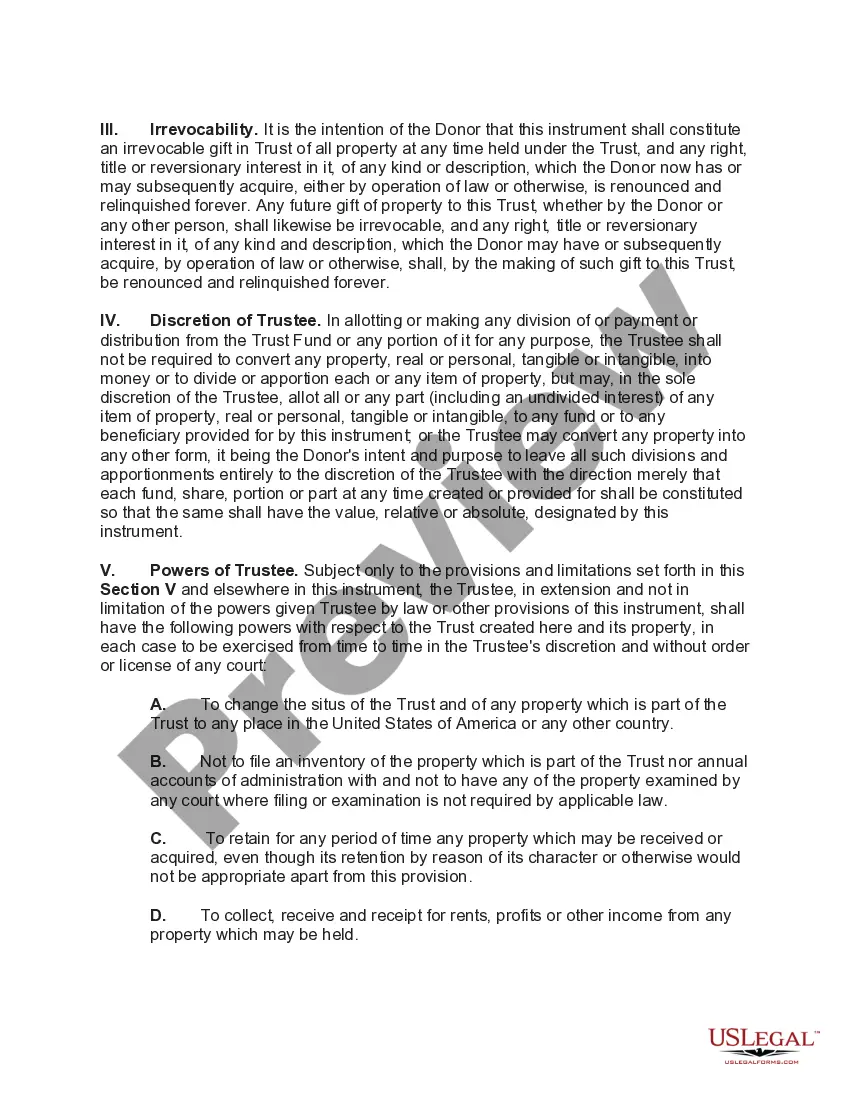
- Provisions for the trust's termination under specific conditions.
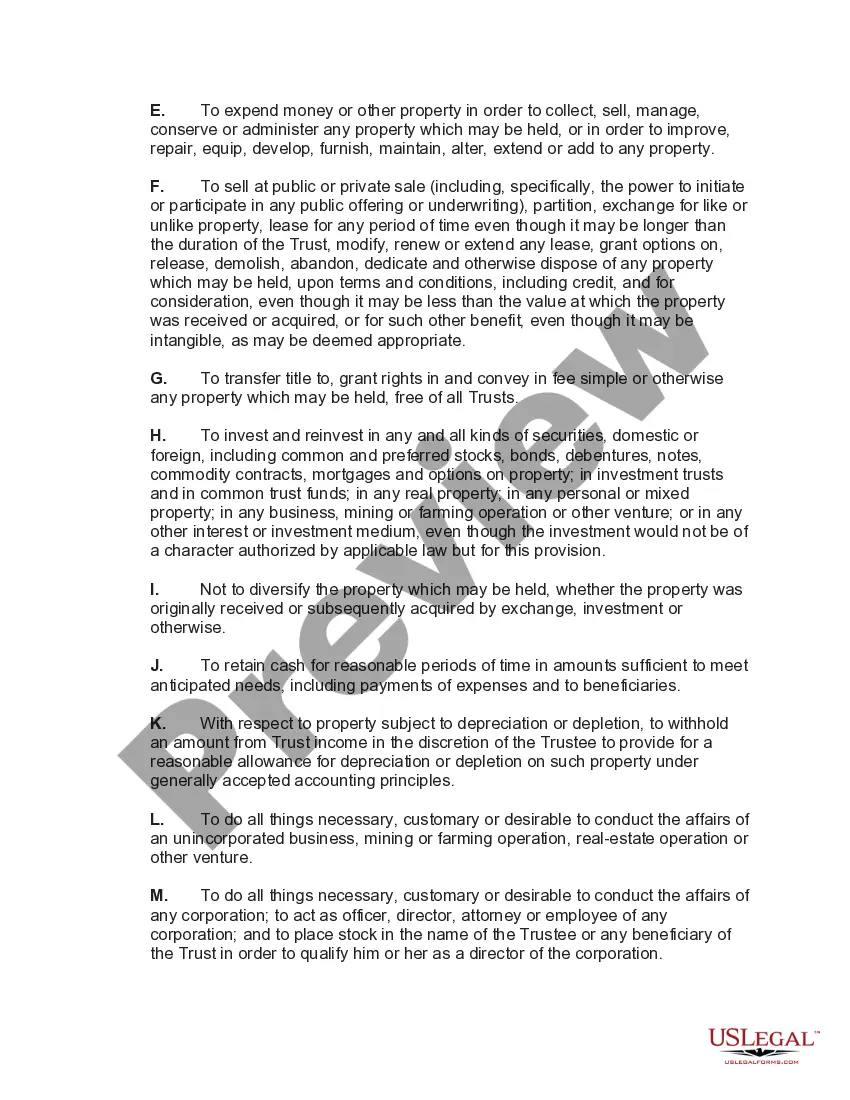
- Trustee's powers and limitations outlined for managing trust assets.
Situations where this form applies
This form is appropriate when a parent or guardian wishes to set up a trust for the financial benefit of a minor child, allowing for controlled management of assets until the child reaches maturity. It is particularly useful in estate planning, ensuring that the child has access to funds while also providing tax advantages and protecting the inheritance from potential creditors.
Who this form is for
- Parents or guardians wishing to establish a trust for their children.
- Individuals who want to take advantage of tax benefits for assets held in a trust.
- Donors looking to protect their child's inheritances from creditors.
Instructions for completing this form
- Identify and enter the date of the agreement and the names of the donor and trustee.
- Complete Schedule A with a detailed list of assets being transferred into the trust.
- Specify the age milestones for principal distributions to the child.
- Outline the terms for the special power of appointment if applicable.
- Have the donor and trustee sign and date the agreement in the presence of any required witnesses or notaries.
Notarization requirements for this form
Notarization is not commonly needed for this form. However, certain documents or local rules may make it necessary. Our notarization service, powered by Notarize, allows you to finalize it securely online anytime, day or night.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Common mistakes
- Failing to properly list all assets in Schedule A.
- Not specifying the correct ages for distributions which can lead to legal complications.
- Omitting signatures or required witness statements, rendering the document invalid.
Benefits of using this form online
- Convenience of downloading and customizing the form for your needs.
- Immediate access to a legally vetted template drafted by licensed attorneys.
- Ability to fill out the form at your own pace, ensuring accuracy and completeness.
Legal use & context
- This trust form provides a structure for asset management and distribution to benefit a minor child.
- The trust must adhere to IRS regulations to maintain its Subchapter-S status, affecting how it is administered and taxed.
- Consultation with an estate planning attorney is recommended to ensure proper implementation and compliance with laws.
What to keep in mind
- A Qualified Subchapter-S Trust can provide significant tax benefits while managing assets for a child.
- Properly identifying parties and assets is crucial for the trust's validity.
- Consult with a legal expert to ensure compliance with state-specific laws.
Looking for another form?


Form popularity
FAQ
A Qualified Subchapter S Trust, commonly referred to as a QSST Election, or a Q-Sub election, is a Qualified Subchapter S Subsidiary Election made on behalf of a trust that retains ownership as the shareholder of an S corporation, a corporation in the United States which votes to be taxed.
1361(d)(3), for a trust to qualify as a QSST, its terms must require that during the life of the current income beneficiary, the trust will have only one income beneficiary; and all of the trust's accounting income must either be required by the terms of the trust instrument to be distributed, or actually be
Generally, estates and six types of trusts are eligible as S corporation shareholders, these include grantor trusts, electing small business trusts (ESBTs), qualified subchapter S trusts (QSSTs), and testamentary trusts (for two years after funding.
If the trust is a grantor trust, testamentary trust, qualified Subchapter S trust (QSST), revocable trust, or retirement account trust, the trust counts as one shareholder. However, the number of beneficiaries of an electing small business trust (ESBT) or voting trust are all counted as shareholders for an S corp.
While there can only be one income beneficiary, a QSST may designate successor beneficiaries. With an ESBT, you can set up one trust that includes all of the income beneficiaries. However, note that any ESBT designated beneficiaries must be an individual, estate or charity eligible to own S corporation stock.
Only estates, individuals, and certain trusts can own shares in an S corp. Corporations, partnerships, and non-resident aliens cannot own stock.If the trust is a grantor trust, testamentary trust, qualified Subchapter S trust (QSST), revocable trust, or retirement account trust, the trust counts as one shareholder.
A Qualified Subchapter S Trust, commonly referred to as a QSST Election, or a Q-Sub election, is a Qualified Subchapter S Subsidiary Election made on behalf of a trust that retains ownership as the shareholder of an S corporation, a corporation in the United States which votes to be taxed.
In order to become an S corporation, the corporation must submit a completed Form 2553 (Election by a Small Business Corporation) that has been signed by all the shareholders. The following information must be provided: The corporation's name and address. The tax year when the election will take effect.