South Carolina Loan Modification Agreement
Understanding this form
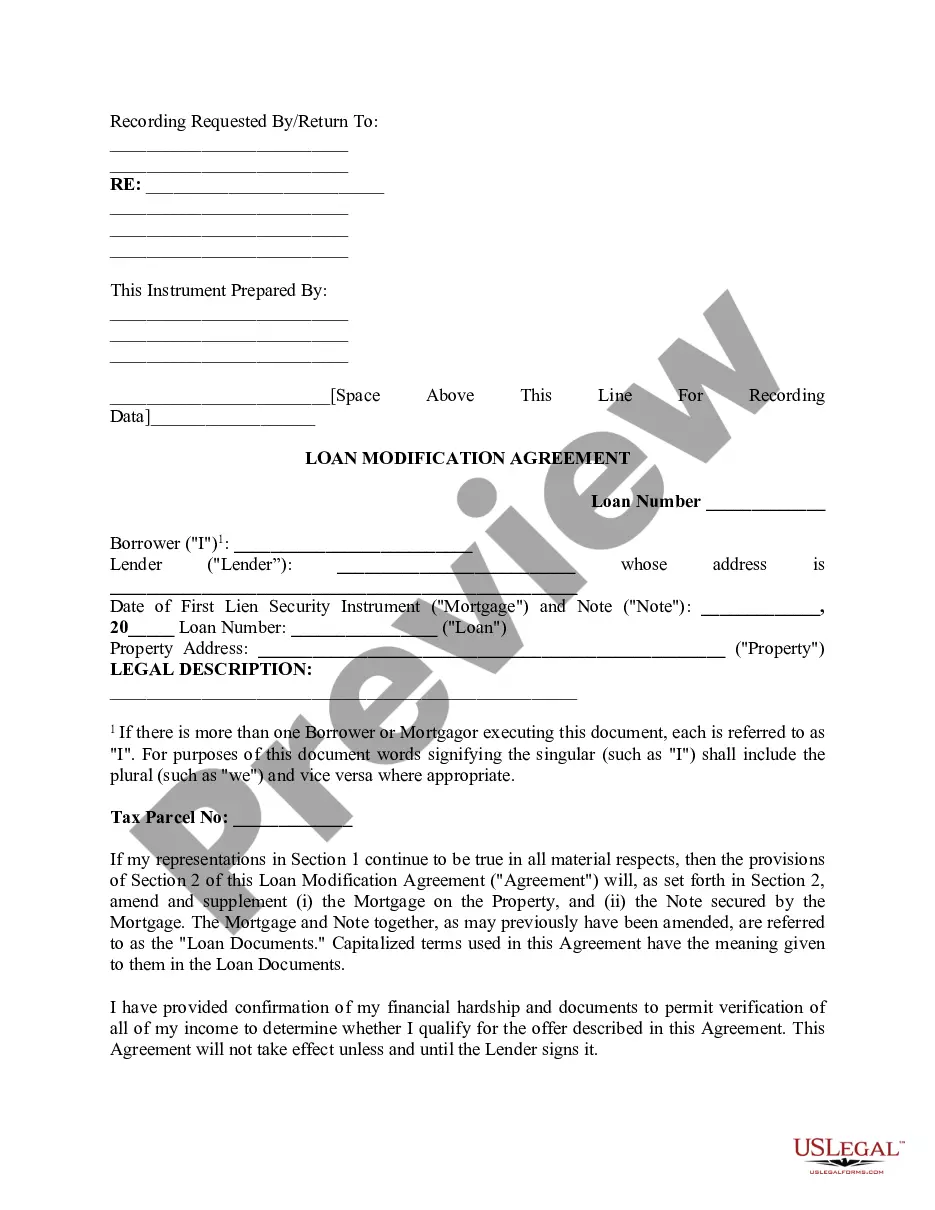
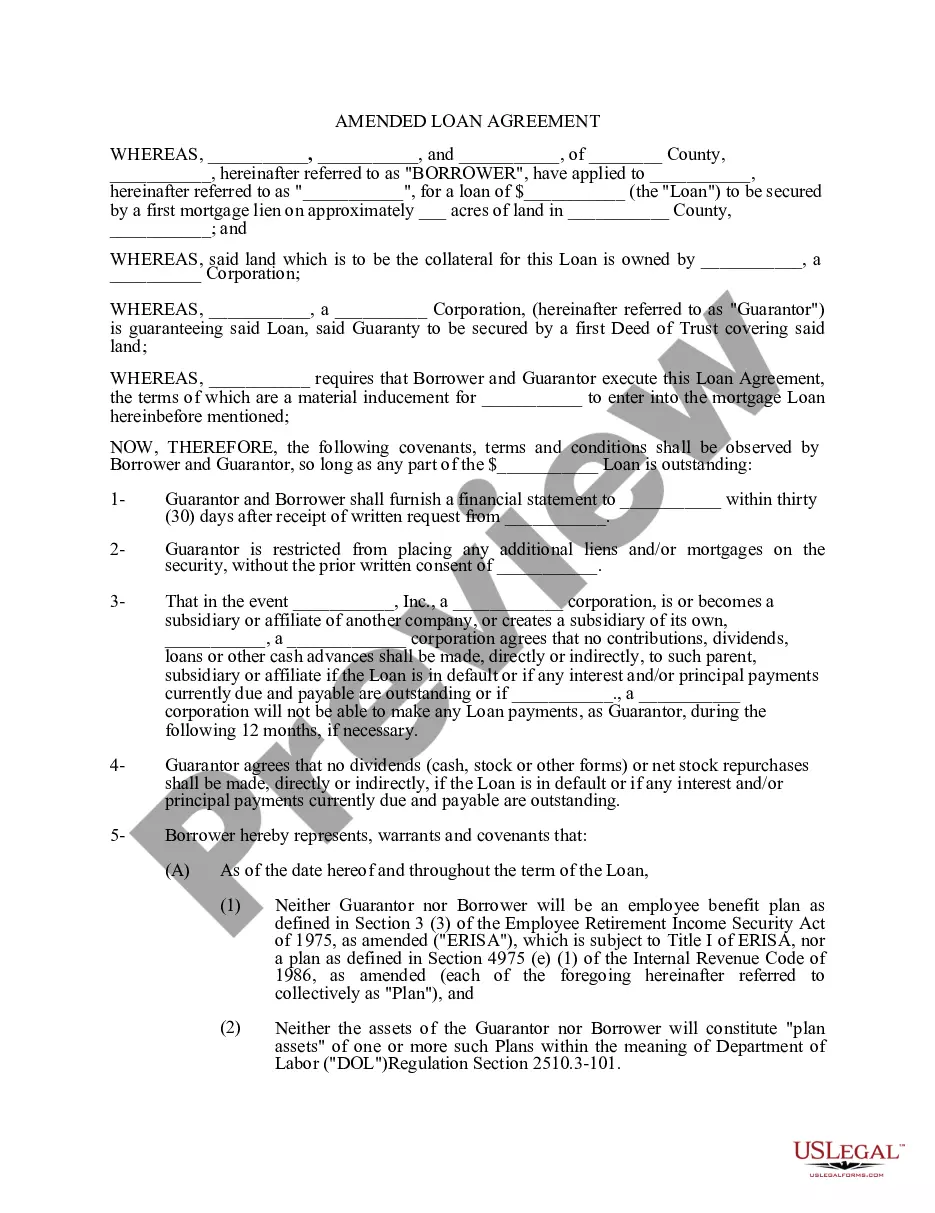
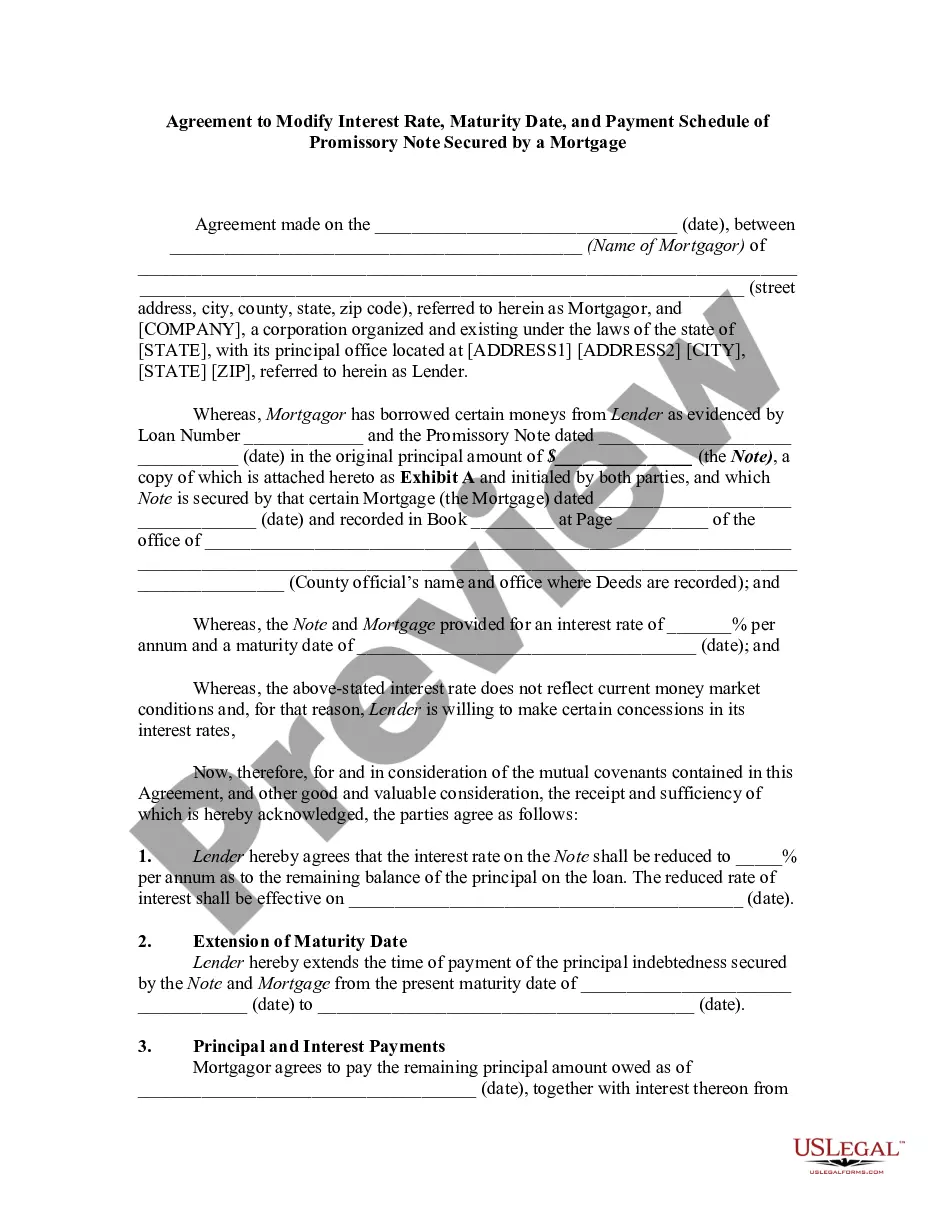
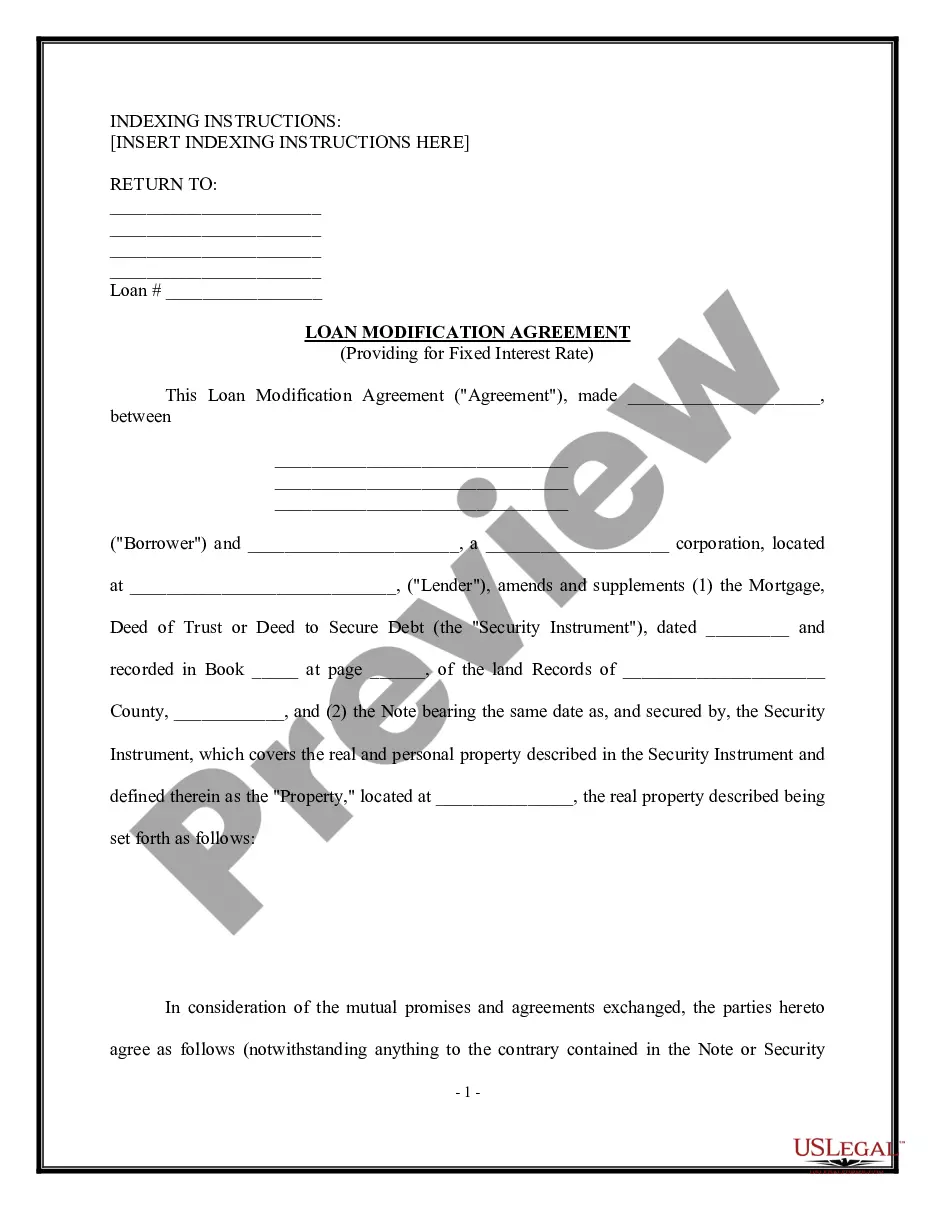
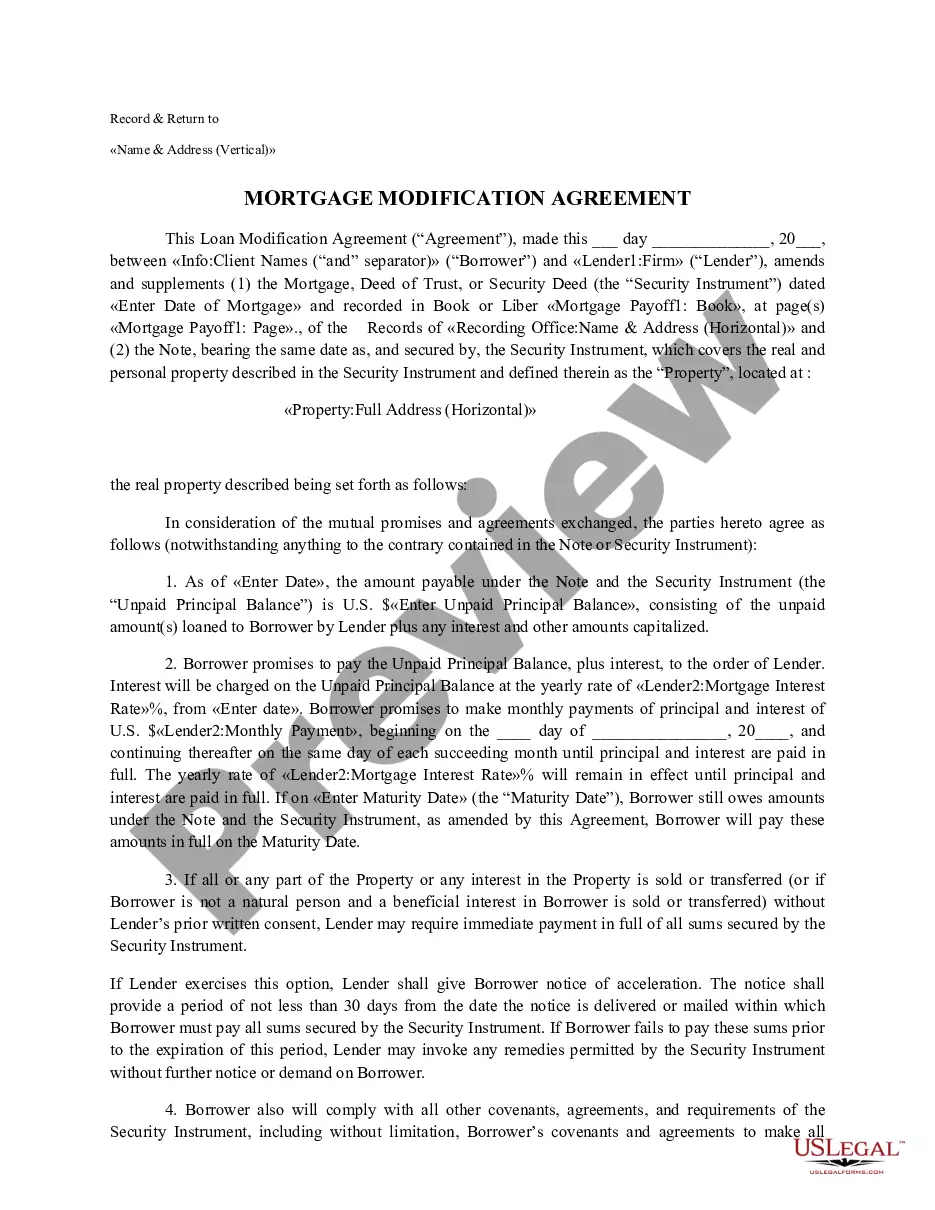
The Loan Modification Agreement is a legal document that enables borrowers to alter the terms of their mortgage with the lender. This modification can include adjustments to the payment amount, interest rate, or length of the loan, often making payments more affordable. Unlike a traditional mortgage agreement, this form specifically addresses changes due to financial hardship, offering a structured approach to help borrowers maintain their home while managing their debt.
Main sections of this form
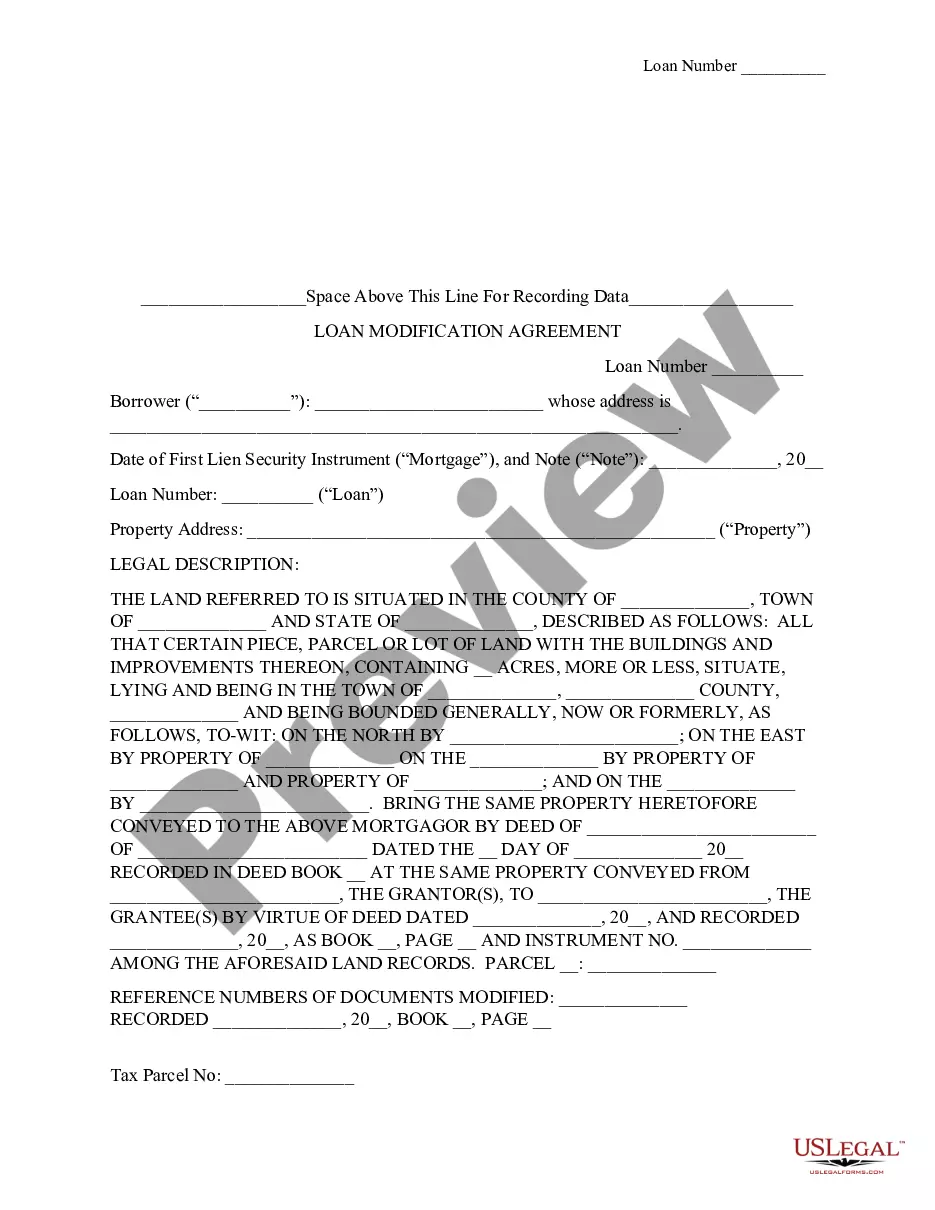
- Identification of parties: Names and addresses of the borrower and lender.
- Loan details: Information about the original loan number, property address, and legal description.
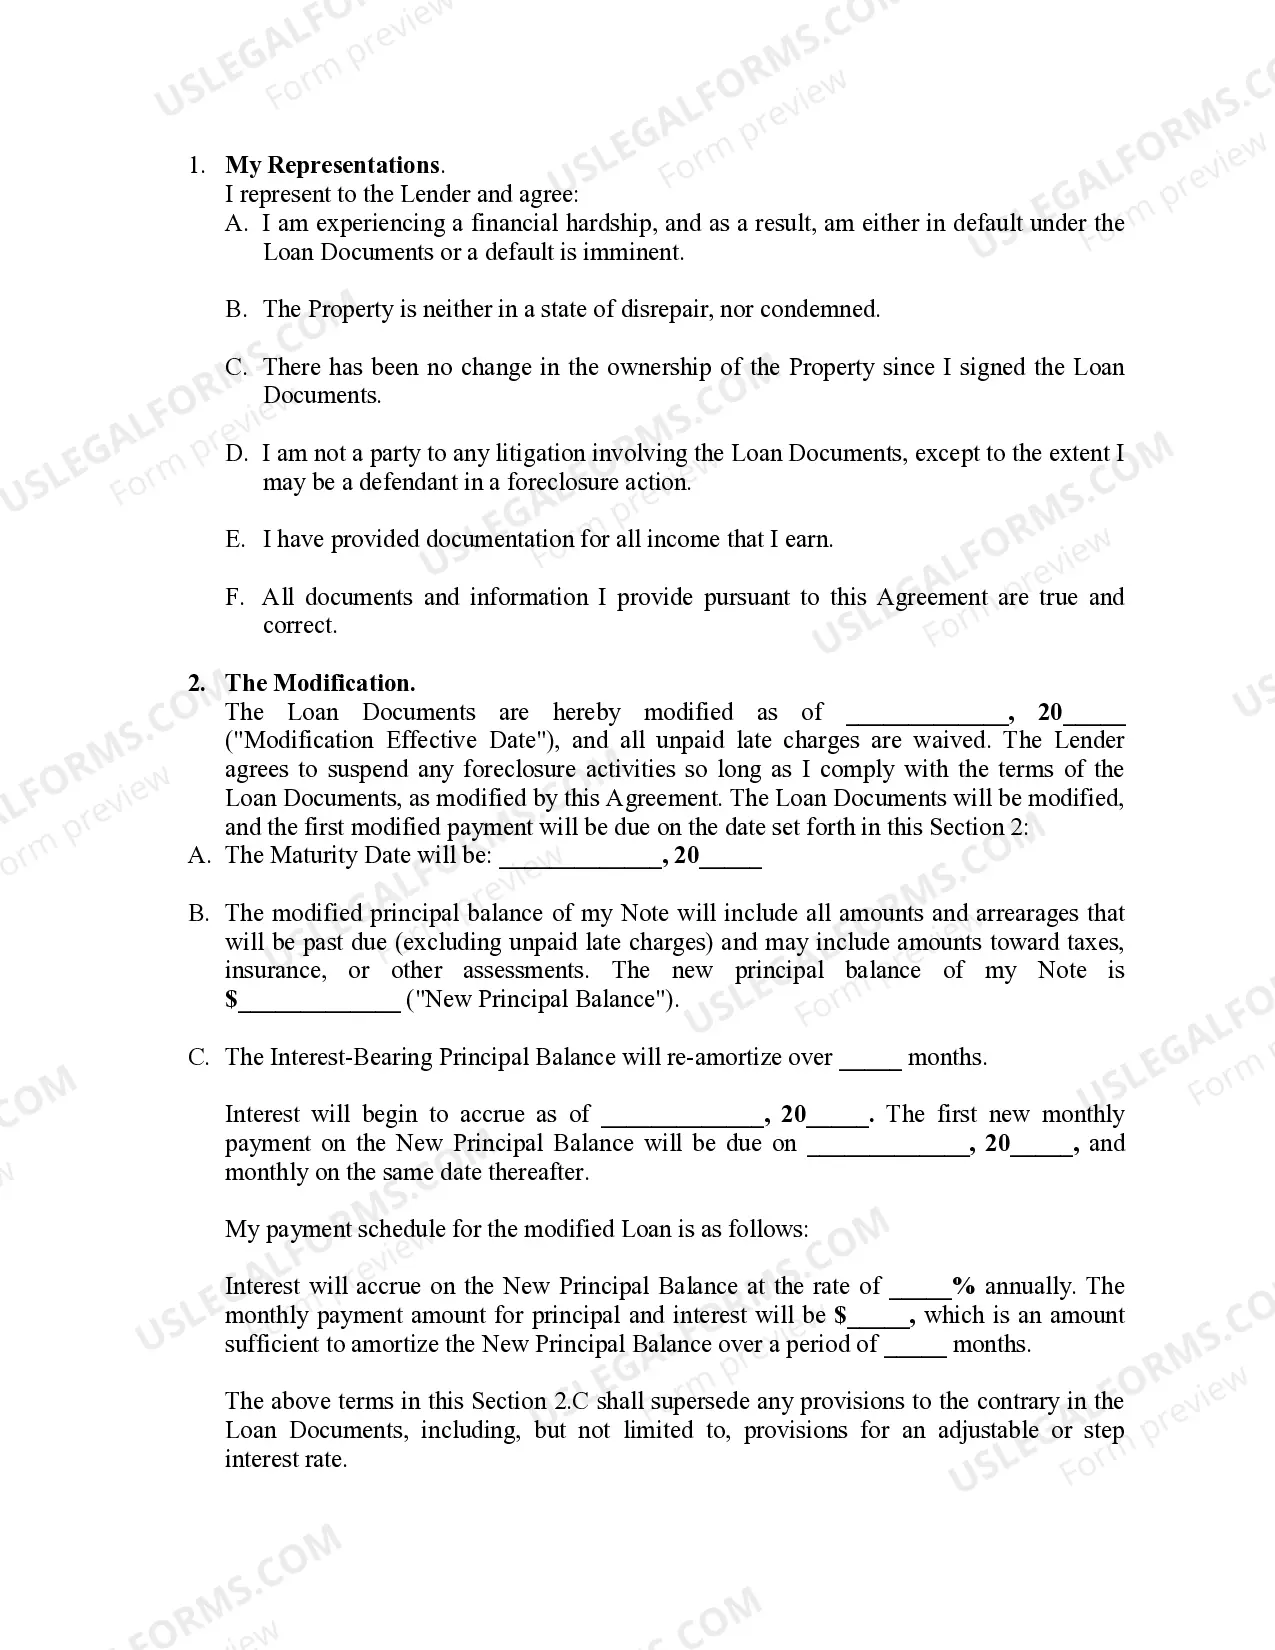
- Financial hardship declaration: A statement confirming the borrower's current financial situation and the necessity for modification.
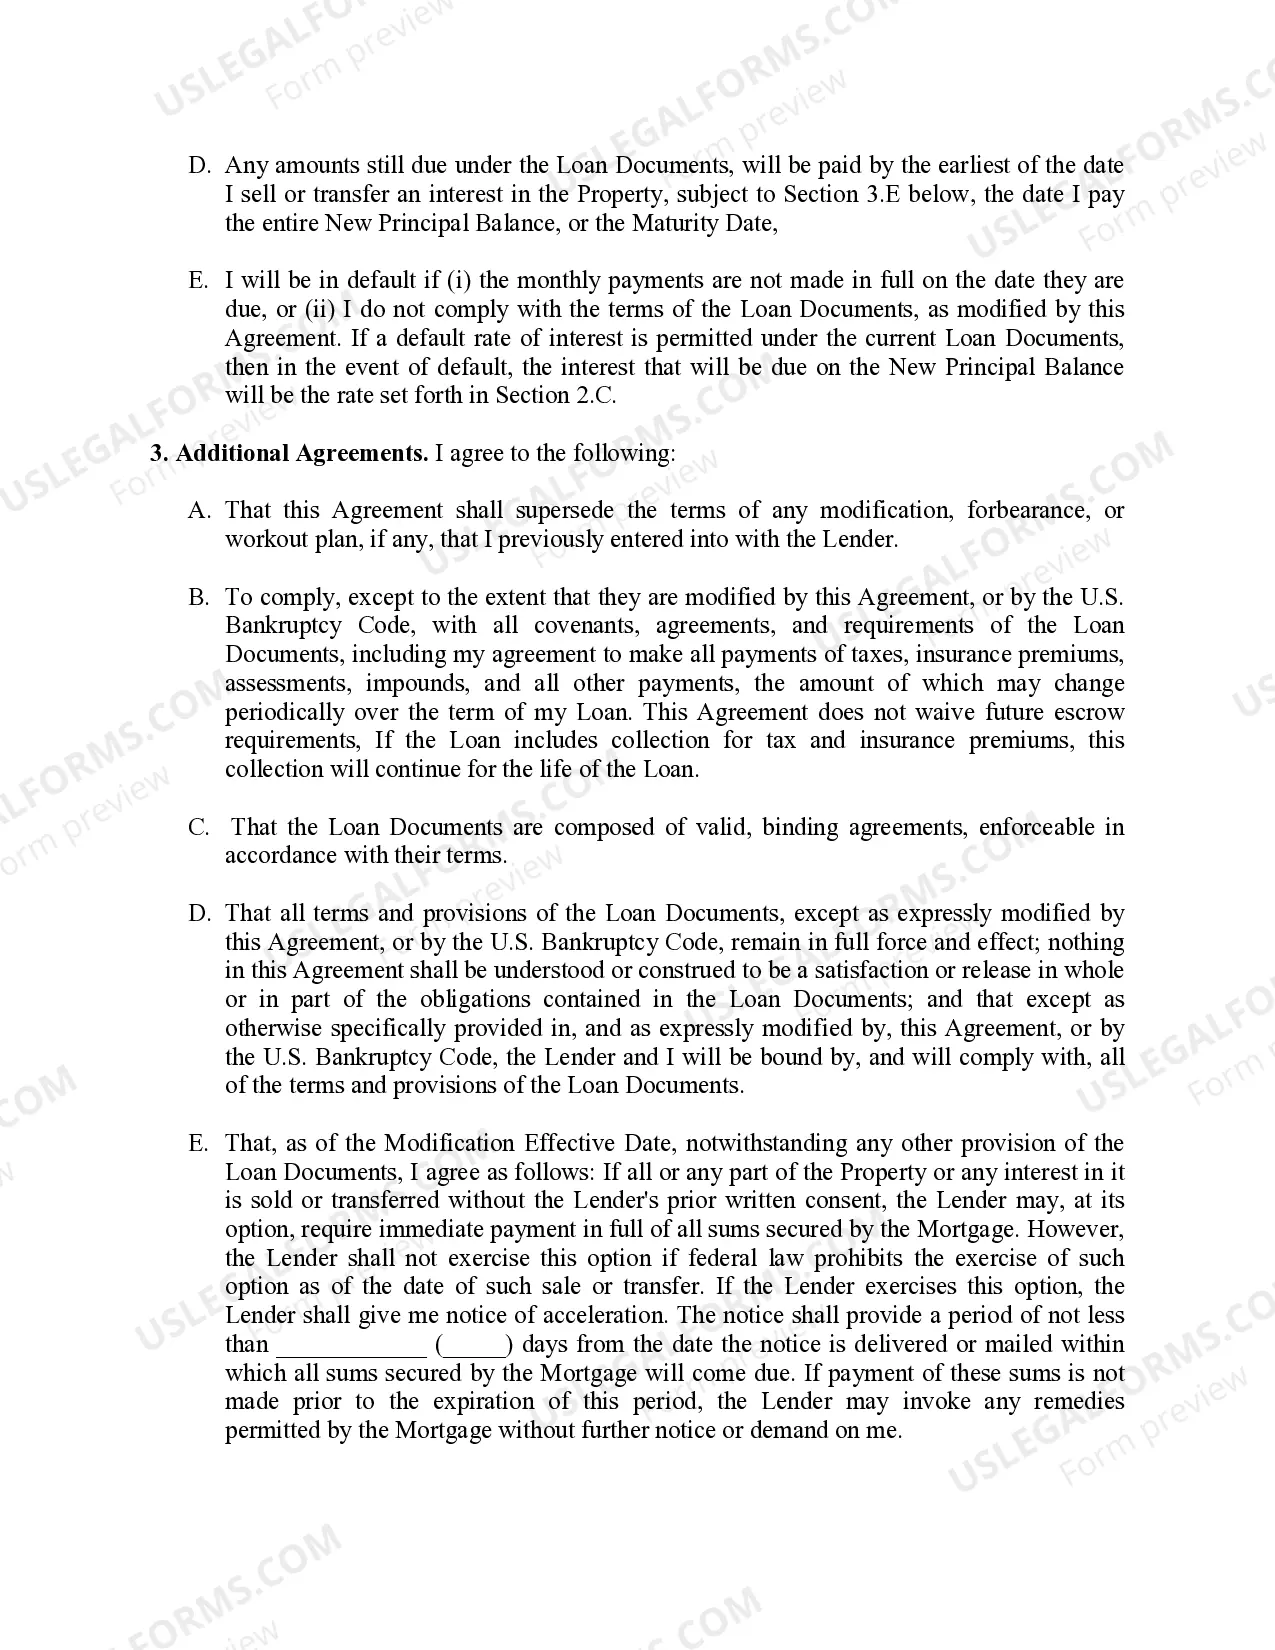
- Modification terms: New payment amount, interest rates, and payment schedule for the adjusted mortgage.
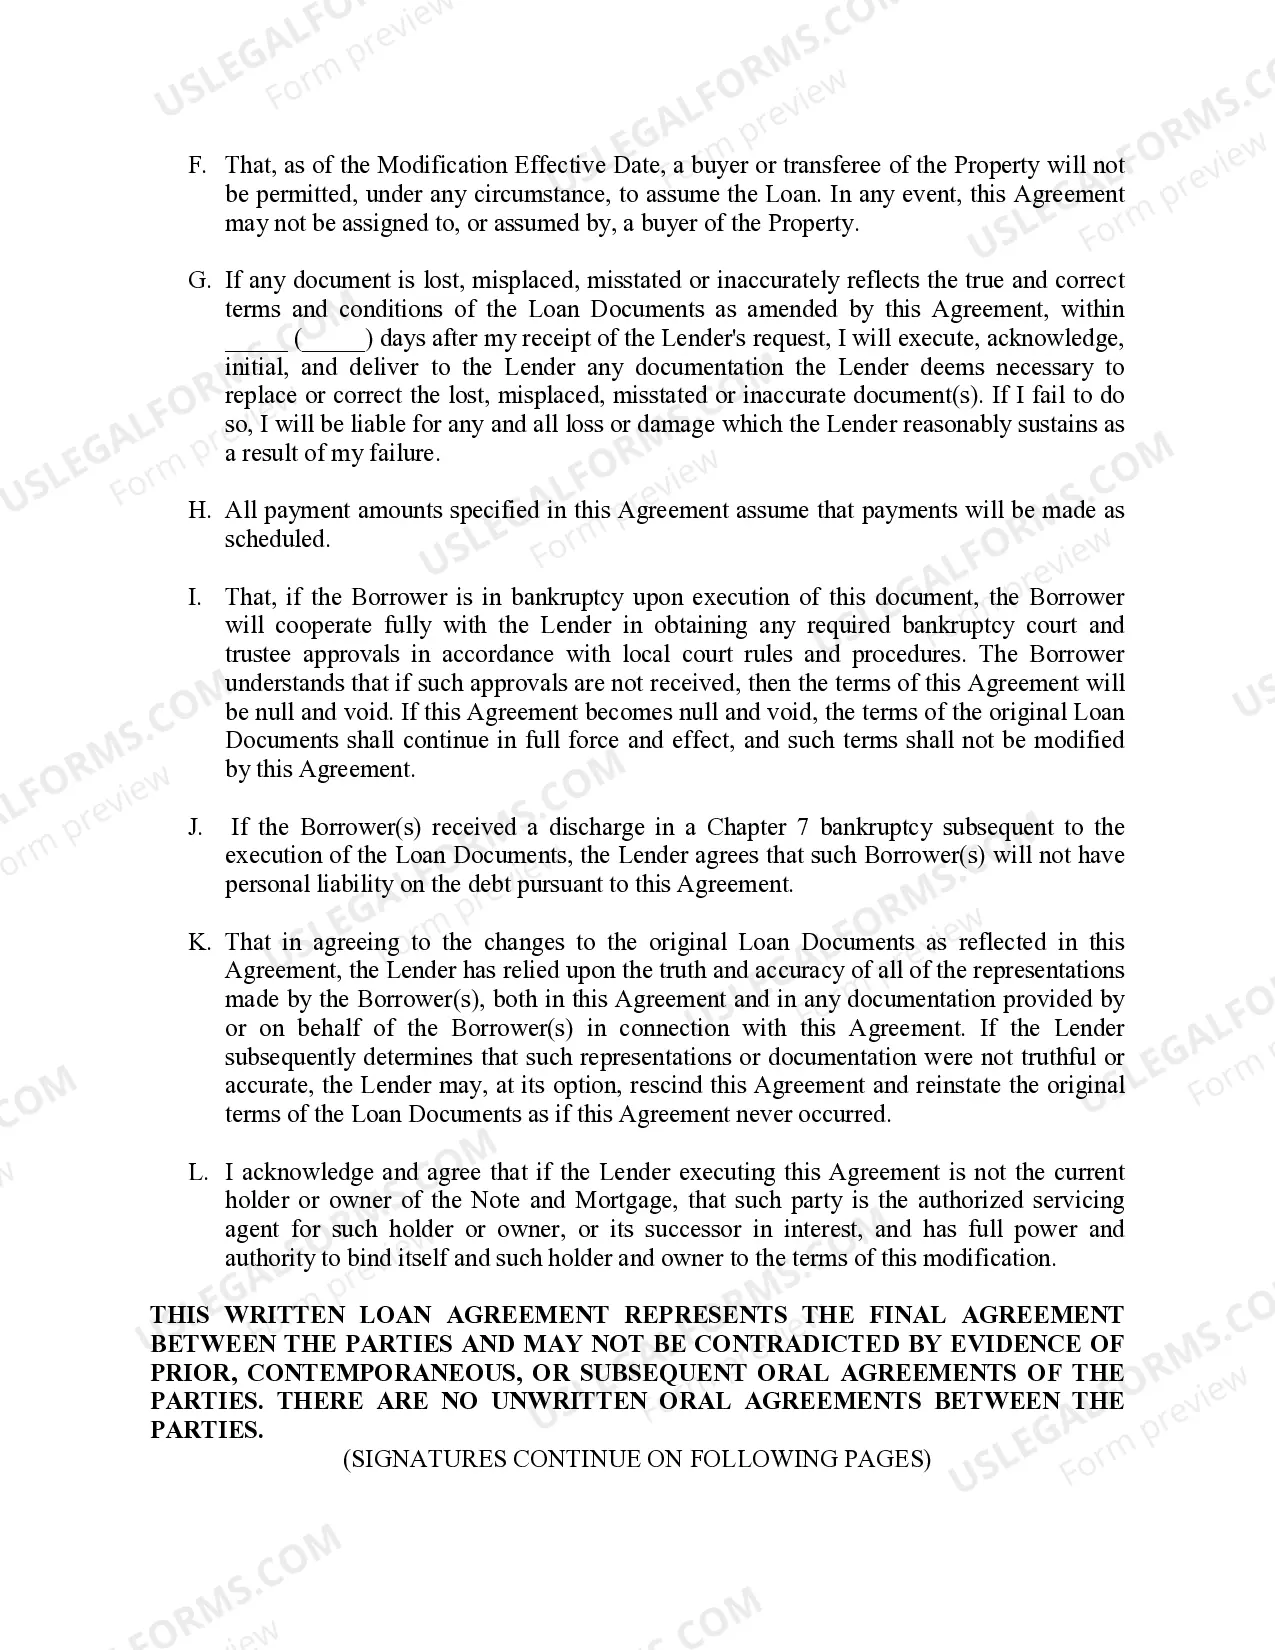
- Compliance agreement: A commitment to adhere to the modified terms of the mortgage and note.
Situations where this form applies
This form should be used when a borrower is facing financial difficulties that affect their ability to make mortgage payments. It is applicable in situations such as job loss, medical emergencies, or other financial hardships that make the current mortgage terms unmanageable. Utilizing this agreement can help prevent foreclosure and stabilize the borrower's financial situation through modified payment terms.
Intended users of this form
This form is intended for:
- Homeowners who are struggling to make their mortgage payments due to verified financial hardship.
- Borrowers who have received communication from their lender regarding potential mortgage modifications.
- Individuals who wish to renegotiate the terms of their existing mortgage to avoid foreclosure.
Steps to complete this form
- Identify the parties involved: Enter the names and addresses of both the borrower and lender.
- Specify loan details: Fill in the original loan number, property address, and legal description of the property.
- Declare financial hardship: Provide a statement outlining the reasons for the requested modification.
- Detail the modification: Clearly outline the new terms, including payment amounts and interest rates.
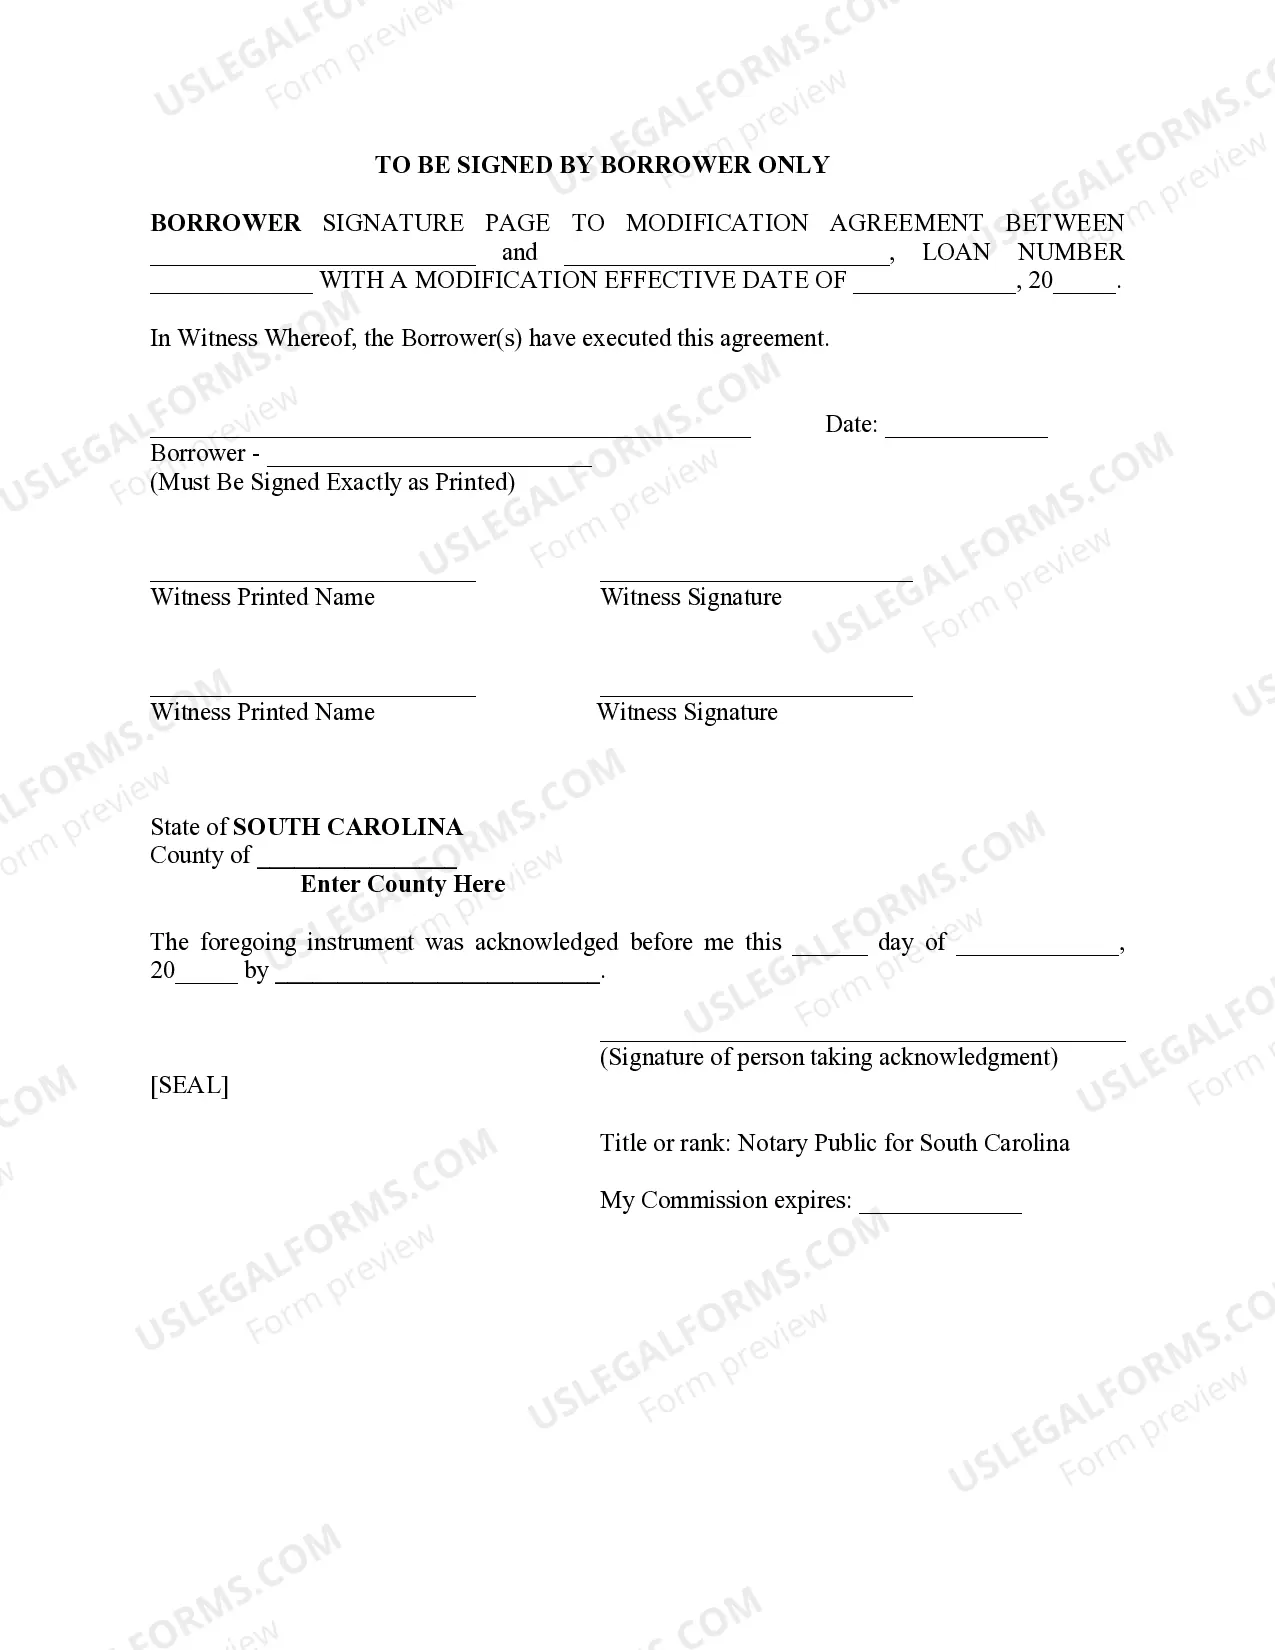
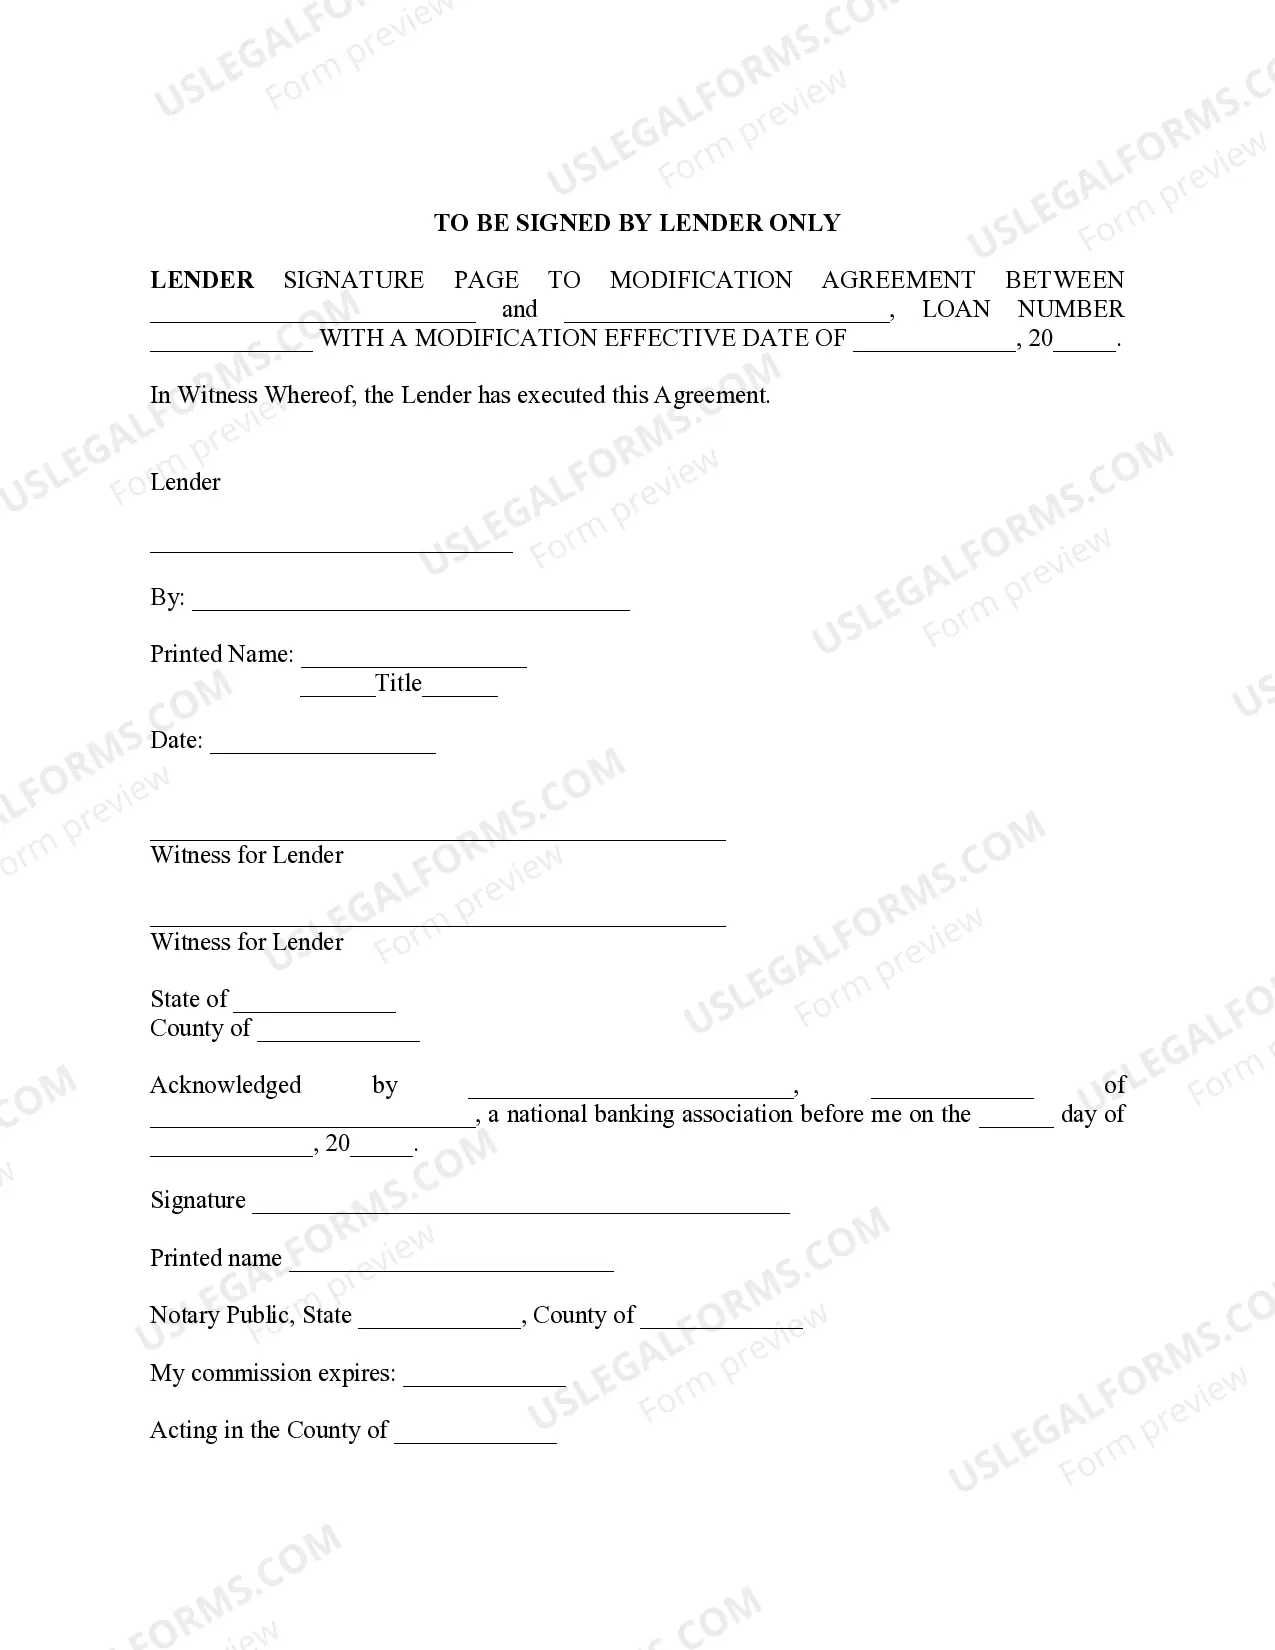
- Collect signatures: Ensure that both the borrower and lender sign and date the agreement, along with any witnesses or notaries if required.
Is notarization required?
This form does not typically require notarization unless specified by local law. Always check your stateâs regulations to confirm if notarization is necessary for your Loan Modification Agreement to be legally binding.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Common mistakes to avoid
- Failing to include accurate loan details.
- Not obtaining necessary signatures or witness confirmations.
- Omitting a clear declaration of financial hardship when required.
- Not reviewing state-specific guidelines for loan modifications.
Why use this form online
- Convenience: Access and download the form at any time from the comfort of your home.
- Editability: Easily input your specific details and adjustments to the agreement.
- Legal assurance: Receive templates drafted by licensed attorneys, ensuring the accuracy and validity of the document.
Looking for another form?

Form popularity
FAQ
Be at least one regular mortgage payment behind or show that missing a payment is imminent. Provide evidence of significant financial hardship, for reasons such as:
Yes, probably. In California, a law called the Homeowner Bill of Rights (HBOR) generally gives borrowers the right to appeal a modification denial. Under HBOR, in most cases, if the servicer denies a borrower's application to modify a first lien loan, the borrower can appeal.
You should contact the lender's loss and mitigation department to discuss the reason of you loan modification rejection. Possible reasons for a modification rejection include insufficient income, high debt-to-income ratio, missing documents, or delinquent credit history.
Some of the most common types of hardship are: job loss, pay reduction, underemployment, declining business revenue, death of a coborrower, illness, injury, and divorce.
A lender may agree to a loan modification during a settlement procedure or in the case of a potential foreclosure.A loan modification agreement is a long-term solution. A loan modification may involve a reduced interest rate, a longer period to repay, a different type of loan, or any combination of these.