North Carolina Additional Advance and Modification Agreement
What is this form?
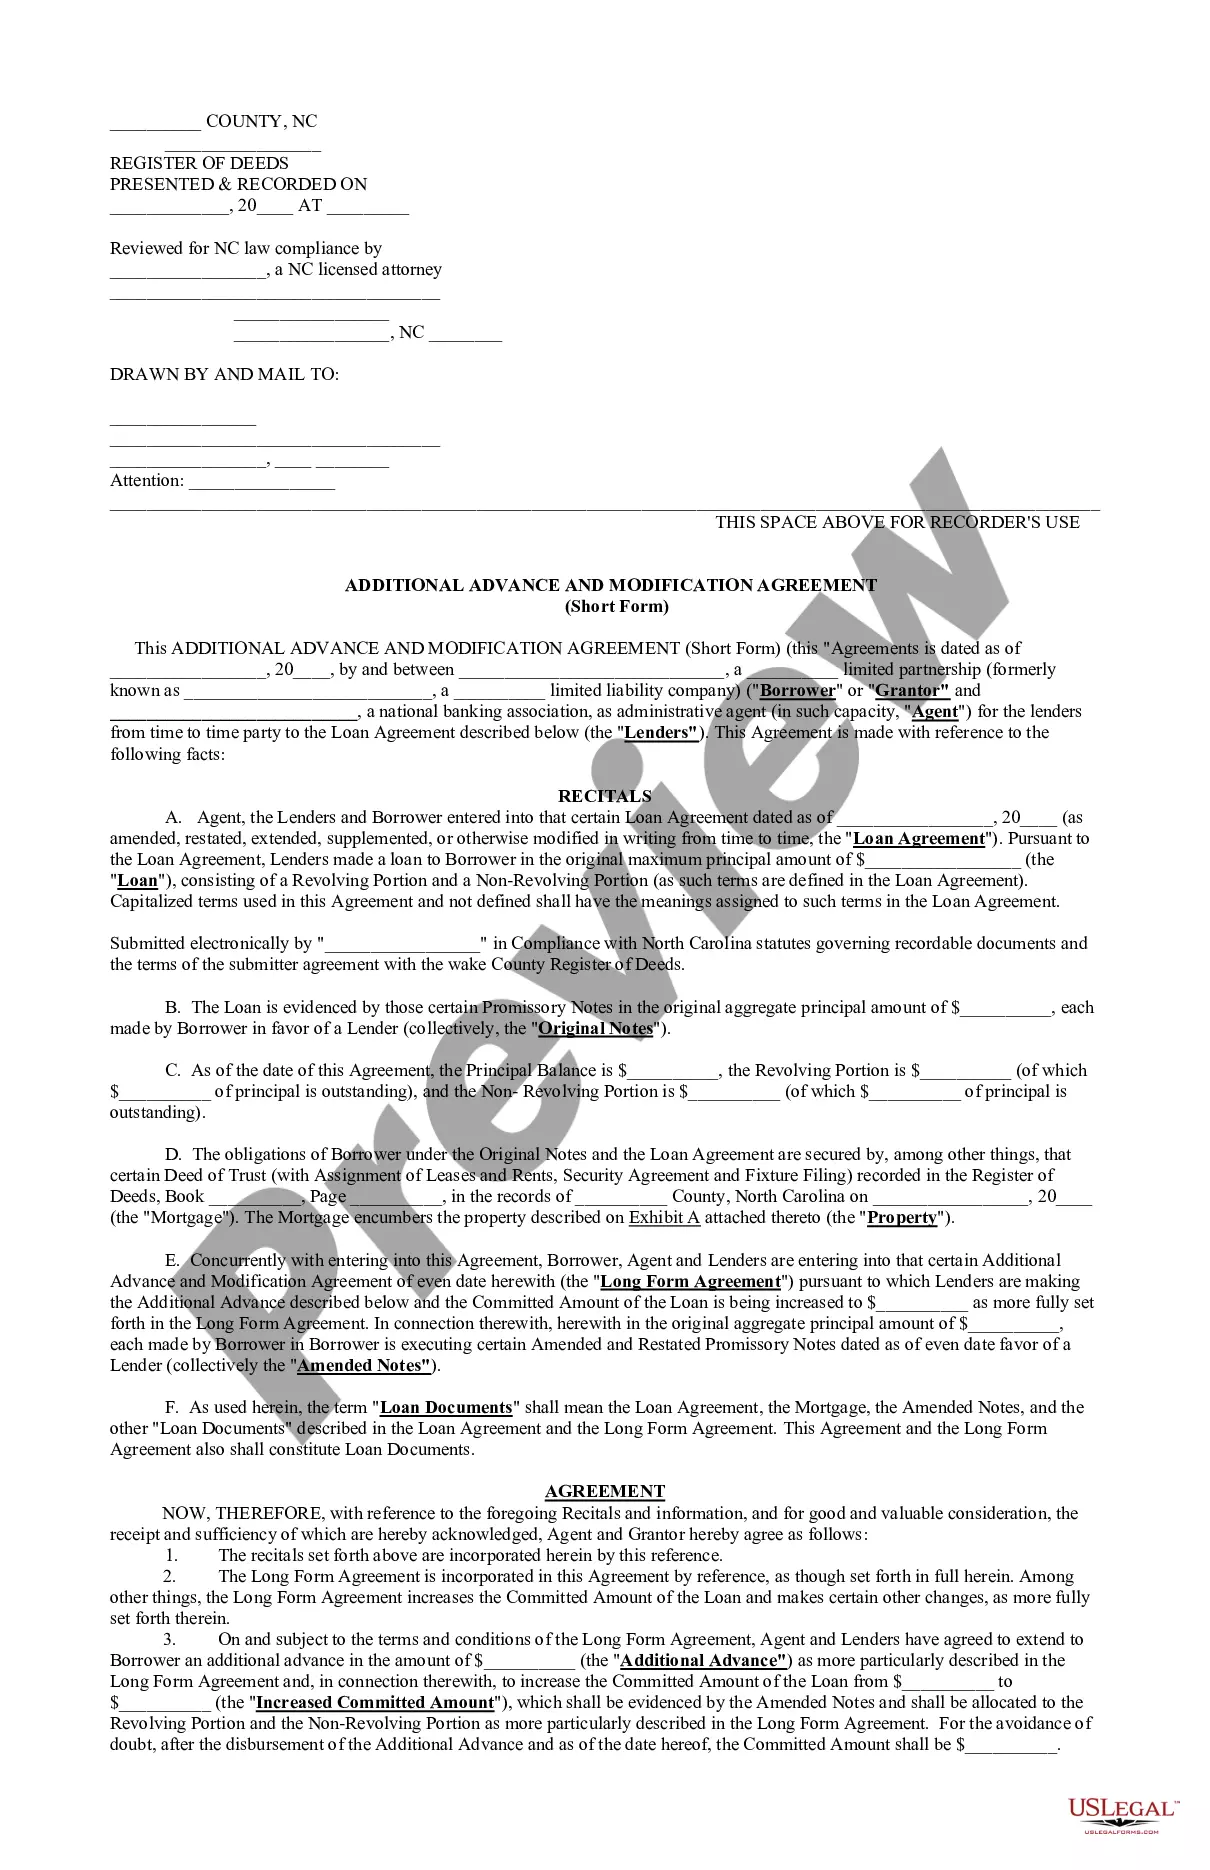
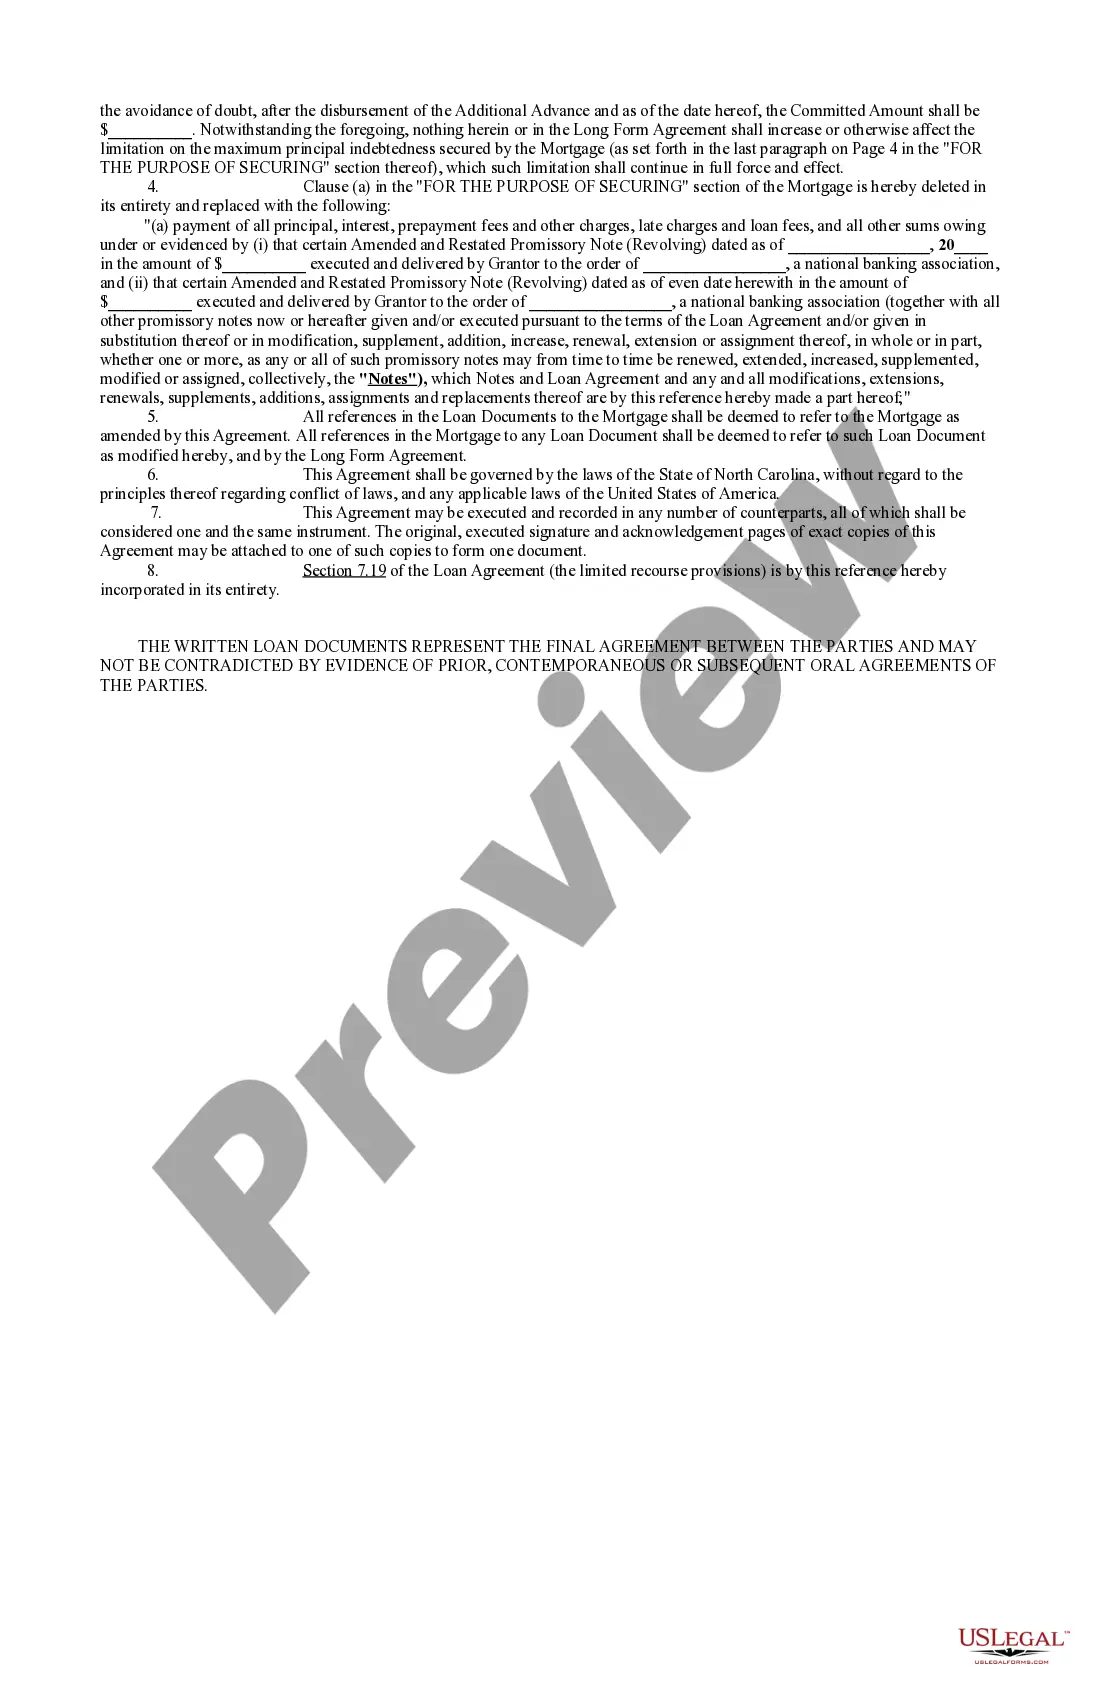
The Additional Advance and Modification Agreement is a legal document used to modify the terms of a loan between a borrower and lenders. This agreement allows for full or partial advances on the loan amount, facilitating adjustments to the original loan structure. It differs from other loan modification forms as it specifically focuses on allowing additional advances while detailing the revised loan terms.
What’s included in this form
- Borrower and Lender Details: Information on the borrower and lending institutions involved in the agreement.
- Loan Agreement Reference: A clause detailing reference to the original loan agreement and any previous amendments.
- Principal Balance and Loan Portions: Sections specifying the current principal balance, revolving, and non-revolving portions of the loan.
- Additional Advances: Declares the amount of additional loan advances and modifies the committed amount.
- Governing Law: Stipulates that the agreement is governed by the laws of North Carolina.
When to use this document
This form should be used when a borrower needs to modify existing loan terms and require additional financing. Common scenarios include expanding business operations, consolidating debt, or securing funds for unforeseen expenses. It is also applicable when both parties agree to re-structure the loan terms and conditions.
Who this form is for
- Borrowers seeking to modify their existing loan agreements.
- Lending institutions requiring a formal record of loan modifications.
- Businesses or individuals entering into loan agreements that need additional funds.
- Attorneys assisting clients with loan modifications and related documentation.
Completing this form step by step
- Identify the Parties: Fill in the names of the borrower and the lending institutions.
- Specify Loan Details: Enter the original loan amount, current balance, and new advance amounts.
- Reference Existing Loan Agreements: Include details from prior agreements as necessary.
- Date the Agreement: Make sure to provide the correct execution date.
- Sign and Notarize: Ensure that all parties sign the agreement and have it notarized if required.
Notarization requirements for this form
Yes, this form must be notarized to be legally valid. US Legal Forms offers integrated online notarization services available 24/7, allowing you to have the document verified through a secure video call, ensuring legality without needing to travel.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Avoid these common issues
- Failing to include all necessary parties in the agreement.
- Not updating references to prior loan documents accurately.
- Omitting signature lines or failing to notarize when required.
- Incorrectly calculating the principal balance or additional advances.
Benefits of using this form online
- Convenience: Download and complete the form at your own pace without professional assistance.
- Editability: Tailor the document to fit your specific loan modification needs.
- Reliability: Access professionally drafted legal documents ensuring compliance with current laws.
Looking for another form?
Form popularity
FAQ
Yes, probably. In California, a law called the Homeowner Bill of Rights (HBOR) generally gives borrowers the right to appeal a modification denial. Under HBOR, in most cases, if the servicer denies a borrower's application to modify a first lien loan, the borrower can appeal.
You should contact the lender's loss and mitigation department to discuss the reason of you loan modification rejection. Possible reasons for a modification rejection include insufficient income, high debt-to-income ratio, missing documents, or delinquent credit history.
A loan modification is a change that the lender makes to the original terms of your mortgage, typically due to financial hardship. The goal is to reduce your monthly payment to an amount that you can afford, which you can achieve in a variety of ways.
The most common examples of hardship include: Illness or injury. Change of employment status. Loss of income.
Be at least one regular mortgage payment behind or show that missing a payment is imminent. Provide evidence of significant financial hardship, for reasons such as:
Suspend past due amounts. Bring your account current. Adjust your interest rate. Lower your minimum payments. Modify your loan. Agree to a short sale of a home. Consider a settlement option.
Yes, it is possible to get a second loan modification though statistically it's obvious that you are less likely to get a second modification if you've had a first, and a third if you were lucky enough to get a second. It is possible though.
Some of the most common types of hardship are: job loss, pay reduction, underemployment, declining business revenue, death of a coborrower, illness, injury, and divorce.