Illinois Modification of Mortgage Loan in Default to Bring it Current and to Change Variable Rate of Interest to Fixed Rate
About this form
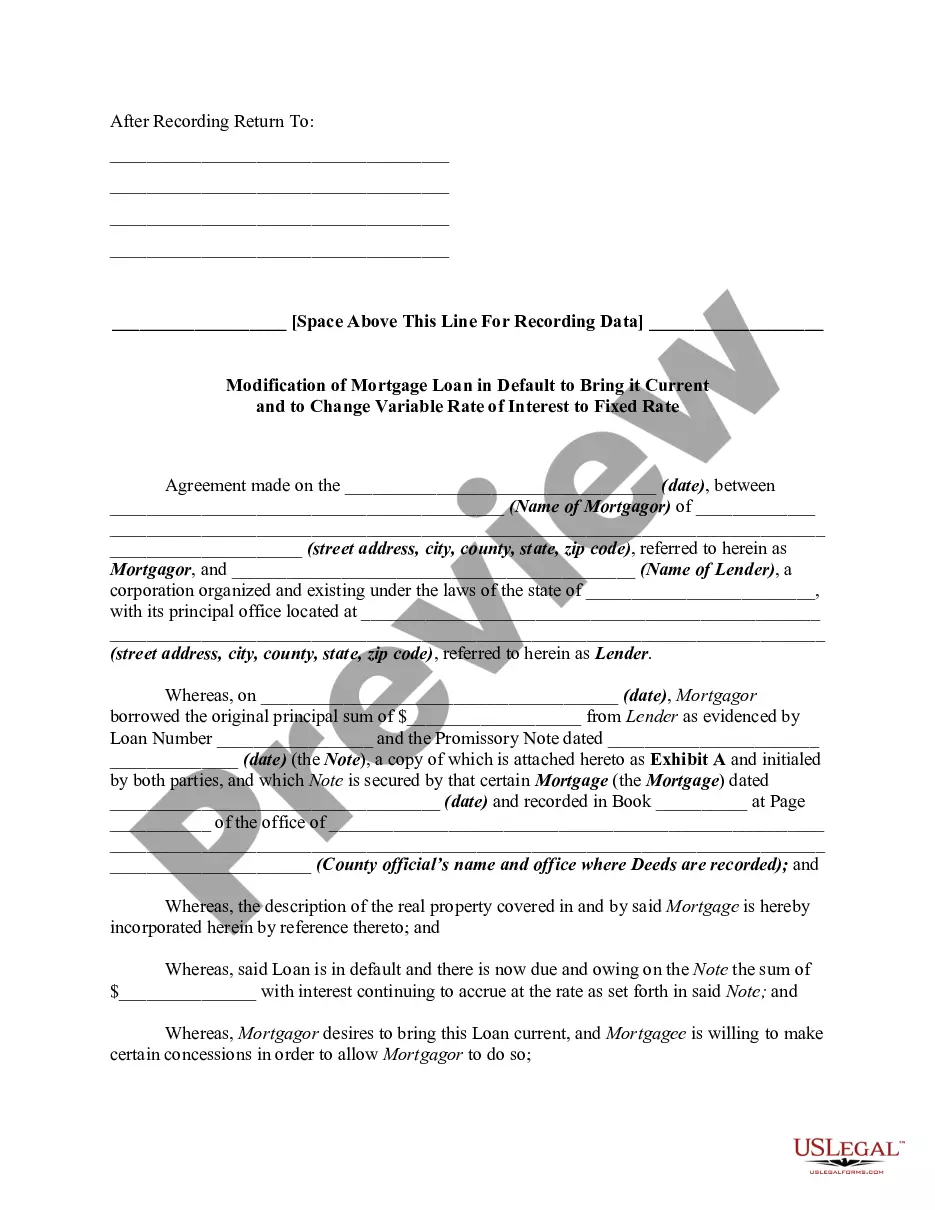
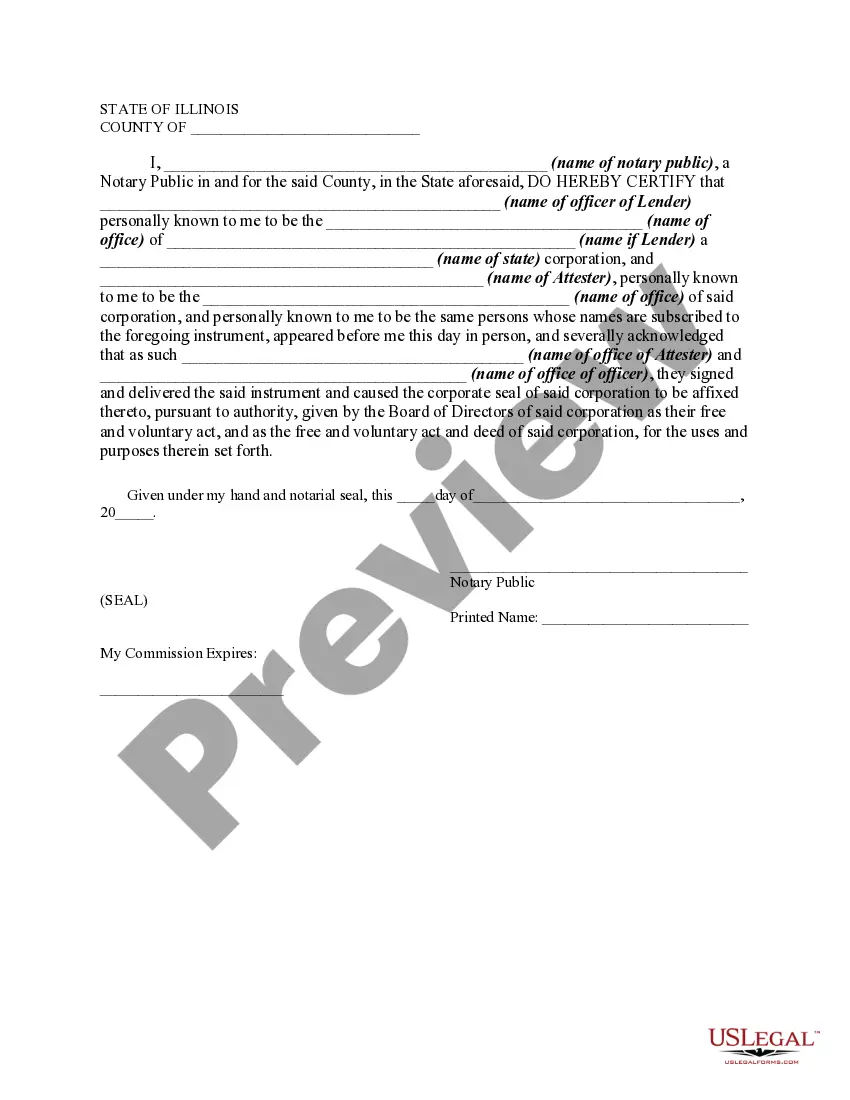
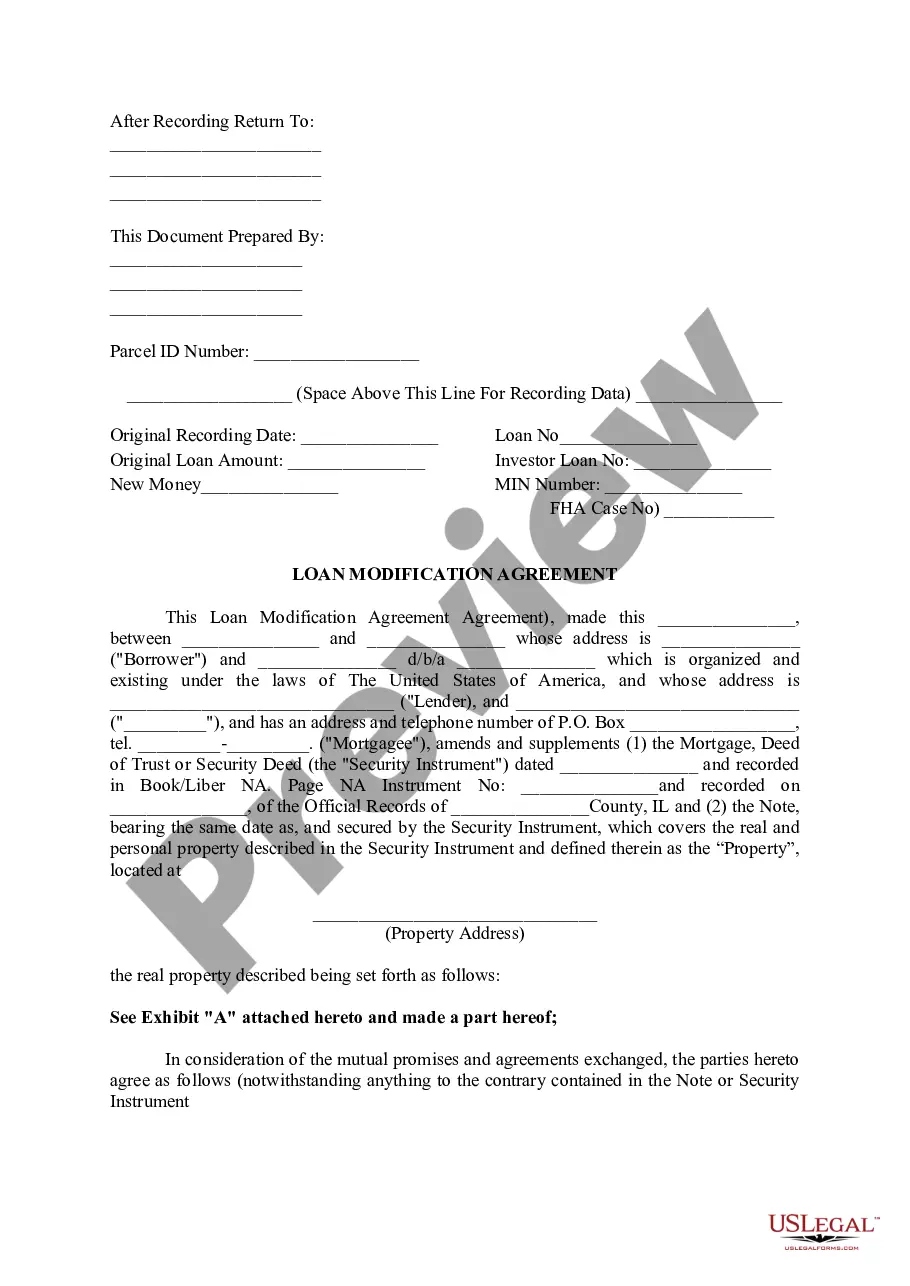
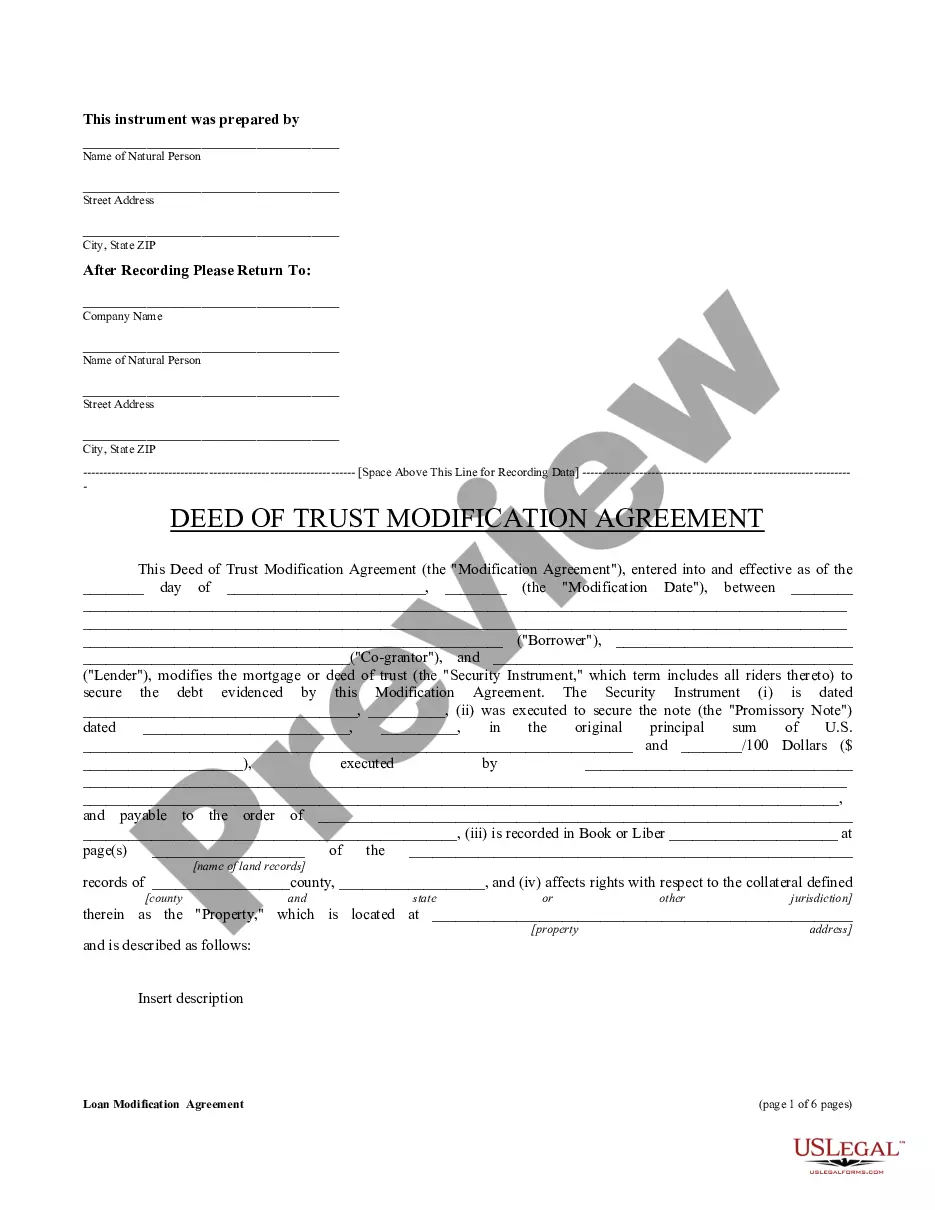
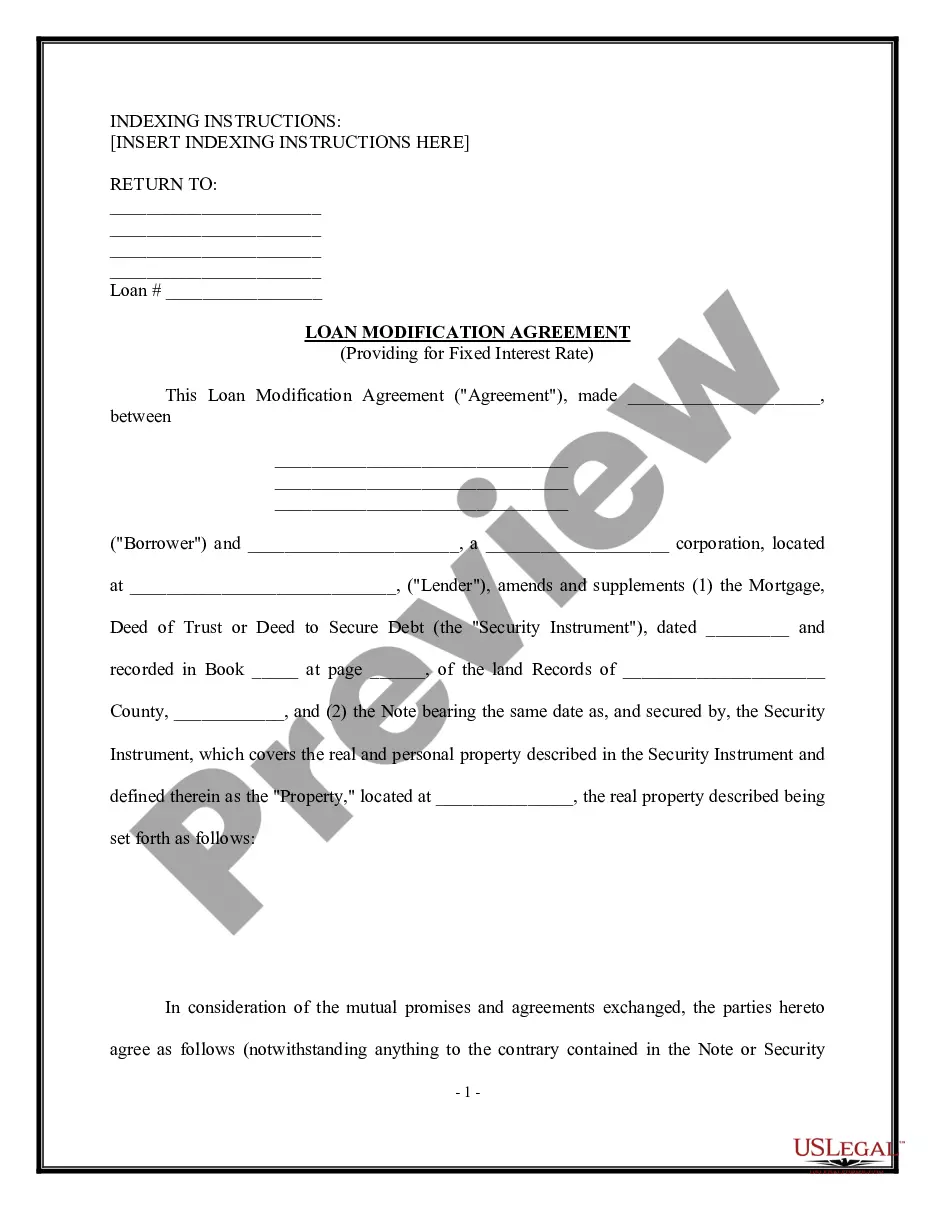
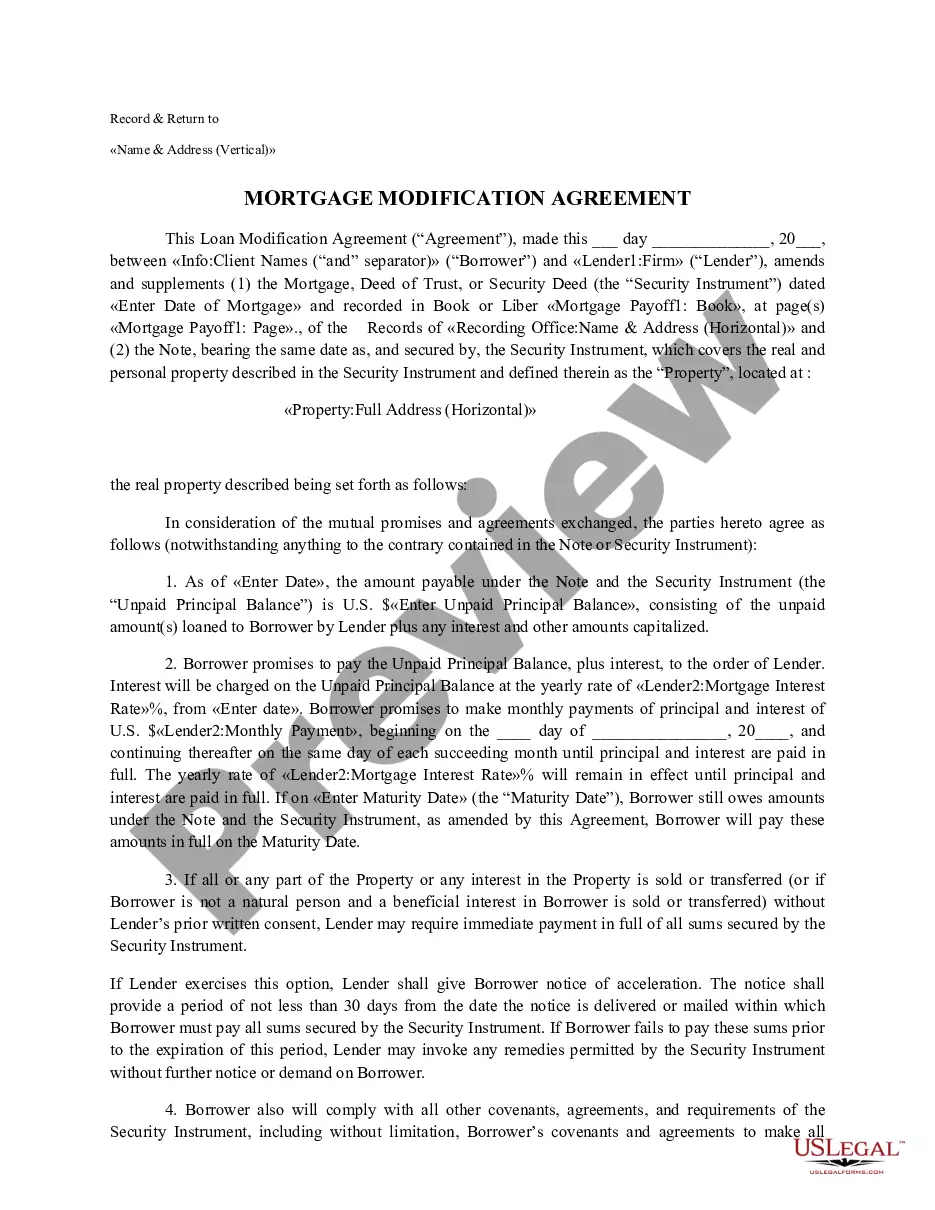
This form, known as a Modification of Mortgage Loan in Default to Bring it Current and to Change Variable Rate of Interest to Fixed Rate, is a legal document used to amend the terms of a mortgage loan that is currently in default. This form allows the mortgagor to update the loan conditions by bringing it current and changing the interest rate from a variable to a fixed rate. It is important to note that this modification is a contractual agreement that must be signed by both the lender and the mortgagor, and it should be recorded in the appropriate register of deeds and mortgages office.
Key components of this form
- Identification of the parties involved: Mortgagor and Lender.
- Original loan details, including the date and amount borrowed.
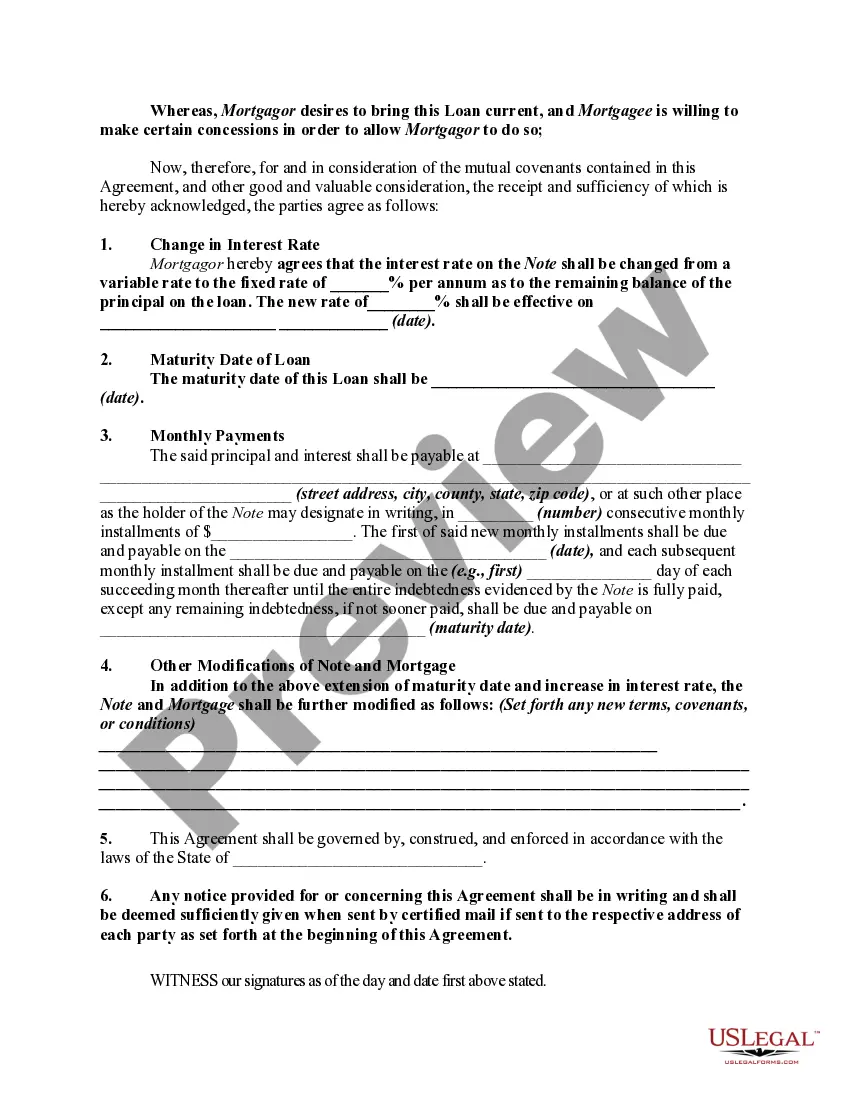
- New terms such as the fixed interest rate and updated maturity date.
- Specifications for monthly payment amounts and due dates.
- Additional modifications to the original mortgage agreement.
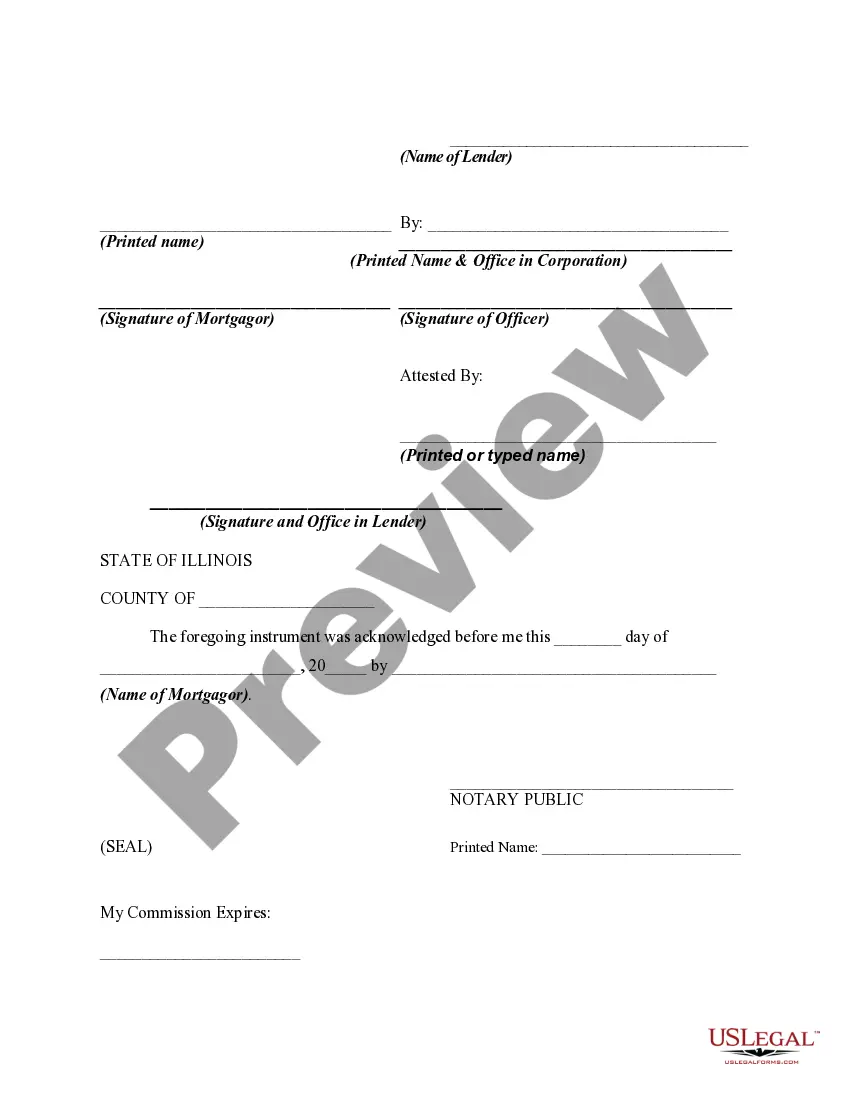
- Signatures of both parties and notarization requirements.
Common use cases
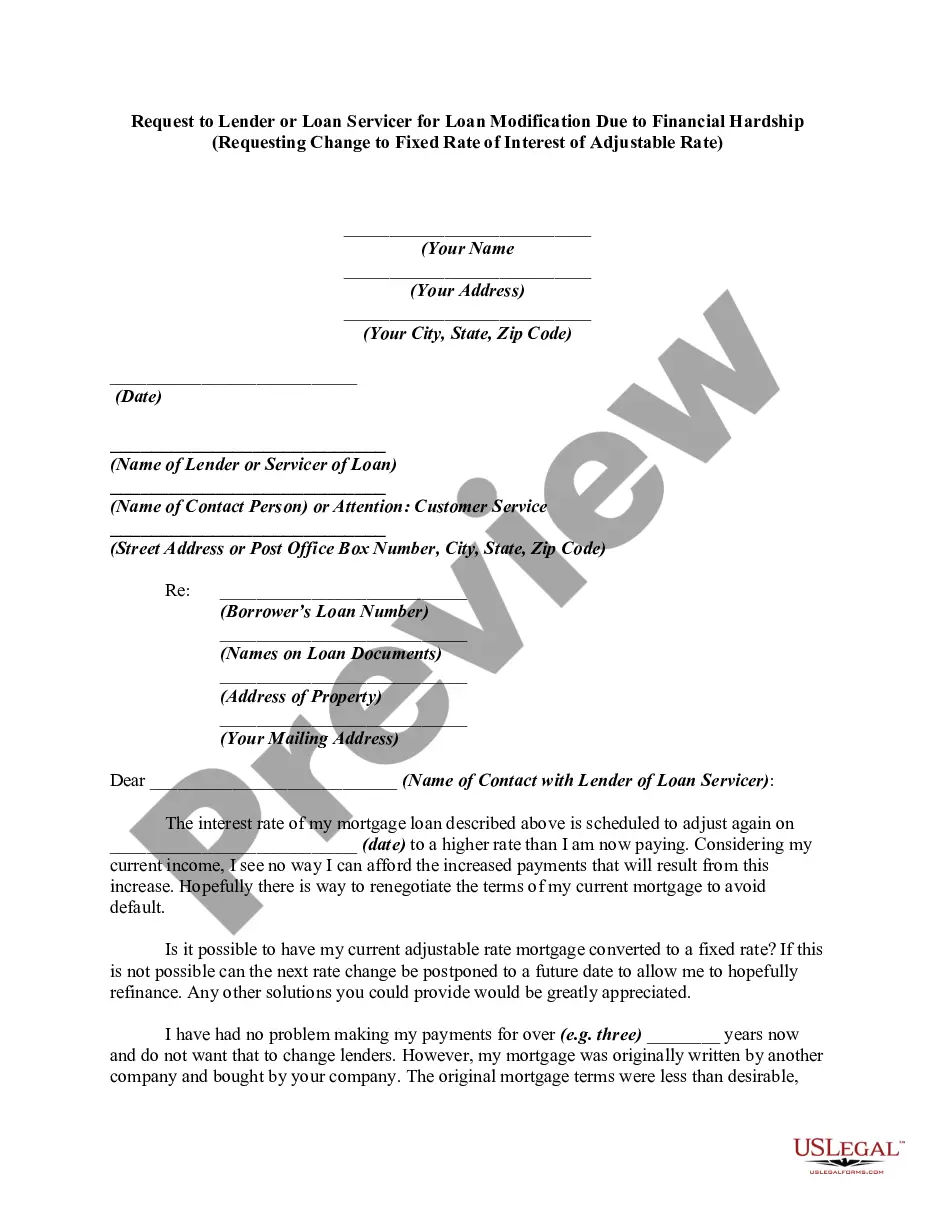
This form should be utilized in situations where a mortgage loan has fallen into default, and the mortgagor wishes to make arrangements to bring the loan current. It is suitable for borrowers who want to stabilize their loan by converting an adjustable interest rate to a fixed interest rate, making their payments more predictable. This can help borrowers better manage their financial responsibilities and avoid potential foreclosure.
Who this form is for
This form is intended for:
- Homeowners who are experiencing financial difficulties and have defaulted on their mortgage payments.
- Lenders who are willing to offer modifications to help borrowers retain their properties.
- Individuals seeking to formalize agreed changes to their existing mortgage agreements.
How to prepare this document
- Identify the parties involved by filling in the names and addresses of both the mortgagor and lender.
- Specify the date of the original loan, along with the loan amount and loan number.
- Complete the sections detailing the new fixed interest rate and the updated maturity date.
- Outline the new payment schedule, including the amount and due dates for monthly installments.
- Ensure that both parties sign the document and have it notarized to validate the agreement.
Does this form need to be notarized?
This form needs to be notarized to ensure legal validity. US Legal Forms provides secure online notarization powered by Notarize, allowing you to complete the process through a verified video call, available anytime.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
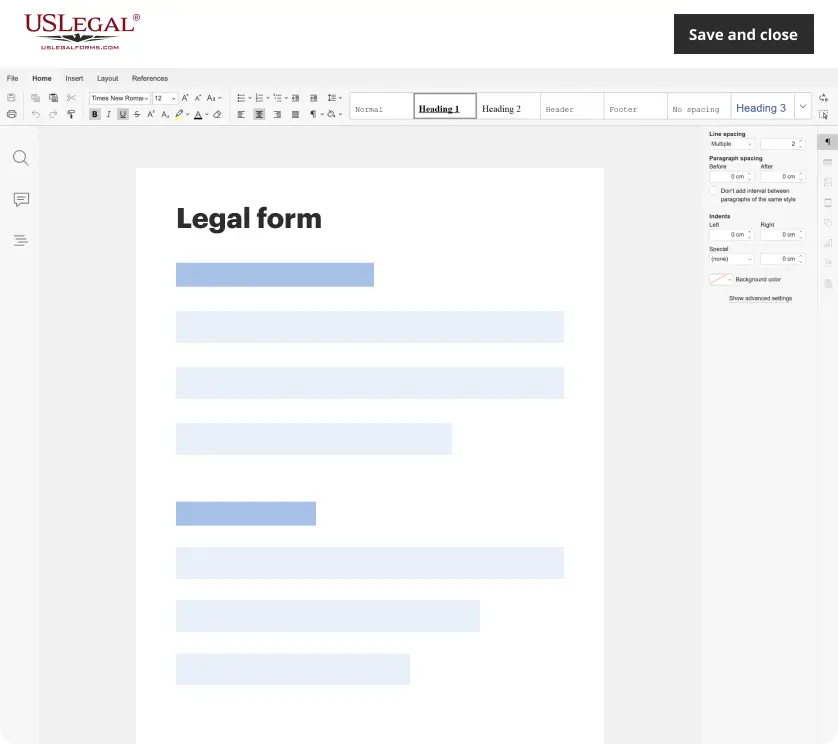
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Typical mistakes to avoid
- Failing to fill in all required fields accurately, particularly financial details.
- Not obtaining proper notarization, which can invalidate the modification.
- Overlooking to record the modification in the appropriate deeds office.
- Not having all parties review and agree to the terms of modification before signing.
Benefits of completing this form online
- Convenient access to a standardized modification document that can be completed at any time.
- Editable format that allows users to customize the document according to their specific needs.
- Reliable legal protections due to templates drafted by licensed attorneys.
Legal use & context
- Modification agreements are legally binding contracts that can help prevent foreclosure or further financial complications.
- Parties should ensure that the modification is within the legal frameworks applicable in their state or jurisdiction.
- Clearly defined terms in the modification ensure enforceability in case of disputes in the future.
What to keep in mind
- This form is essential for those looking to modify a default mortgage loan's terms.
- Notarization and proper recording of the modification are crucial for legality.
- Both parties must agree to the new terms for the modification to be enforceable.
Looking for another form?

Form popularity
FAQ
If your modification is temporary, you'll likely need to return to the original terms of your mortgage and repay the amount that was deferred before you can qualify for a new purchase or refinance loan.
Homeowners go through the process of a loan modification to stay afloat in times that their mortgage payments are becoming too difficult to maintain. It is possible to refinance the loan again in the future, but do not expect it to come without challenges.
You can refinance a modified home loan depending on your current financial conditions, the terms of the modification and how much time passed since completing the modification. Typically, lenders don't approve modifications unless you stand a better chance of repaying the debt under new modified terms.
Homeowners go through the process of a loan modification to stay afloat in times that their mortgage payments are becoming too difficult to maintain. It is possible to refinance the loan again in the future, but do not expect it to come without challenges.
You can get a mortgage after you have done a loan modification. Loan modifications were quite popular starting in 2009 through 2013.If you went ahead a only lowered the interest rate or converted it to a fixed rate, than you should be able to qualify for a new mortgage right away, no waiting period.
There is a 12-24 month waiting period before you can refinance under most post-loan modification options. To refinance a loan's interest rate and repayment terms, the refinance lender requires you to have stable income and total monthly expenses within 40 percent of your gross monthly income.
If a borrower defaults on a loan modification executed under HAMP (delinquent by the equivalent of three full monthly payments at the end of the month in which the last of the three delinquent payments was due), the loan is no longer considered to be in good standing. Once lost, good standing cannot be restored even
Either way, it stays on your report for seven years.
After your loan modification was completed. There are a couple of lenders that will allow anywhere from 1-2 yrs after a loan modification is completed. Barclay Butler Financial has no minimum time that has to have gone by since the loan modification was completed.