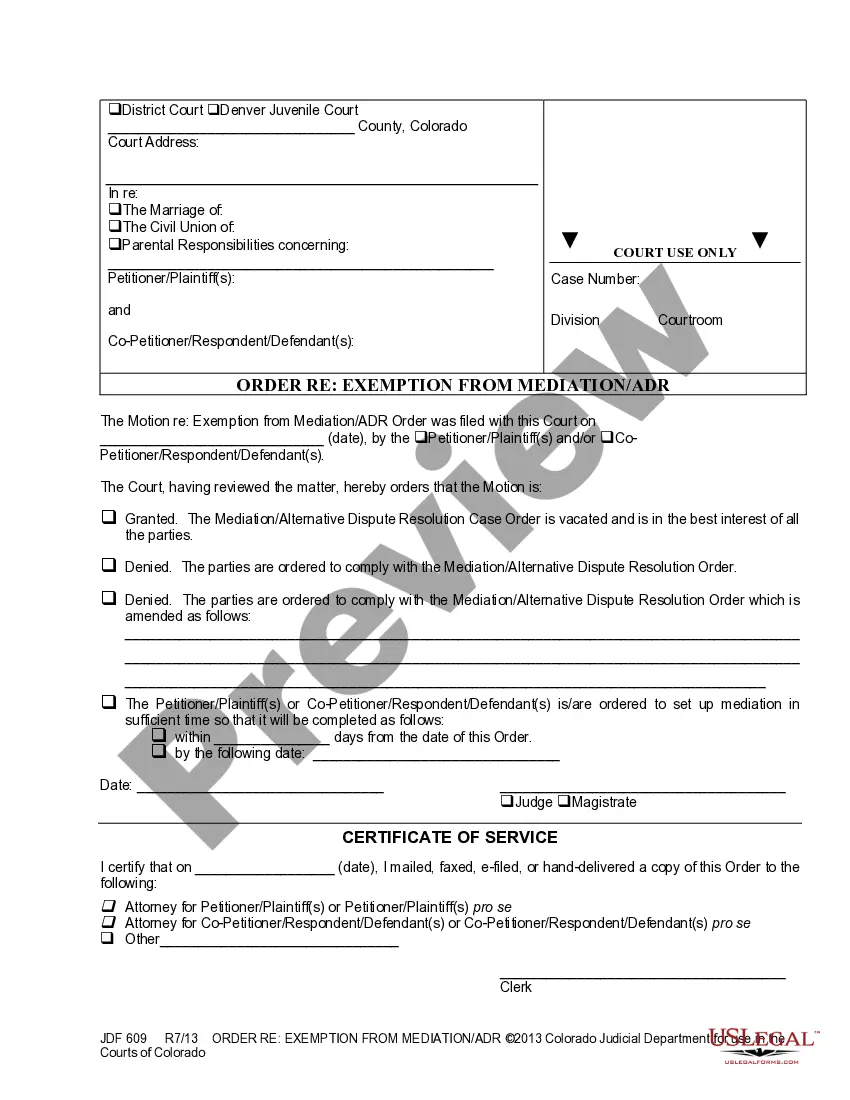
Alabama Deed In Lieu of Foreclosure
Understanding this form
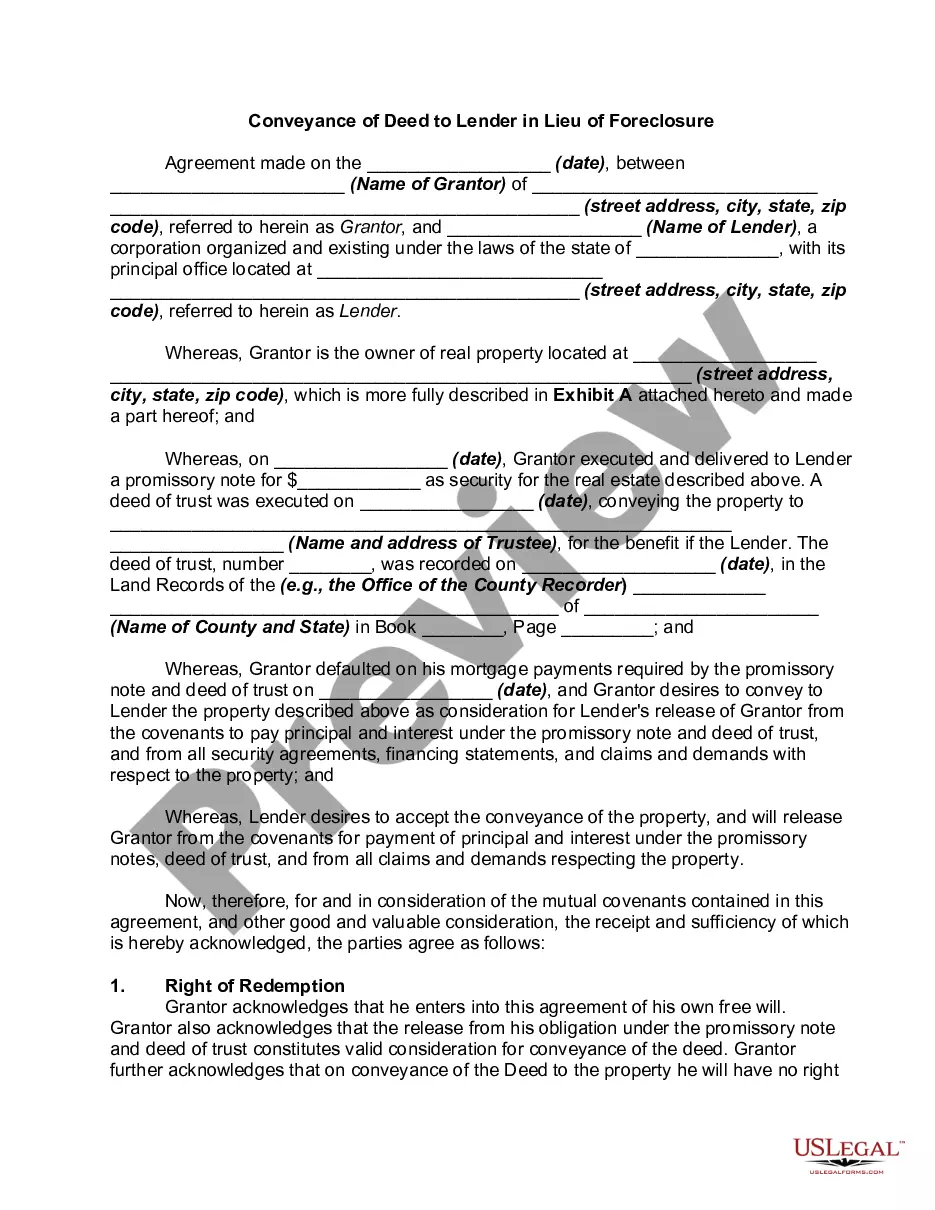
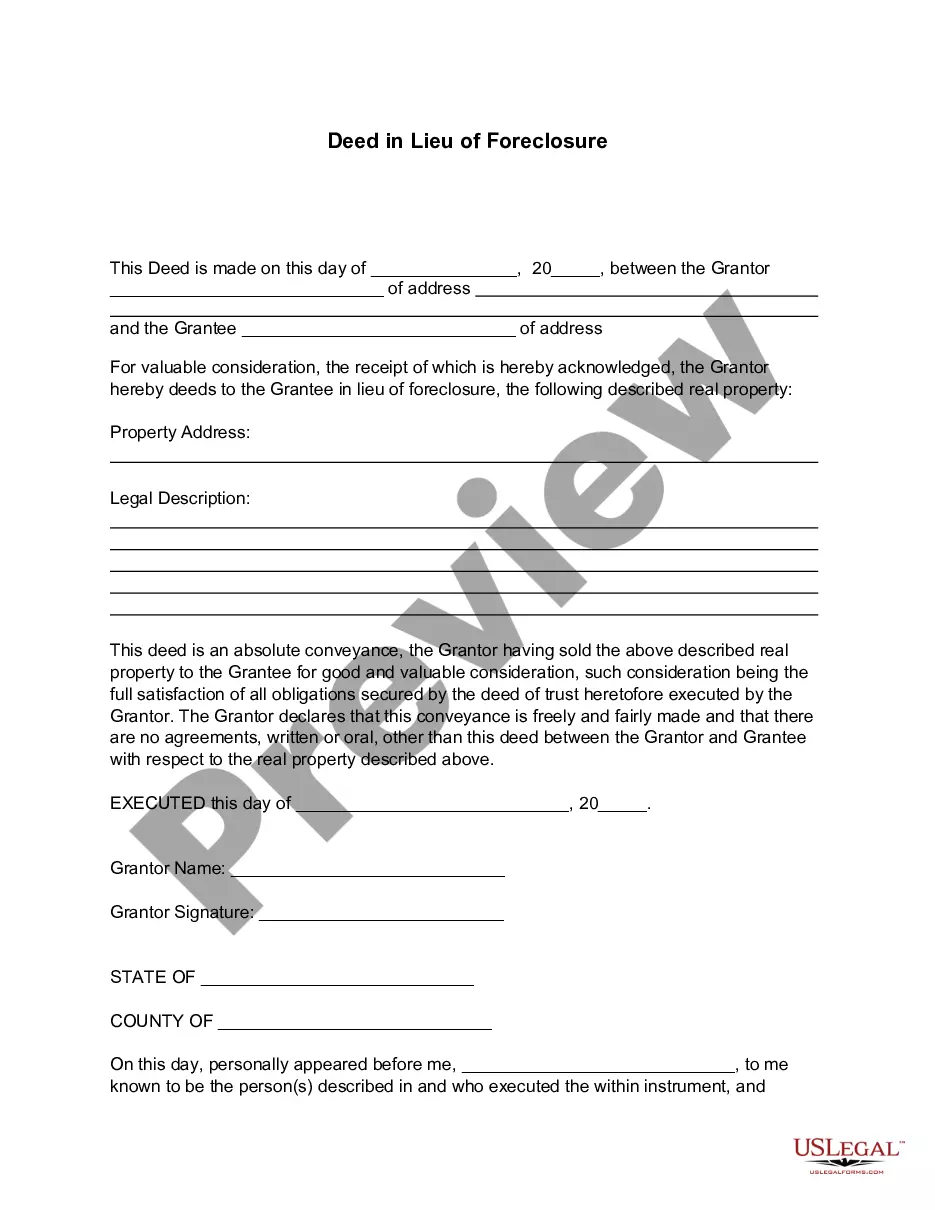
The deed in lieu of foreclosure is a legal document that allows a property owner to transfer ownership of their property back to the lender to avoid the foreclosure process. Instead of undergoing a lengthy and costly foreclosure, the property owner gives the deed directly to the lender as full repayment for the outstanding mortgage. This approach can simplify the process for both parties involved.
What’s included in this form
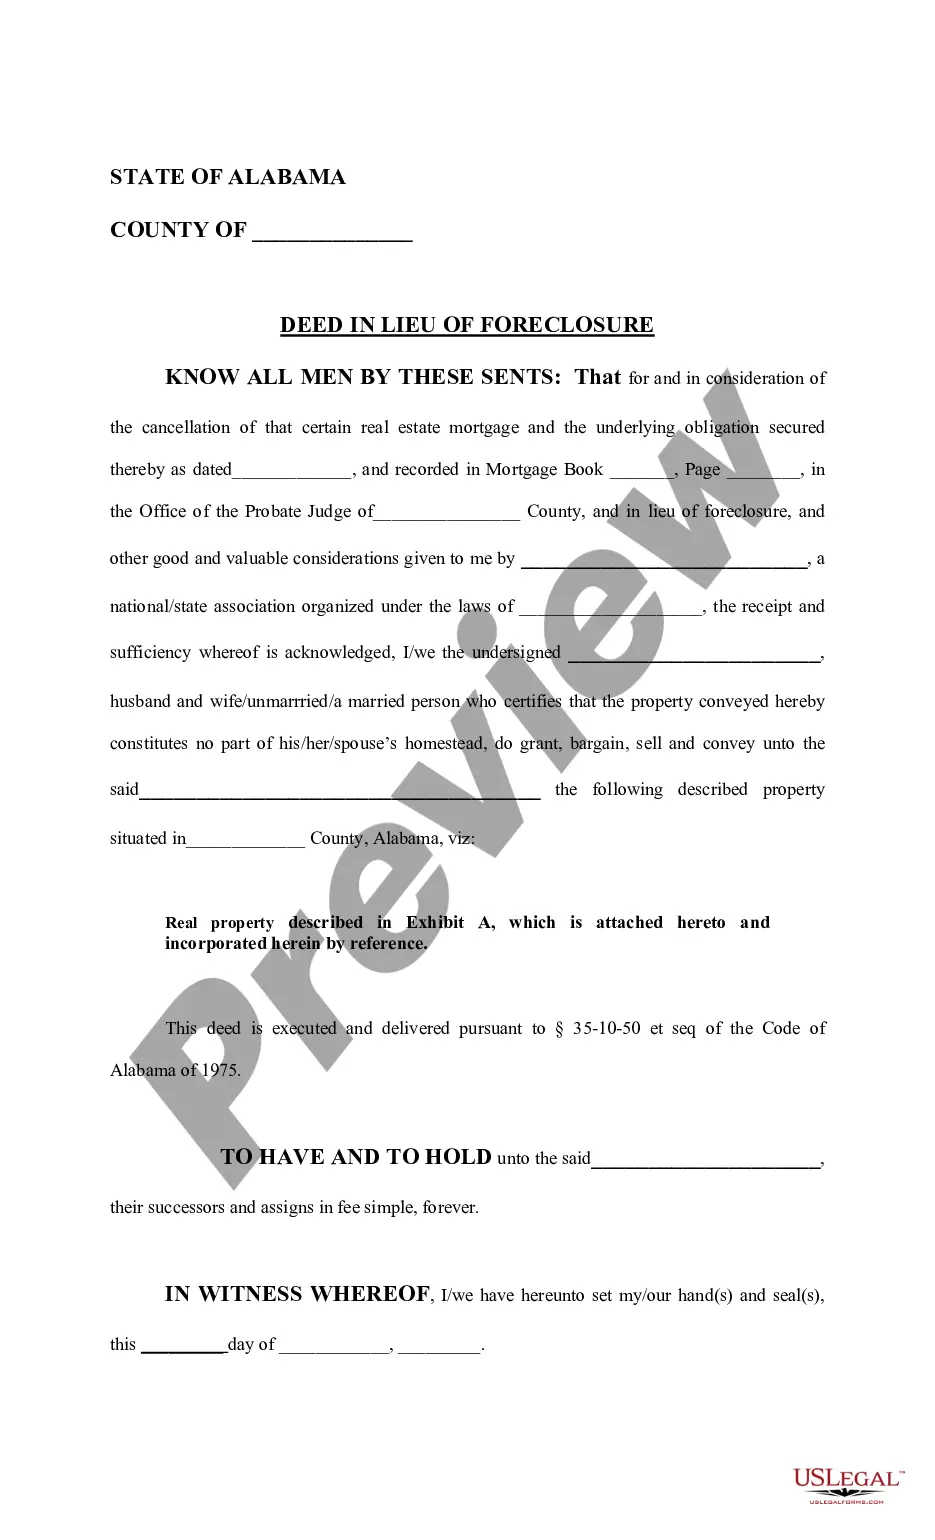
- Identification of the property owner and lender.
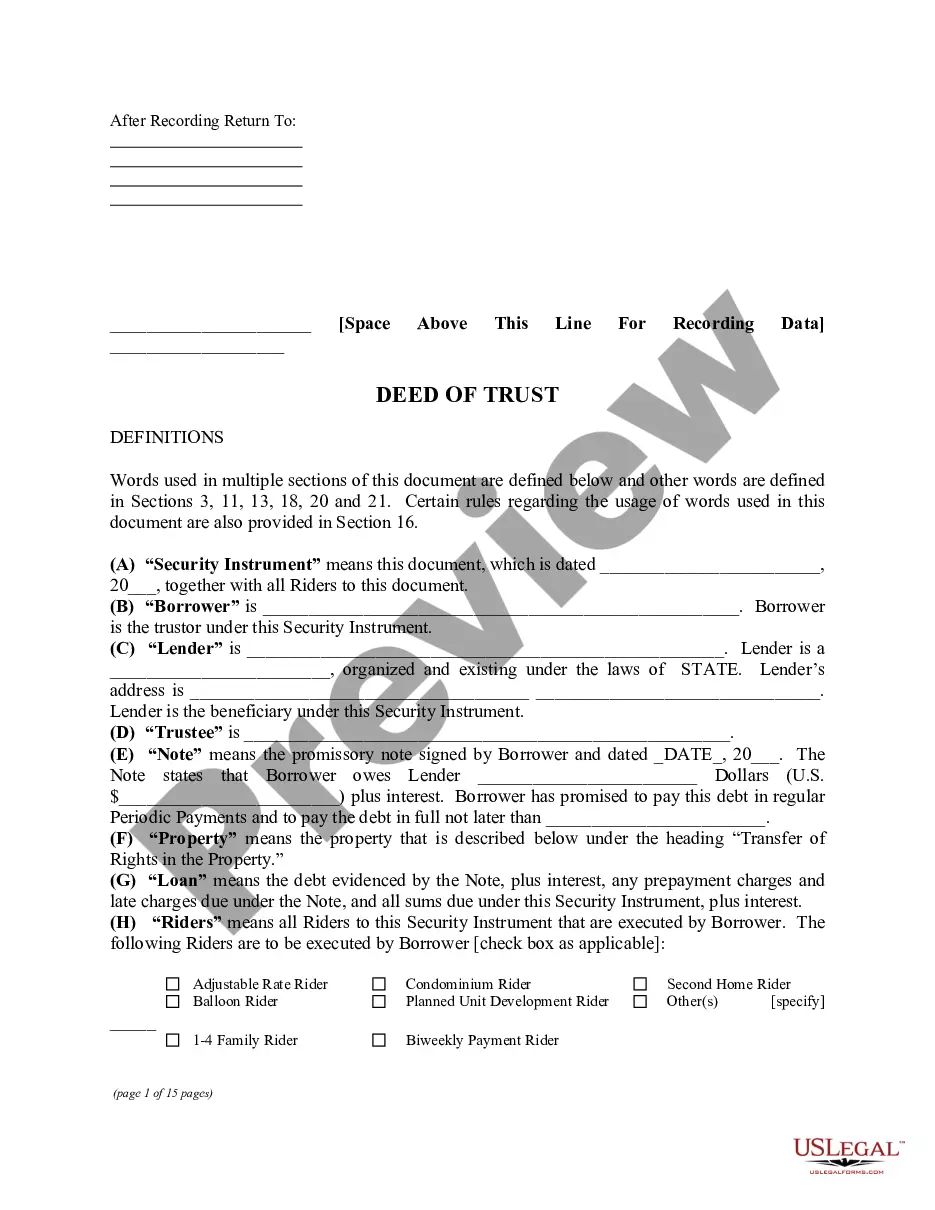
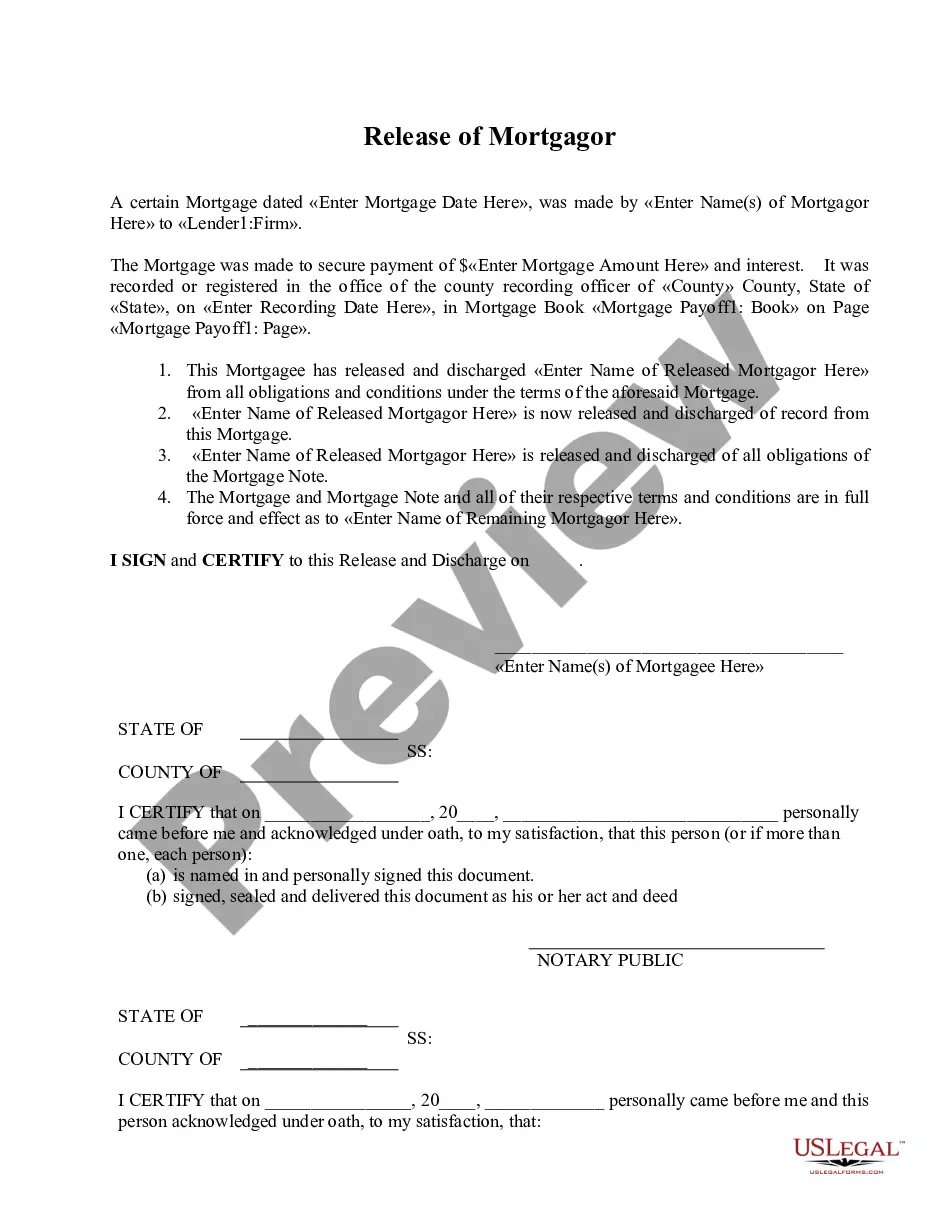
- Details of the real estate mortgage being canceled.
- Clear description of the property being transferred.
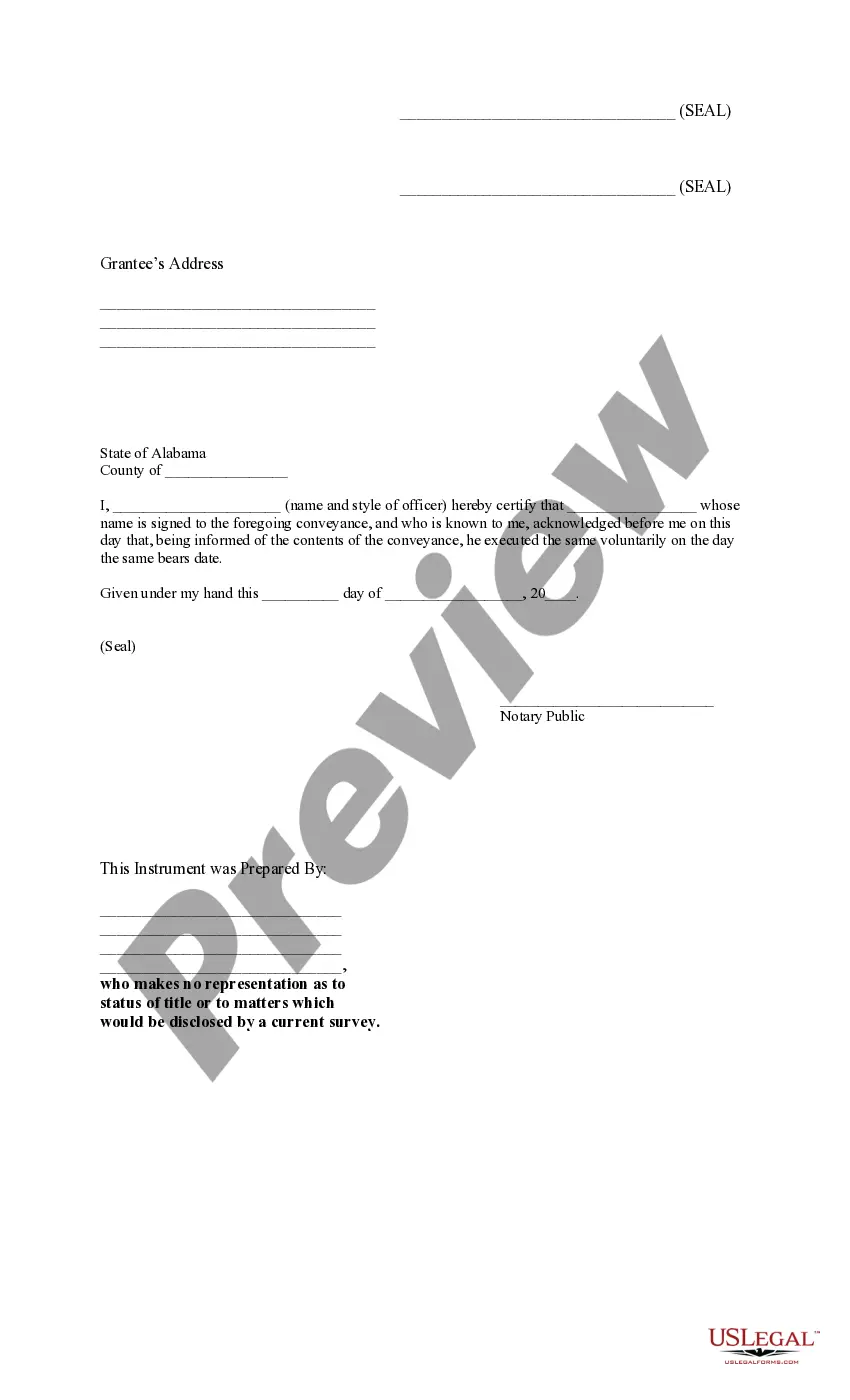
- Signatures of the property owners and witnesses.
- Notary certification to verify the authenticity of the form.
When to use this document
This form is appropriate to use when a property owner is facing financial difficulty and wishes to avoid foreclosure. It is particularly beneficial if the owner wants to relinquish their property without undergoing the complicated foreclosure process, allowing for a smoother transition and potentially less damage to their credit score.
Who should use this form
This form is intended for:
- Homeowners facing imminent foreclosure due to financial hardship.
- Property owners who wish to expedite the transfer of their property to a lender.
- Lenders looking to accept a property deed in lieu of foreclosure as an alternative to traditional foreclosure proceedings.
How to complete this form
- Identify and insert the names of all parties involved (i.e., property owner and lender).
- Specify the address and legal description of the property being conveyed.
- Enter the details of the mortgage being canceled, including dates and recording information.
- Provide signatures of all grantors, ensuring proper witnessing as required.
- Obtain notarization from a qualified notary public to validate the document.
Does this document require notarization?
Yes, this form must be notarized to be legally valid. The notarization process confirms the identities of the parties involved and their voluntary execution of the deed. US Legal Forms offers integrated online notarization through secure video calls, making the process convenient and accessible.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Mistakes to watch out for
- Failing to include accurate property descriptions, which can lead to legal disputes.
- Not obtaining necessary notary signatures, making the deed invalid.
- Omitting witness signatures when required by law.
Advantages of online completion
- Convenience of accessing and filling out the form from anywhere.
- Easy to edit and tailor the form to specific needs before downloading.
- Reliable templates drafted by licensed attorneys to ensure legal compliance.
Looking for another form?
Form popularity
FAQ
A deed in lieu can eliminate your deficiency if you owe more on your home than the home is worth. In exchange for giving the lender your deed voluntarily and keeping the home in good condition, your lender may agree to forgive your deficiency or greatly reduce it.
The deed in lieu of foreclosure offers several advantages to both the borrower and the lender. The principal advantage to the borrower is that it immediately releases him/her from most or all of the personal indebtedness associated with the defaulted loan.
Both short sales and deeds in lieu can help homeowners avoid foreclosure.One benefit to these options is that that you won't have a foreclosure on your credit history. But your credit score will still take a major hit. A short sale or deed in lieu is almost as bad as a foreclosure when it comes to credit scores.
The impact that a deed in lieu has on your score depends primarily on your credit history.According to FICO, if you start with a score of around 780, a deed in lieu (without a deficiency balance) shaves 105 to 125 points off your score; but if you start with a score of 680, you'll lose 50 to 70 points.
Less damage to your credit: A deed in lieu agreement stays on your credit report for 4 years while a foreclosure sticks around for 7 years. Taking a deed in lieu agreement can allow you to buy a new home sooner than if you were to go through a foreclosure.
The purchaser must pay off both the mortgage and junior lienholders after the sale. What is a major disadvantage to lenders of accepting a deed in lieu of foreclosure? a. The lender takes the real estate subject to all junior liens.
If your lender agrees to a short sale or to accept a deed in lieu of foreclosure, you might owe federal income tax on any forgiven deficiency. The IRS learns of the deficiency when the lender sends it a Form 1099-C, which reports the forgiven debt as income to you.
A deed in lieu of foreclosure is different from a short sale because it transfers the property to the lender instead of selling it to a new buyer.Most lenders find this option less appealing than a short sale because they will need to handle the logistics of the sale instead of the homeowner.