Sell Of Partnership In Montgomery
Description
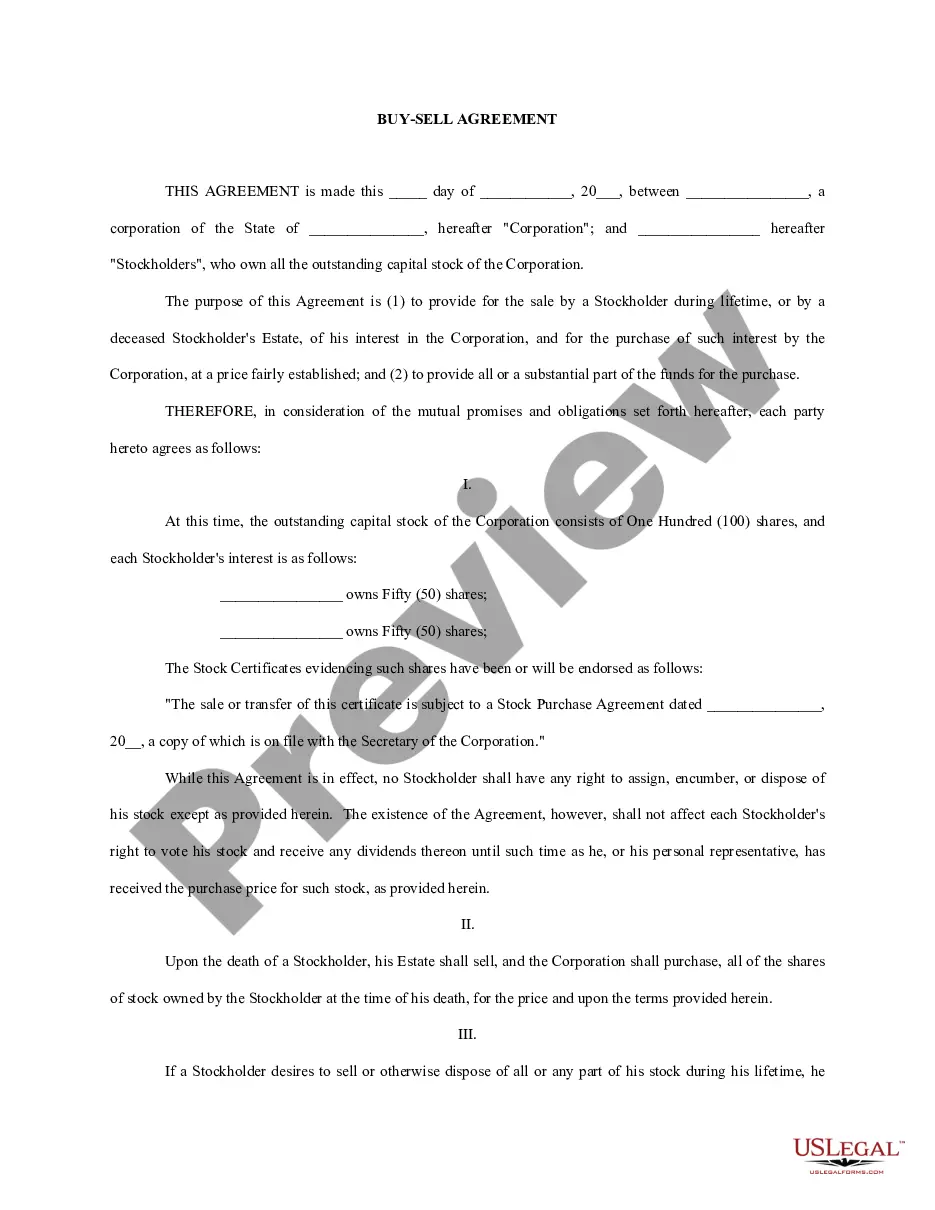
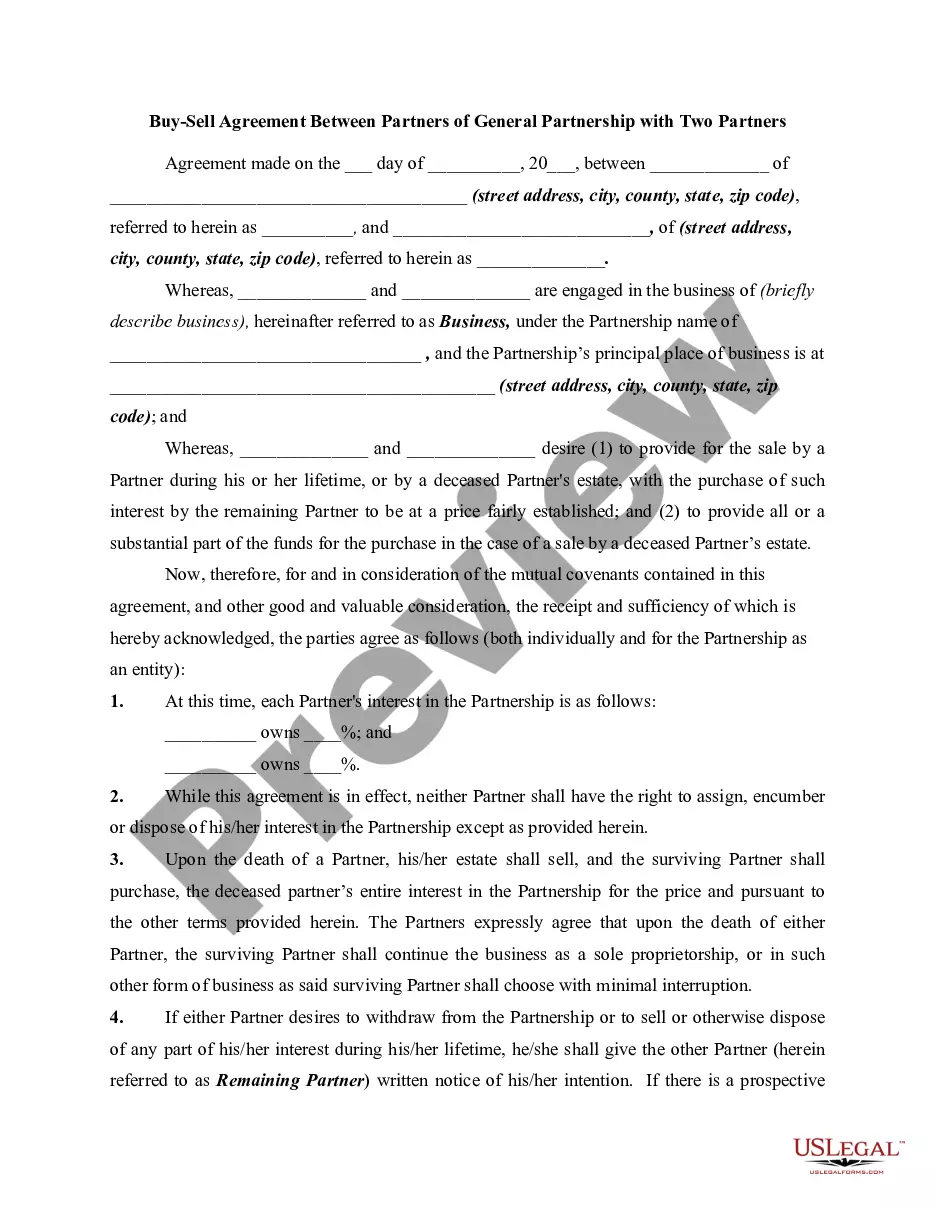
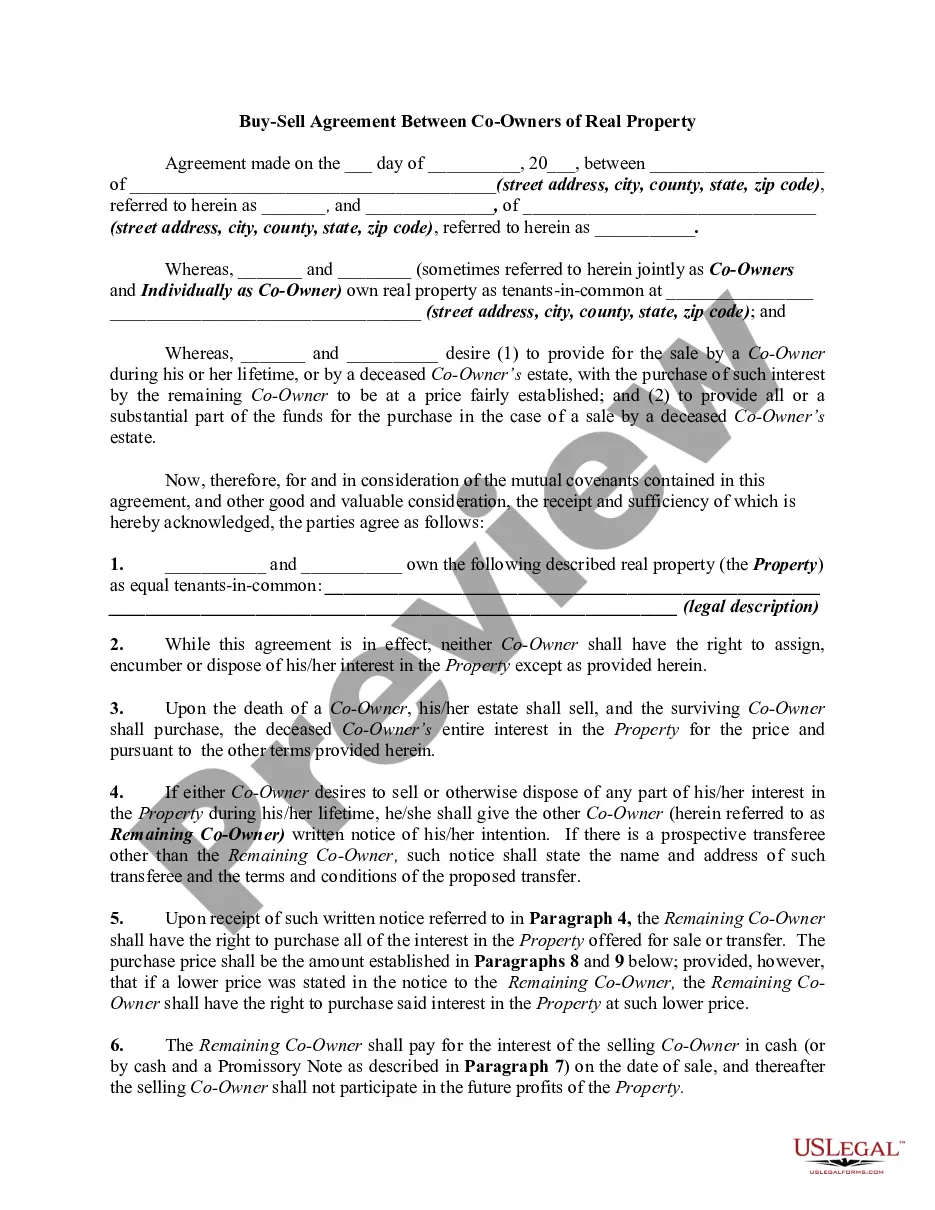
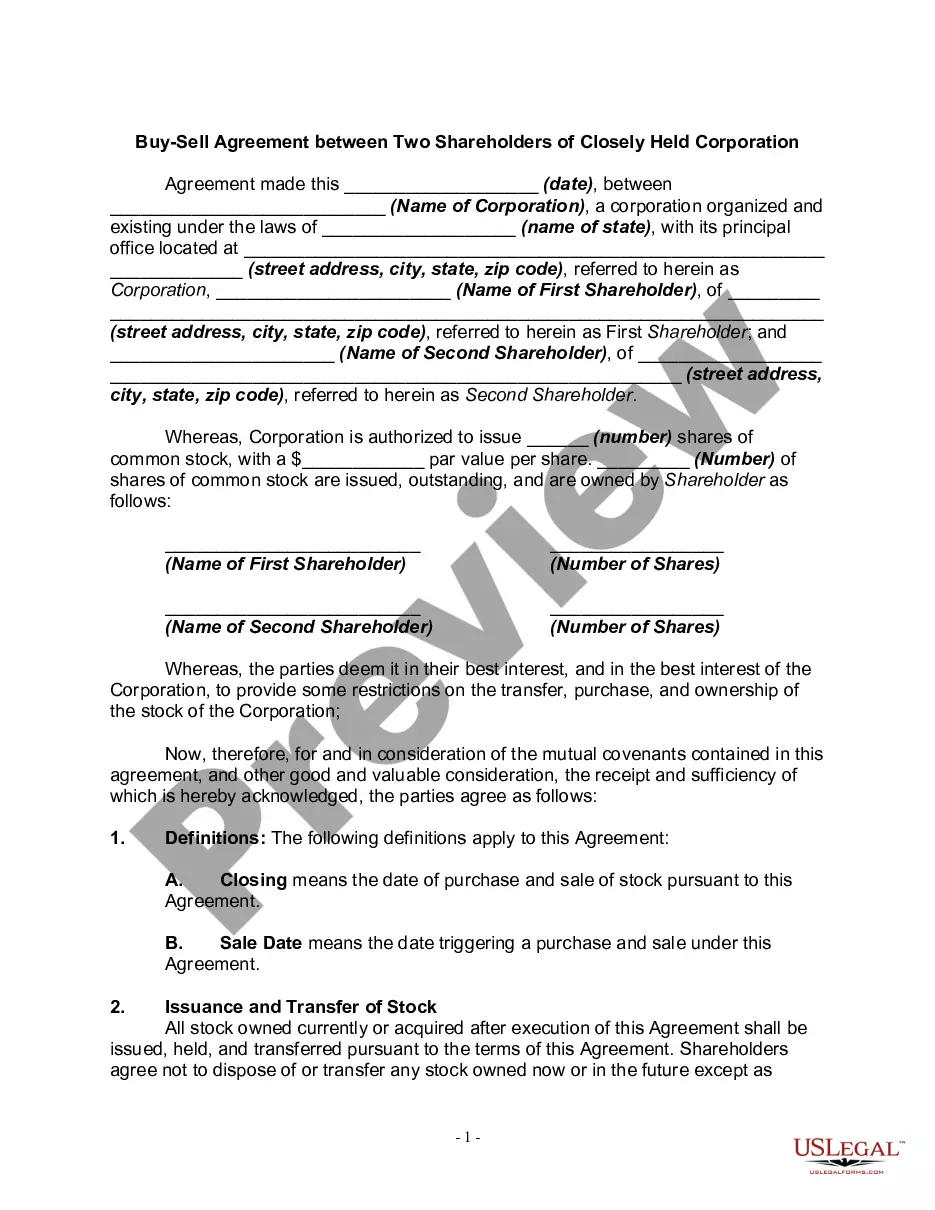
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
Form popularity
FAQ
If a partnership holds IRC 751(a) property at the time of the sale, the partner recognizes gain or loss from its share of IRC 751(a) assets. The ordinary gain or loss is subtracted from the total gain or loss. The result is the partner's capital gain or loss from the sale.
Interest on capital will be allowed only when there are profits. Interest on capital is only given to partners when there are profits. In case of losses, partners are not given interest on capital. Interest on capital can be defined as the amount charged as interest on partner's capital.
The gain or loss from the sale of a partnership interest is the difference between the sales proceeds received and the partner's tax basis in the interest at the time of the sale.
Generally, a partner selling his partnership interest recognizes capital gain or loss on the sale. The amount of the gain or loss recognized is the difference between the amount realized and the partner's adjusted tax basis in his partnership interest.
Generally, a partner selling his partnership interest recognizes capital gain or loss on the sale. The amount of the gain or loss recognized is the difference between the amount realized and the partner's adjusted tax basis in his partnership interest.
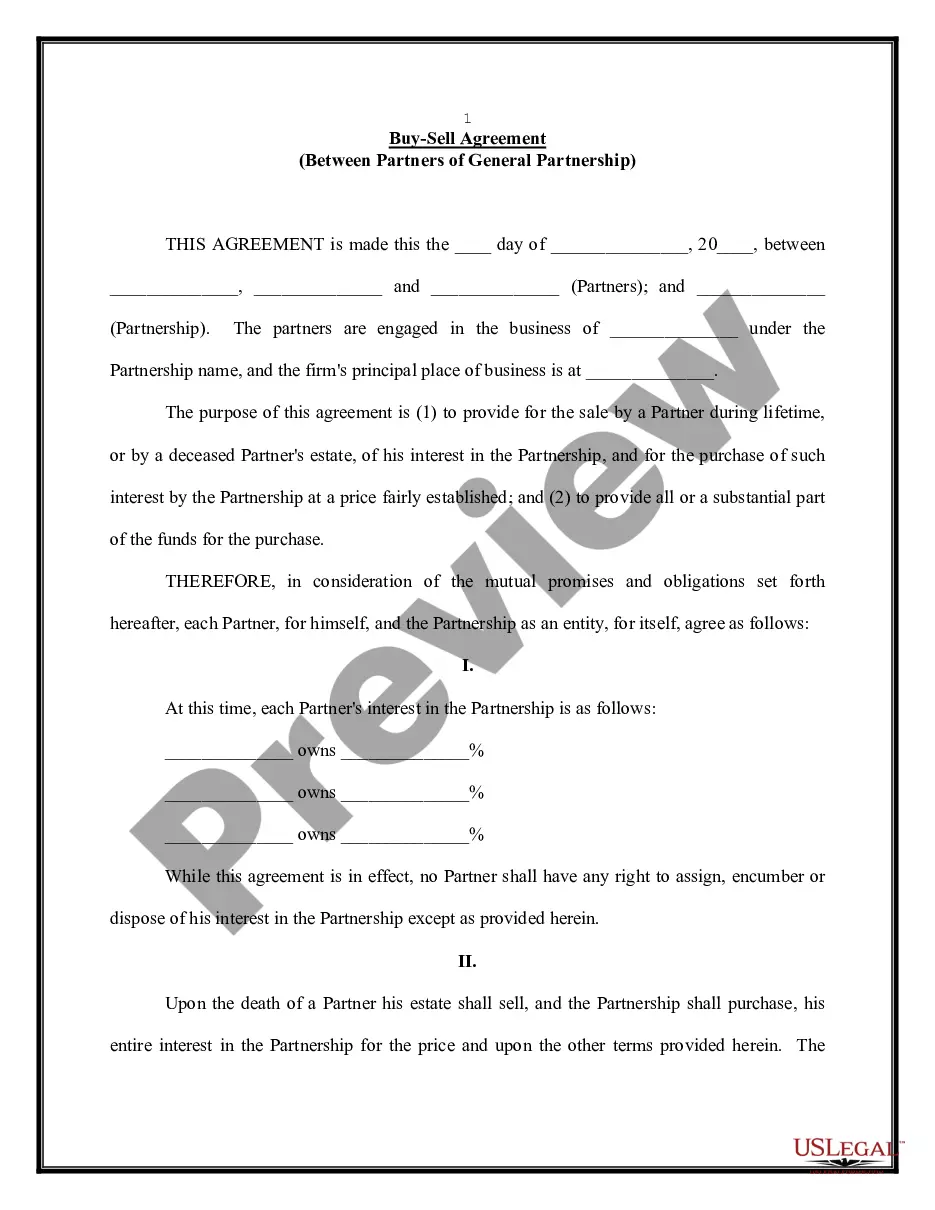
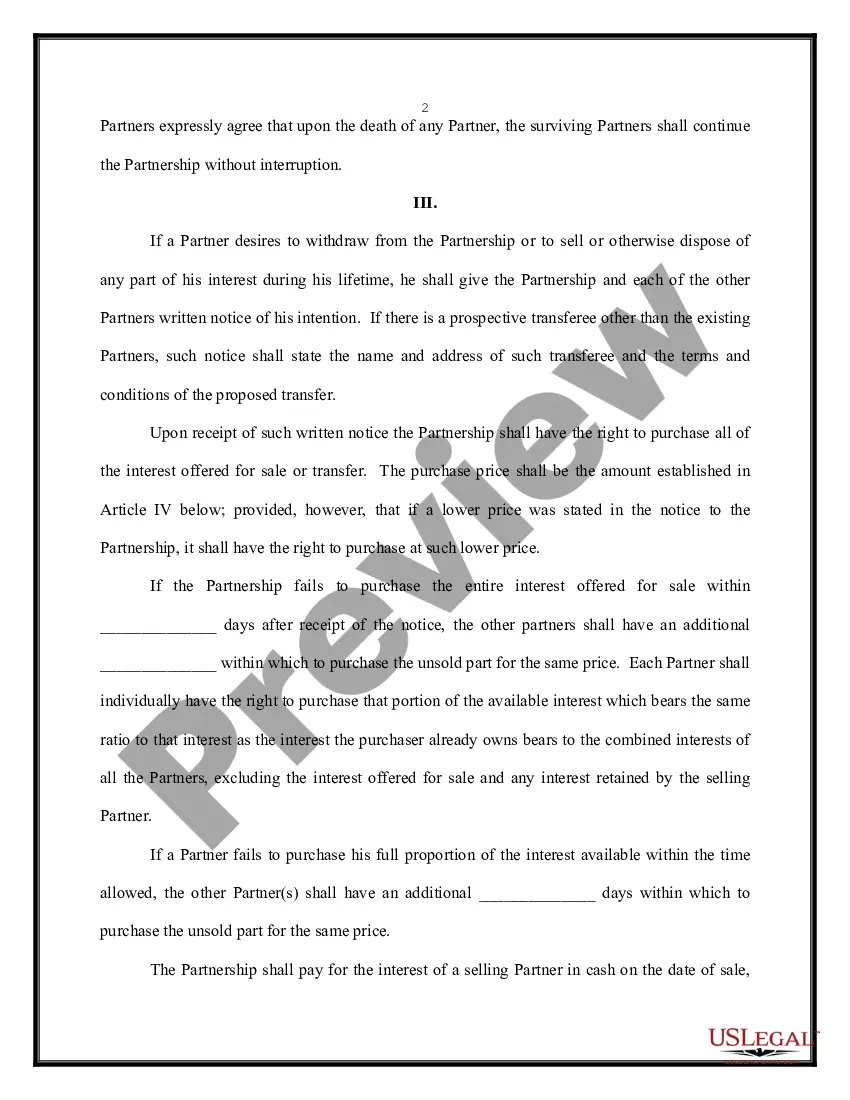
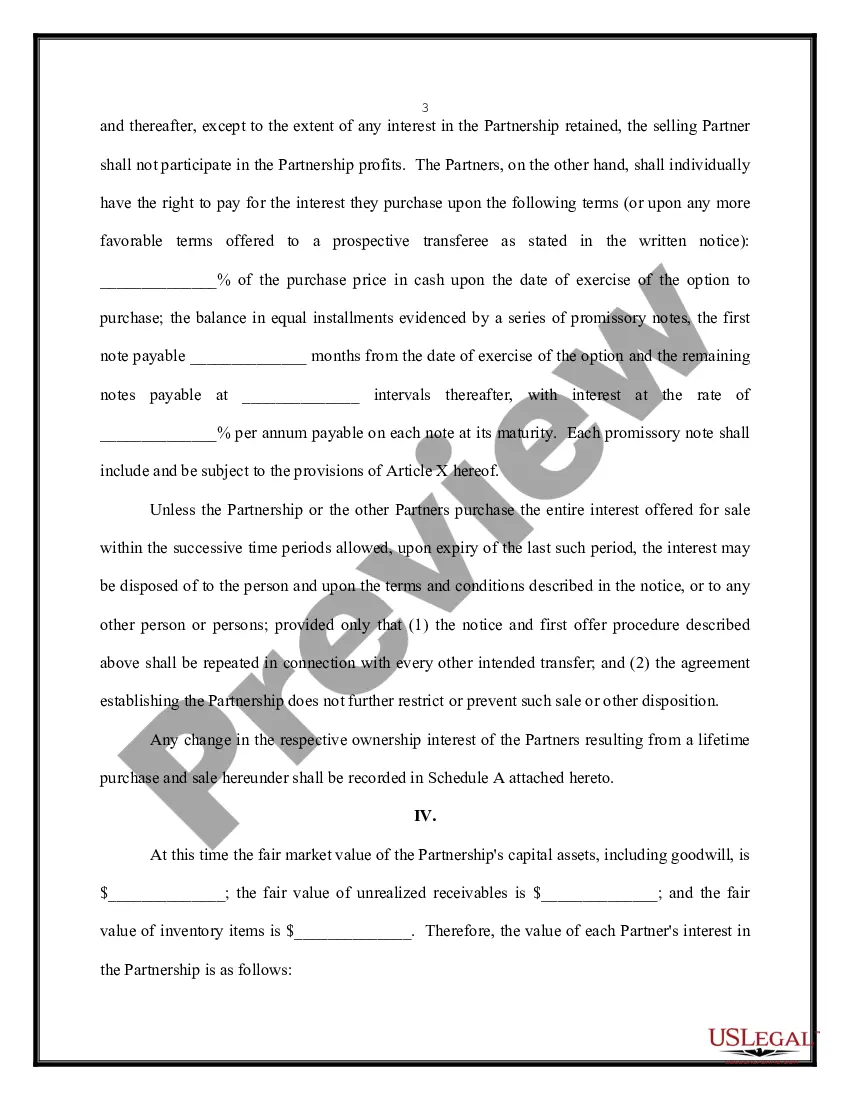
A transfer of partnership interest involves transferring ownership, profits, losses, and management responsibilities from one partner to another or to a new entity. Partnership agreements typically dictate the terms of transfer, often including restrictions like the right of first refusal for existing partners.
Returns for both partnerships and single member limited liability entities, whether filing as a separate entity or as a disregarded entity, as a division of its owner, are required to be filed on or before the date the taxpayer's corresponding federal tax return is due.
Filing Requirement: Every corporation, limited liability entity, and disregarded entity doing business in Alabama or organized, incorporated, qualified, or registered under the laws of Alabama is required to file an Alabama Business Privilege Tax Return.
Alabama residents should file a Resident Individual Income Tax Return, Form 40 or 40A, each year. If I am not a resident of Alabama, but earned income from Alabama sources, am I required to file an Alabama tax return? Yes.
All Alabama S corps are required to annually file the Alabama Business Privilege Tax Return and Annual Report for Pass-Through Entities (Form PPT).