Unfair Trade Practices In Insurance In Phoenix
Description
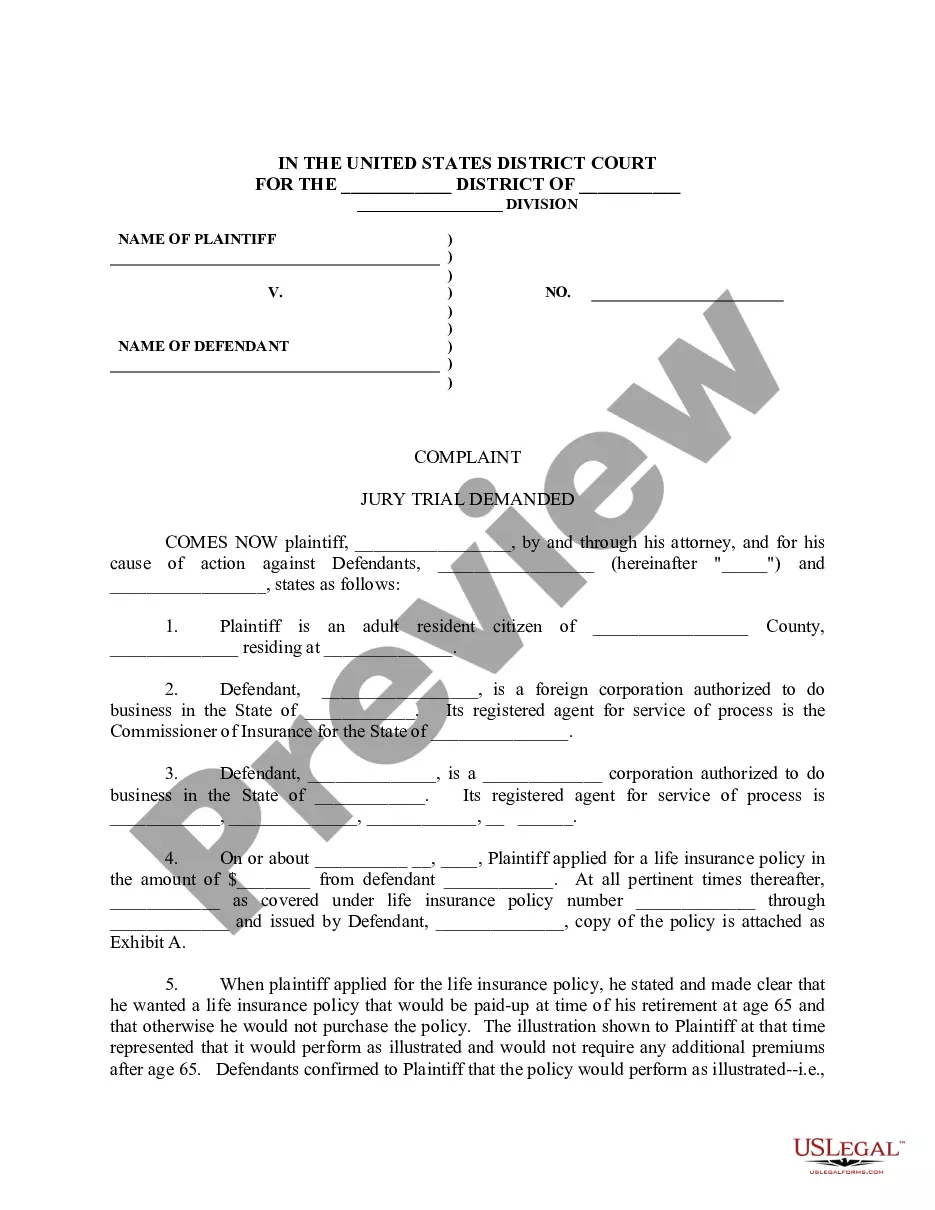
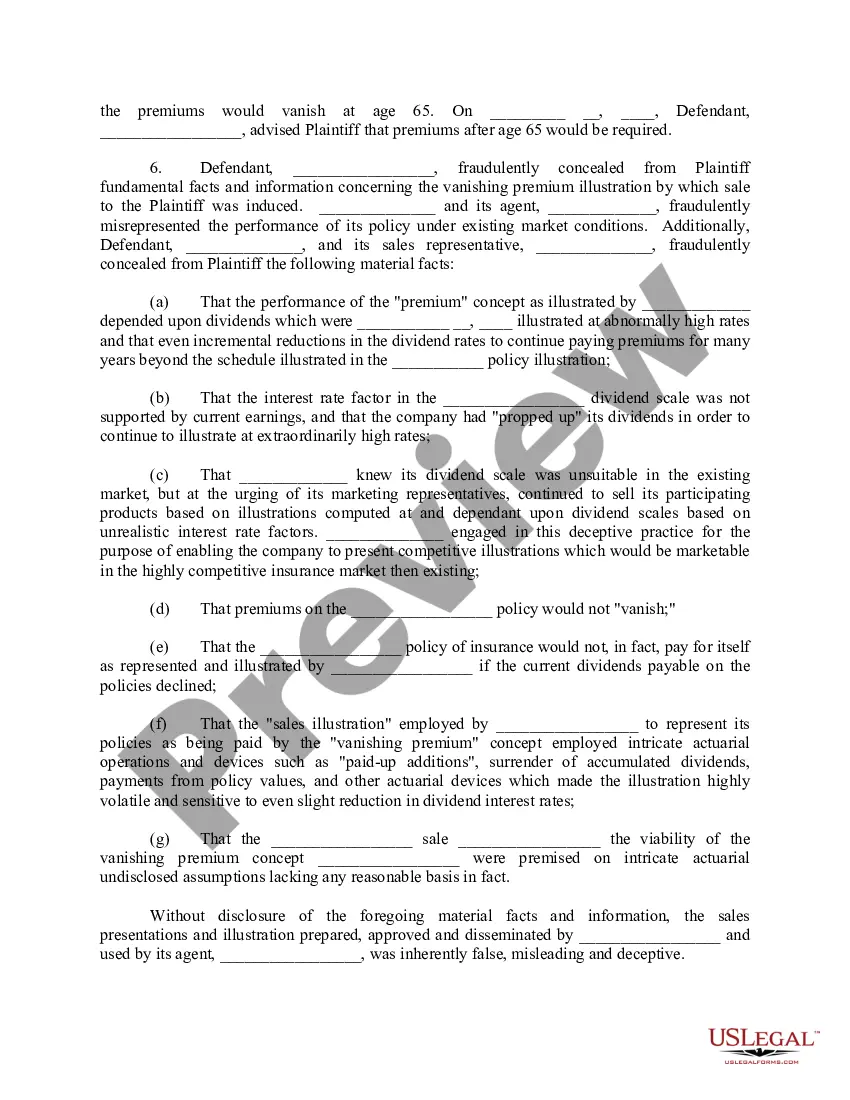
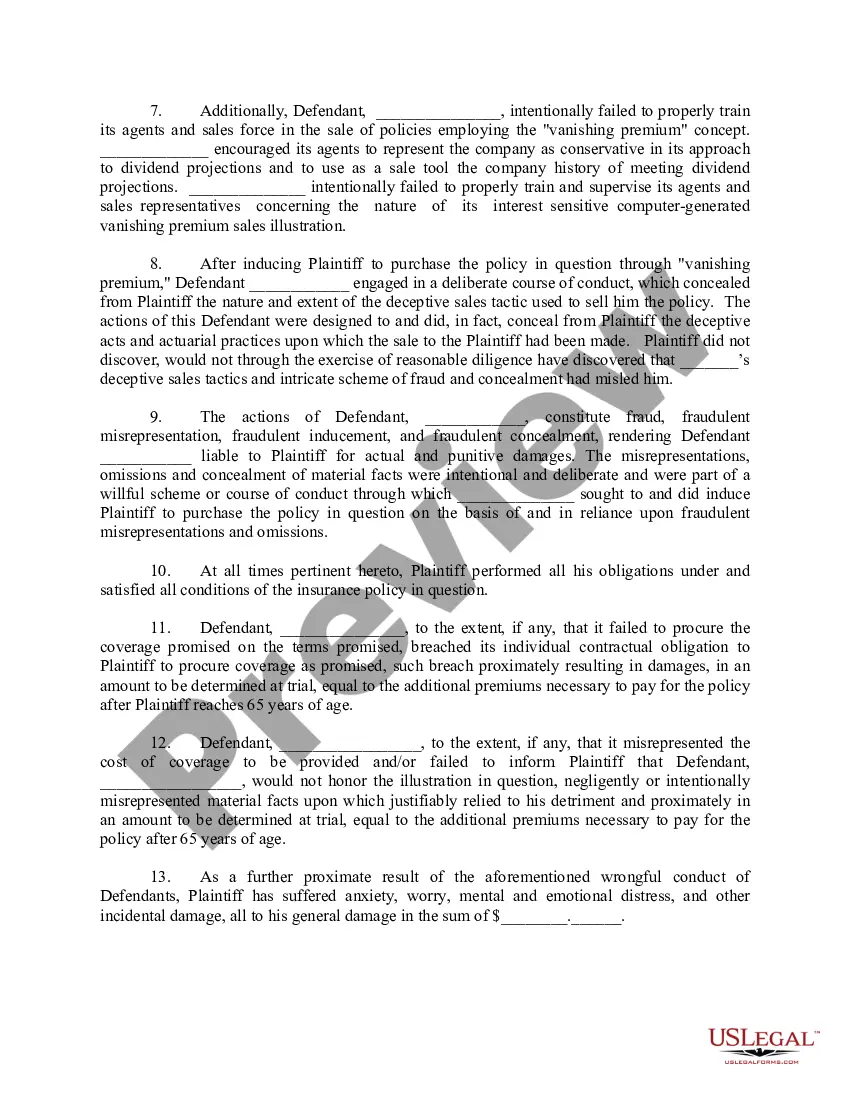
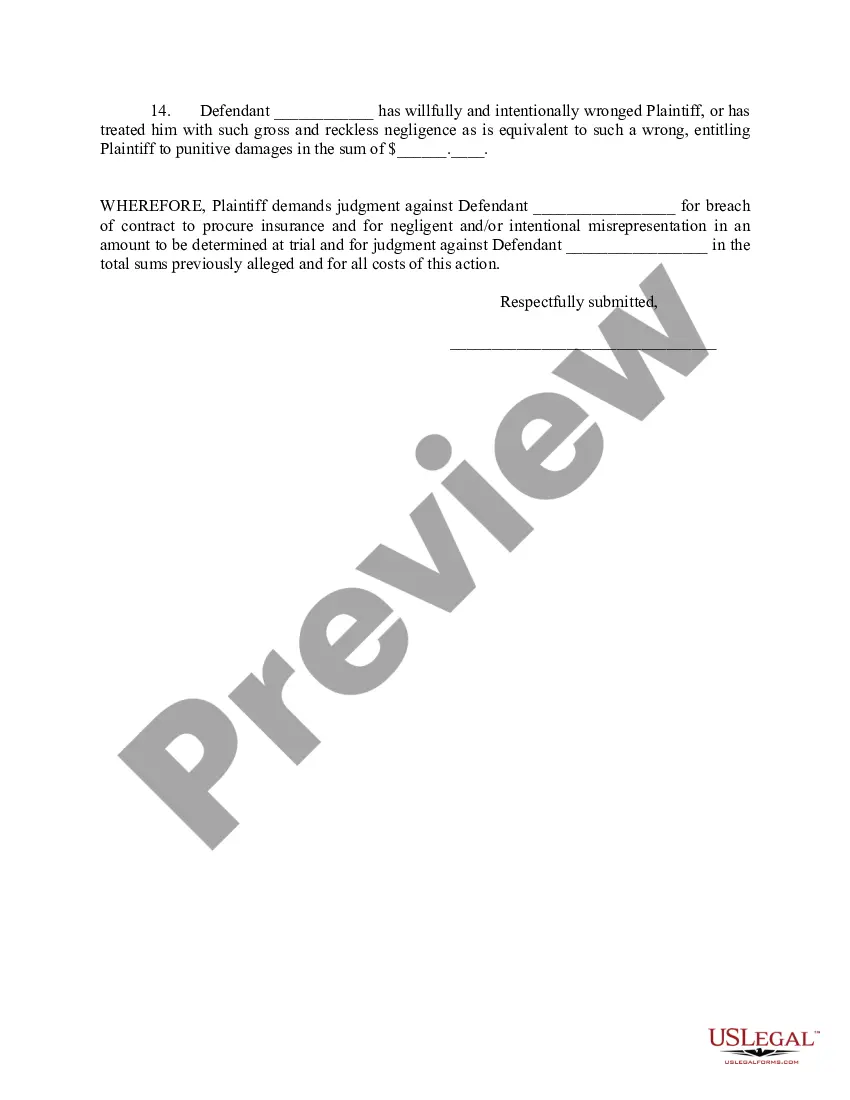
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?


Form popularity
FAQ
File a complaint with your local consumer protection office or the state agency that regulates the company. Notify the Better Business Bureau (BBB) in your area about your problem. The BBB tries to resolve your complaints against companies.
Two keywords in the Unfair Claim Settlement Practices Act are “reasonably” and “promptly”—insurance companies are required to take reasonable and quick action on claims. For instance, they can't leave you in the dark for weeks and then deny your claim without any explanation; that wouldn't be prompt or reasonable.
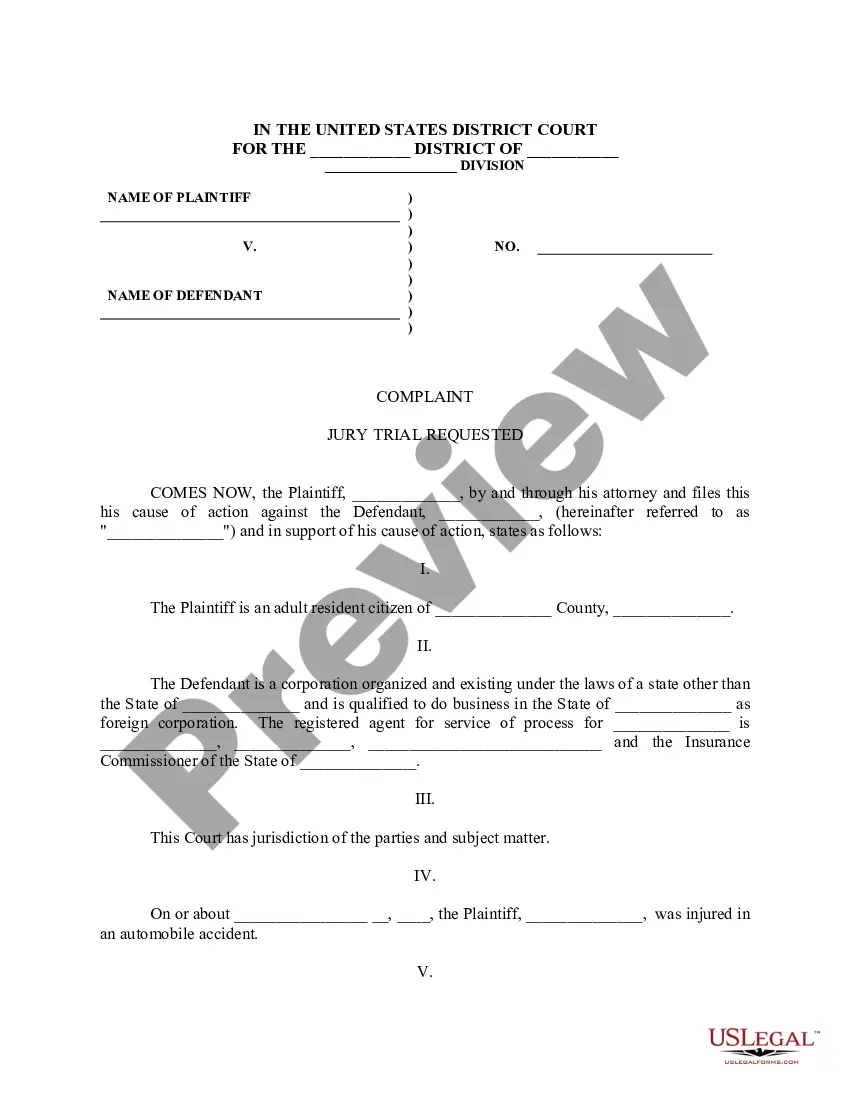
The plaintiff files a document (complaint) with the clerk of the court stating the reasons why the plaintiff is suing the defendant, and what action the plaintiff wants the court to take. A copy of the complaint and a summons are delivered to (served on) the defendant.
The Arizona Consumer Fraud Act (ACFA) is a package of Arizona state laws that give protections to consumers in almost any kind of transaction related to the sale or advertisement of merchandise.
Arizona Revised Statutes, Title 20, outlines insurance law and establishes the Department of Insurance and Financial Institutions (DIFI). The Director of the DIFI, appointed by the Governor, has general authority to enforce insurance laws, to adopt rules, and to investigate and resolve consumer complaints (A.R.S.
After a complaint is filed, it is reviewed by an attorney general representative who determines whether: The complaint is appropriate for mediation by the office. If it should be referred to another governmental entity that may be more suited to assist with the consumer's complaint.
Introduction. Insurance is regulated by the states. This system of regulation stems from the McCarran-Ferguson Act of 1945, which describes state regulation and taxation of the industry as being in “the public interest” and clearly gives it preeminence over federal law. Each state has its own set of statutes and rules.
Assisting and ensuring regulatory compliance of Financial Services operating within Arizona. Providing protections to Arizona residents insured by a licensed insurance company that becomes insolvent. Providing information on the prevention of vehicle crimes throughout Arizona.
Arizona Department of Insurance and Financial Institutions (DIFI) | Arizona State Library.
The law broadly prohibits businesses from using deceptive or unfair practices, fraud, misrepresentation, and omission of material fact during the sale or advertisement of goods and services.