Nebraska Non-Foreign Affidavit Under IRC 1445
About this form
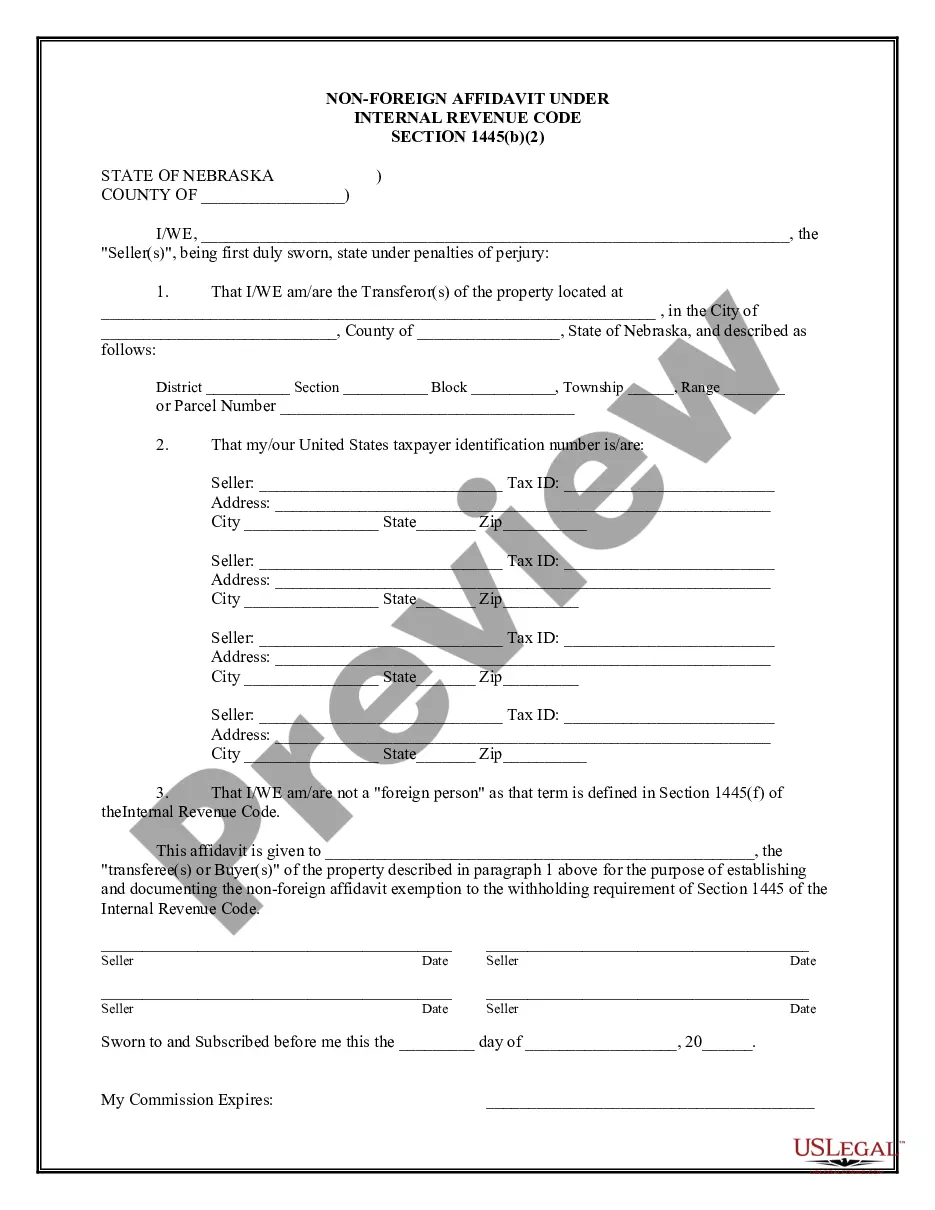
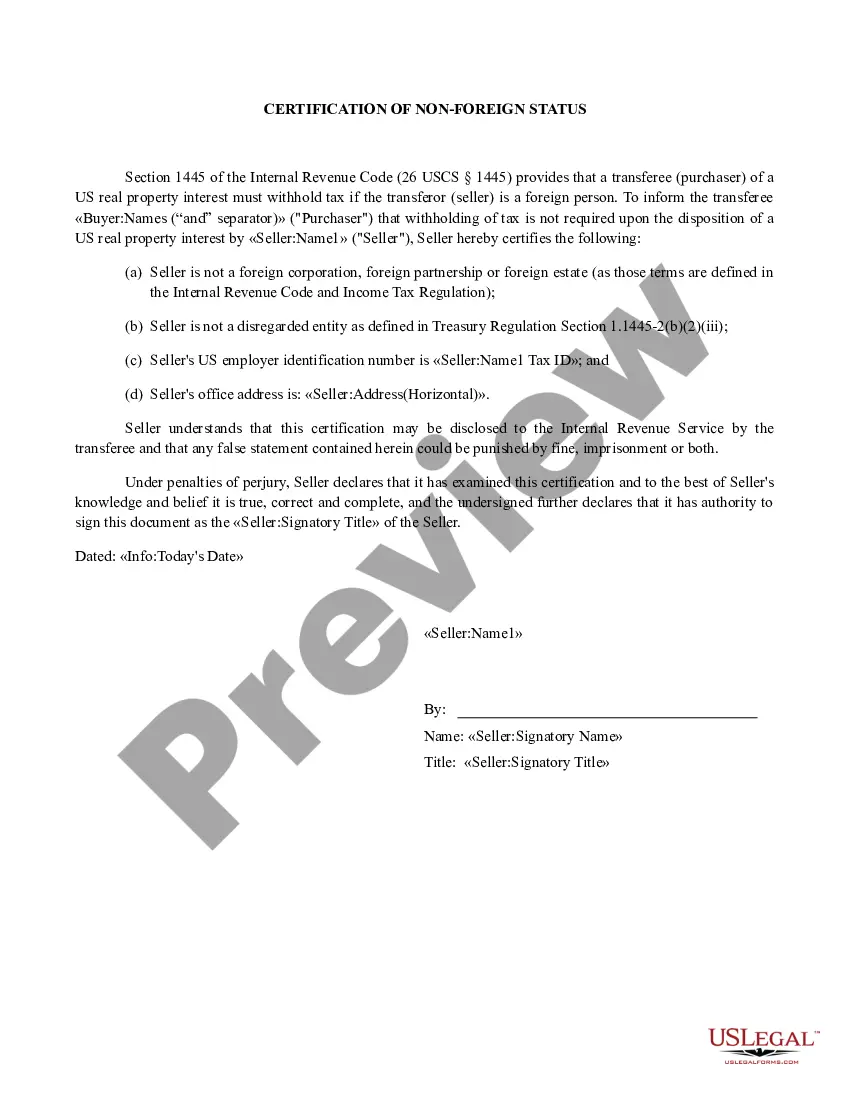
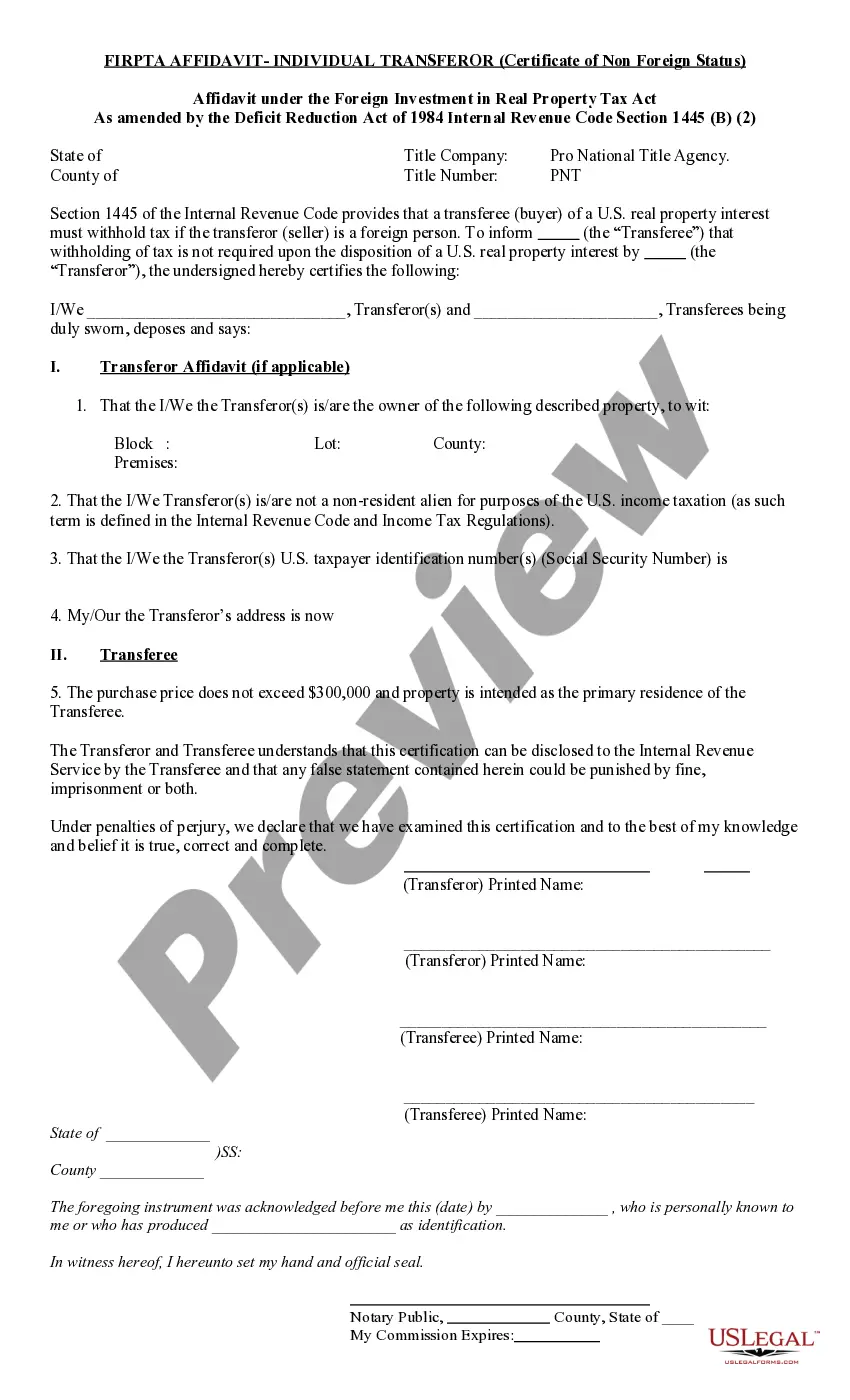
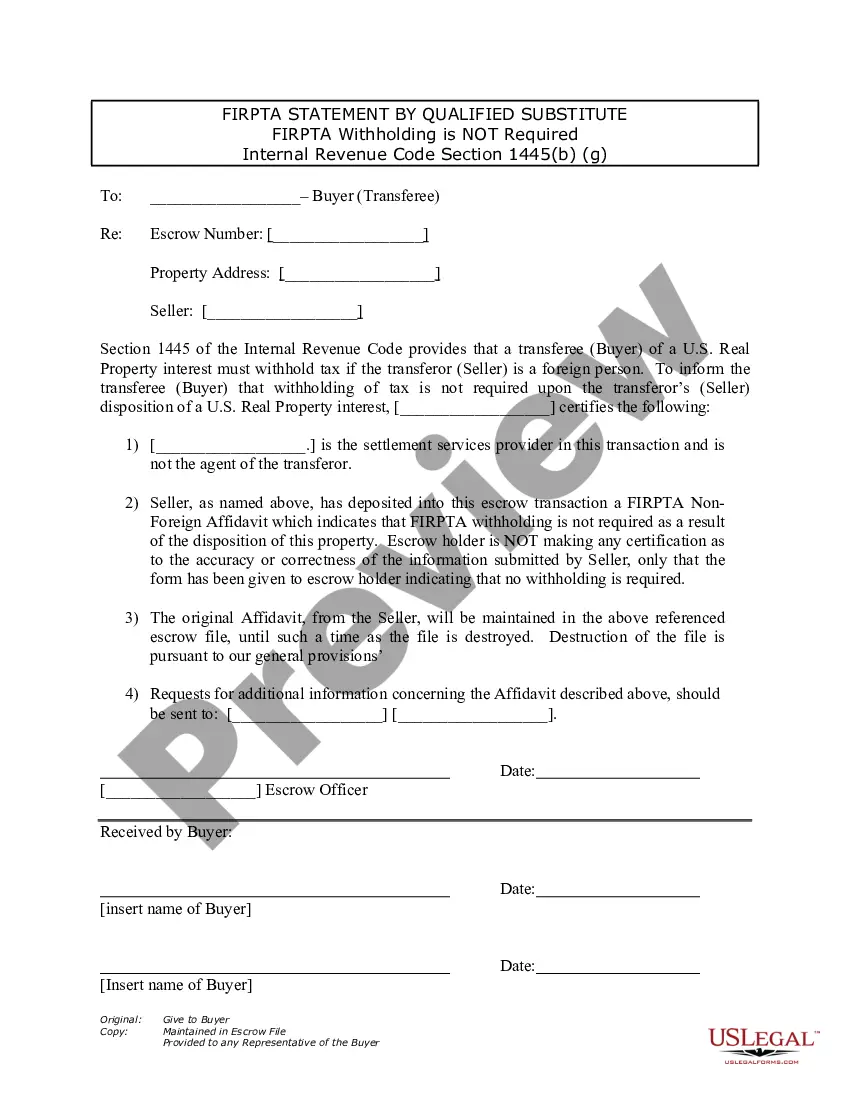
The Non-Foreign Affidavit Under IRC 1445 is a legal document that a seller of real property must sign to confirm they are not a foreign person as defined by the Internal Revenue Code. This affidavit serves to exempt the buyer from withholding requirements related to the sale of the property. It is crucial for transactions involving real estate to verify the status of the seller, ensuring compliance with tax regulations.
What’s included in this form
- Identification of the seller(s) and their taxpayer identification number(s).
- Details of the property being sold, including its address and parcel number.
- A declaration affirming that the seller(s) are not foreign persons, as defined by the tax code.
- Space for signatures of the seller(s) and a notary public.
When to use this document
This form should be used when selling real estate to establish that the seller is not a foreign person, thus avoiding unnecessary withholding taxes. It is commonly needed during property sales to ensure compliance with the Internal Revenue Code, particularly for transactions where the buyer must document the seller's non-foreign status.
Intended users of this form
- Individual or entity sellers of real estate in the United States.
- Real estate agents or attorneys representing sellers in property transactions.
- Buyers who need verification of the seller's status to comply with tax withholding requirements.
Completing this form step by step
- Identify the seller(s) by entering their full names and taxpayer identification numbers.
- Provide the complete address and legal description of the property being sold.
- Confirm that the seller(s) are not foreign persons by checking the appropriate section.
- Sign and date the affidavit in the presence of a notary public.
- Ensure all required parties sign and that the notary acknowledges the document.
Does this form need to be notarized?
Yes, this form must be notarized to be legally valid. The notarization process helps to verify the identities of the seller(s) and ensures that the affidavit is executed properly. US Legal Forms provides integrated online notarization services, making it easy to complete this step securely and conveniently.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
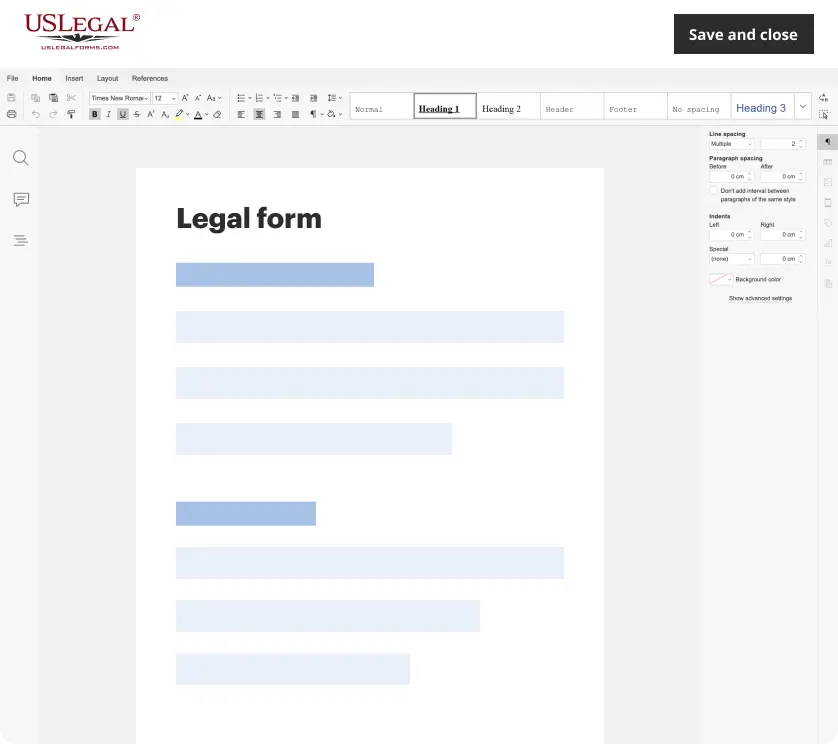
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Mistakes to watch out for
- Failing to include all seller(s) information, including taxpayer identification numbers.
- Not accurately describing the property being sold.
- Forgetting to sign the affidavit or to have it notarized.
Why use this form online
- Convenience of completing the form online from anywhere.
- Editability allows users to tailor the form to their specific situation.
- Reliability, as the document is drafted by licensed attorneys.
- Quick access to necessary legal forms without the need for in-person appointments.
Legal use & context
- This affidavit is a legally binding document that aids in tax compliance for real estate transactions.
- It helps protect both buyers and sellers from unexpected tax liabilities.
Summary of main points
- The Non-Foreign Affidavit is essential for sellers to confirm their tax status.
- Proper completion of the form can prevent withholding tax issues during the sale of property.
- Notarization is required to ensure the legality of the affidavit.
Looking for another form?
Form popularity
FAQ
FIRPTA Exemptions The sales price is $300,000 or less, and. The buyer signs affidavit at or before closing stating they intend to use property for personal purposes for at least 50% of time property occupied for the each of the first two 12 month periods immediately after closing.
Foreign affidavit is an affidavit involving a matter of concern in one state but taken in another state or country before an officer of that state or country.
The disposition of a U.S. real property interest by a foreign person (the transferor) is subject to income tax withholding (IRC section 1445). The transferee is the withholding agent.If the transferor is a foreign person and you fail to withhold, you may be held liable for the tax.
A foreign person includes a nonresident alien individual, foreign corporation, foreign partnership, foreign trust, foreign estate, and any other person that is not a U.S. person. It also includes a foreign branch of a U.S. financial institution if the foreign branch is a qualified intermediary.
This document, included in the seller's opening package, requests that the seller swears under penalty of perjury that they are not a non-resident alien for purposes of United States income taxation. A Seller unable to complete this affidavit may be subject to withholding up to 15%.
The disposition of a U.S. real property interest by a foreign person (the transferor) is subject to the Foreign Investment in Real Property Tax Act of 1980 (FIRPTA) income tax withholding. FIRPTA authorized the United States to tax foreign persons on dispositions of U.S. real property interests.
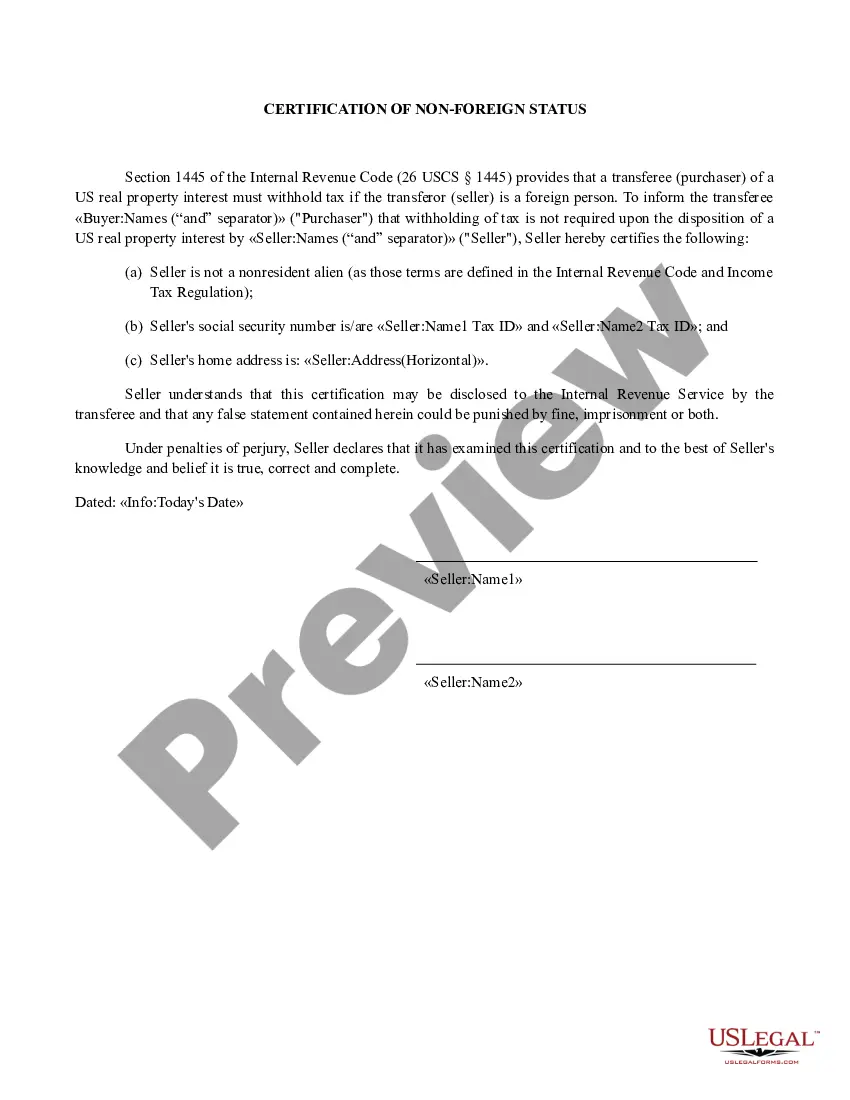
What Is a Certification of Non-Foreign Status? With a Certification of Non-Foreign Status, the seller of real estate is certifying under penalty of perjury, that the seller is not foreign. Therefore, the seller and the transaction will not have the withholding requirements.
You or a member of your family must have definite plans to reside at the property for at least 50% of the number of days the property is used by any person during each of the first two 12-month periods following the date of transfer.
The only other way to avoid FIRPTA is via a withholding certificate. If FIRPTA withholding exceeds the maximum tax liability realized on the sale of the real property, sellers can appeal to the IRS for a lower withholding amount.