FIRPTA Statement By Qualified Substitute
What this document covers
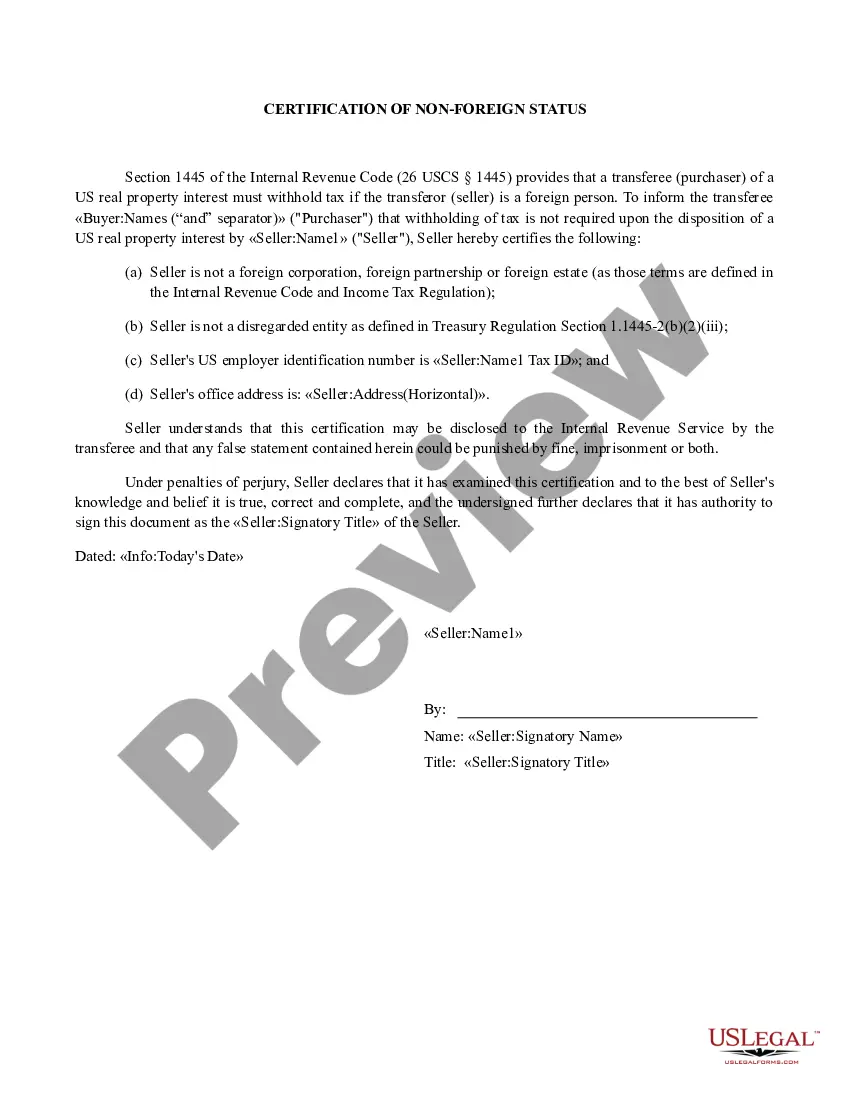
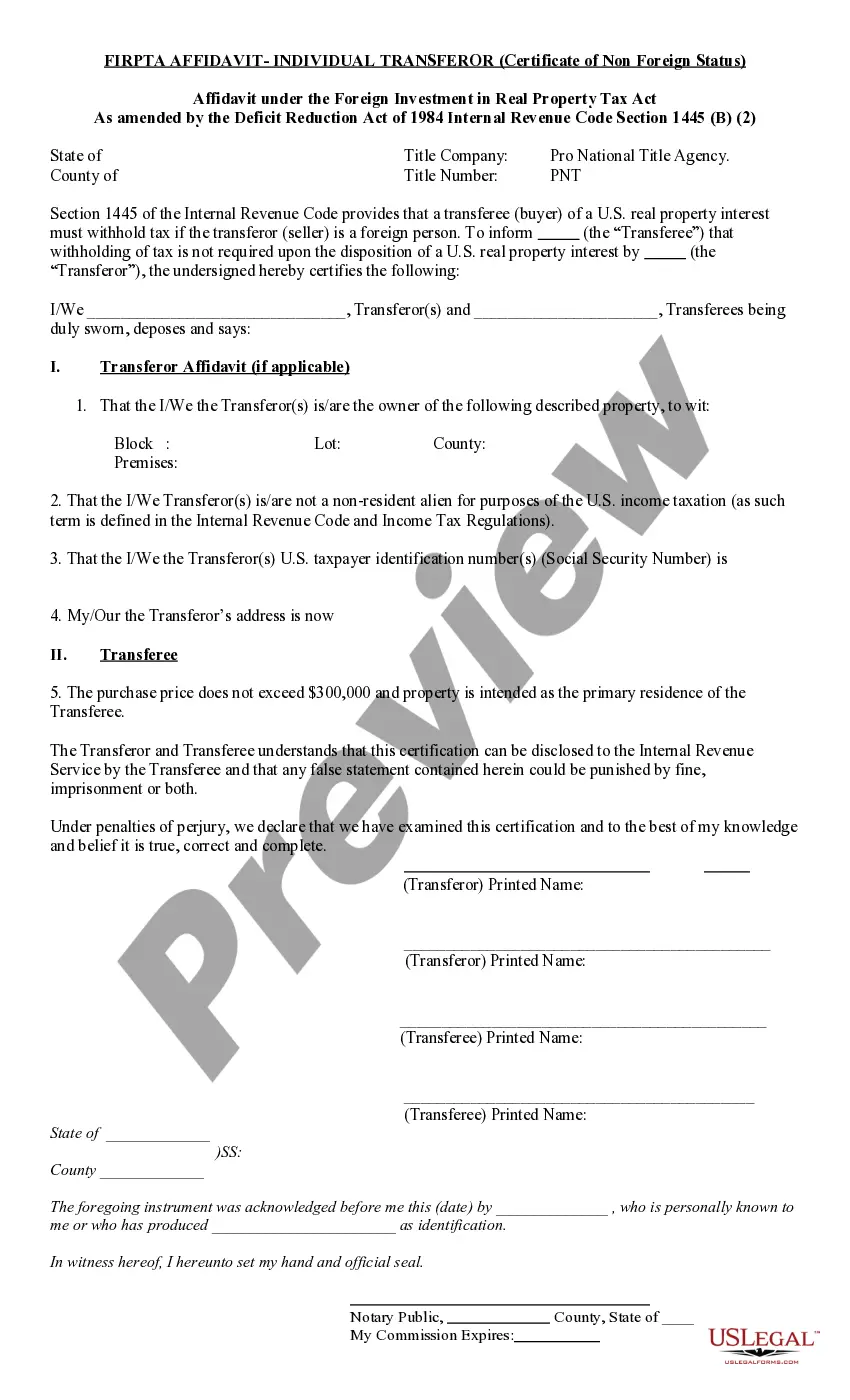
The FIRPTA Statement By Qualified Substitute is a legal document used under the Foreign Investment in Real Property Tax Act (FIRPTA). This form certifies that a Qualified Substitute, which is either a person or an entity recognized under FIRPTA, can accept a Seller's Affidavit on behalf of the Buyer, indicating that no tax withholding is required on the transfer. It is essential for facilitating real estate transactions involving foreign sellers while ensuring compliance with tax regulations.
Main sections of this form
- Identifies the Buyer (Transferee) and Seller involved in the transaction.
- Includes property address and escrow number for proper identification.
- Certifies the Seller's Non-Foreign Affidavit and confirms that FIRPTA withholding is not required.
- Indicates the roles of the settlement services provider and the escrow holder in the transaction.
- Details the process for maintaining the Sellerâs Affidavit in the escrow file.
When to use this document
This form is used in real estate transactions where the Seller is a foreign individual or entity. It should be completed when the Buyer needs to confirm that no FIRPTA withholding is necessary due to the Seller's status. This typically occurs when the Seller certifies their non-foreign status through the Non-Foreign Affidavit submitted during the closing process.
Intended users of this form
- Buyers (Transferees) acquiring U.S. real property from a foreign Seller.
- Qualified Substitutes acting on behalf of a Seller to facilitate the transaction.
- Escrow agents handling the closing of the real estate transaction.
- Real estate attorneys assisting clients with compliance under FIRPTA regulations.
Completing this form step by step
- Identify the parties involved by entering the names of the Buyer and Seller.
- Specify the property address and related escrow number for reference.
- Complete the sections for certifying the Seller's Non-Foreign Affidavit.
- Enter the name and signature of the Escrow Officer and the Buyer.
- Distribute copies as indicated: retain a copy in the escrow file and provide the original to the Buyer.
Is notarization required?
This form does not typically require notarization unless specified by local law. It is essential, however, to check local requirements to ensure compliance during the transaction.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Common mistakes to avoid
- Failing to properly identify all parties involved in the transaction.
- Leaving key sections, such as the property address or escrow number, incomplete.
- Using outdated versions of the form that do not comply with current FIRPTA regulations.
- Neglecting to keep a copy of the Seller's Affidavit in the escrow file as required.
Why use this form online
- Convenience of downloading and editing the form from anywhere at any time.
- Access to up-to-date legal resources and templates drafted by licensed attorneys.
- Easy integration of necessary information without the hassle of physical paperwork.
Looking for another form?
Form popularity
FAQ
To ensure that the buyer does not withhold funds, the foreign seller should file a 1031 Declaration Notice. With advance planning, you can receive permission from the IRS to prevent FIRPTA withholding on your sale. Once you have received an ITIN or EIN, then you can apply.
A seller may be exempt from FIRPTA if one or more of these circumstances apply: The sales price is less than $300,000 and the buyer (or a family member) has definite plans to reside in the home for at least 50% of the first 24 months of ownership.
Qualified Substitute is the Default. The seller will then manually complete Paragraph 3B and provide the form to the title or escrow company acting as the qualified substitute. The title or escrow company may use C.A.R. Form QS, or its own form, to satisfy its obligation to notify the buyer.
On the day of the USRPI disposition, the transferee must provide written notice to the court or trustee of the transferee's name and address, a brief description of the property, the amount realized on the sale of the property, and the amount withheld under Sec. 1445(a).
A qualified substitute is (1) the person, including an attorney or title company, responsible for closing the transaction, other than the transferor's agent, and (2) the transferor's agent.
(6) Qualified substitute The term ?qualified substitute? means, with respect to a disposition of a United States real property interest? (A) the person (including any attorney or title company) responsible for closing the transaction, other than the transferor's agent, and (B) the transferee's agent.
A qualified investment entity is any real estate investment trust (REIT) or any regulated investment company (RIC). The entity is domestically controlled if at all times during the testing period less than 50% in value of its stock was held, directly or indirectly, by foreign persons.