FIRPTA Clauses: Contract for Real Property
About this form
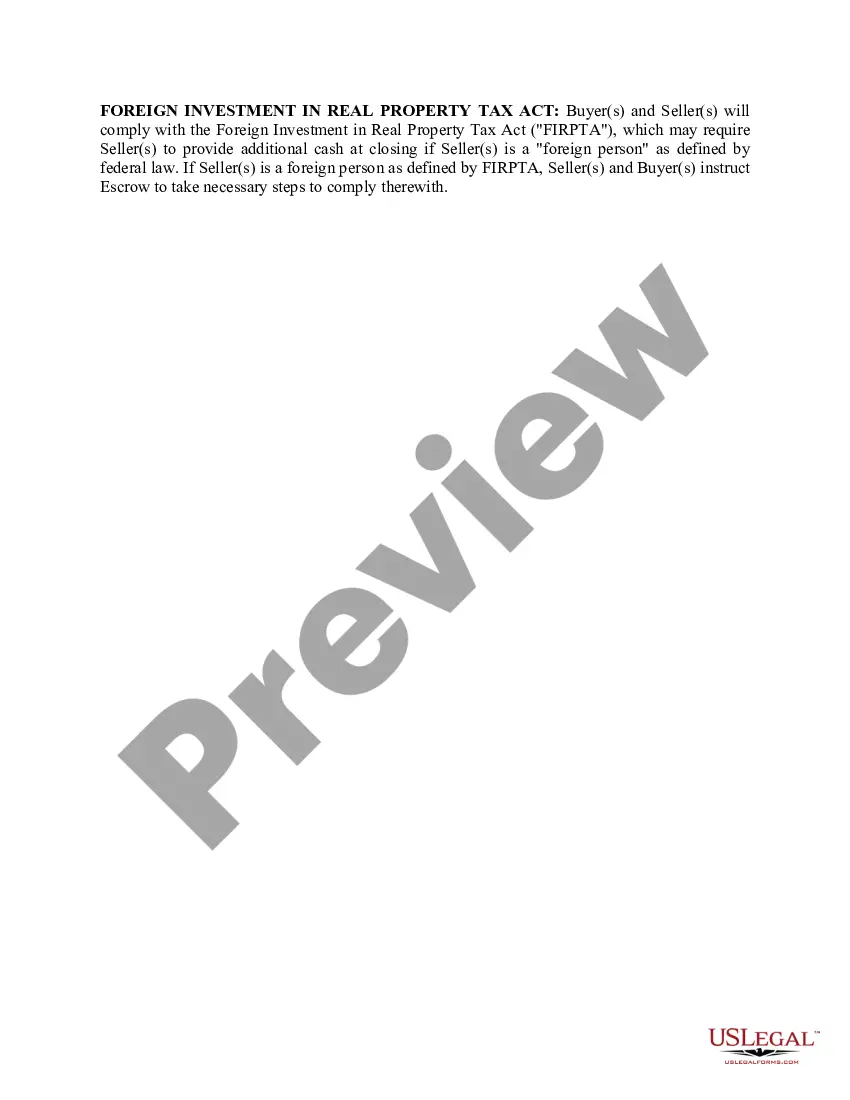
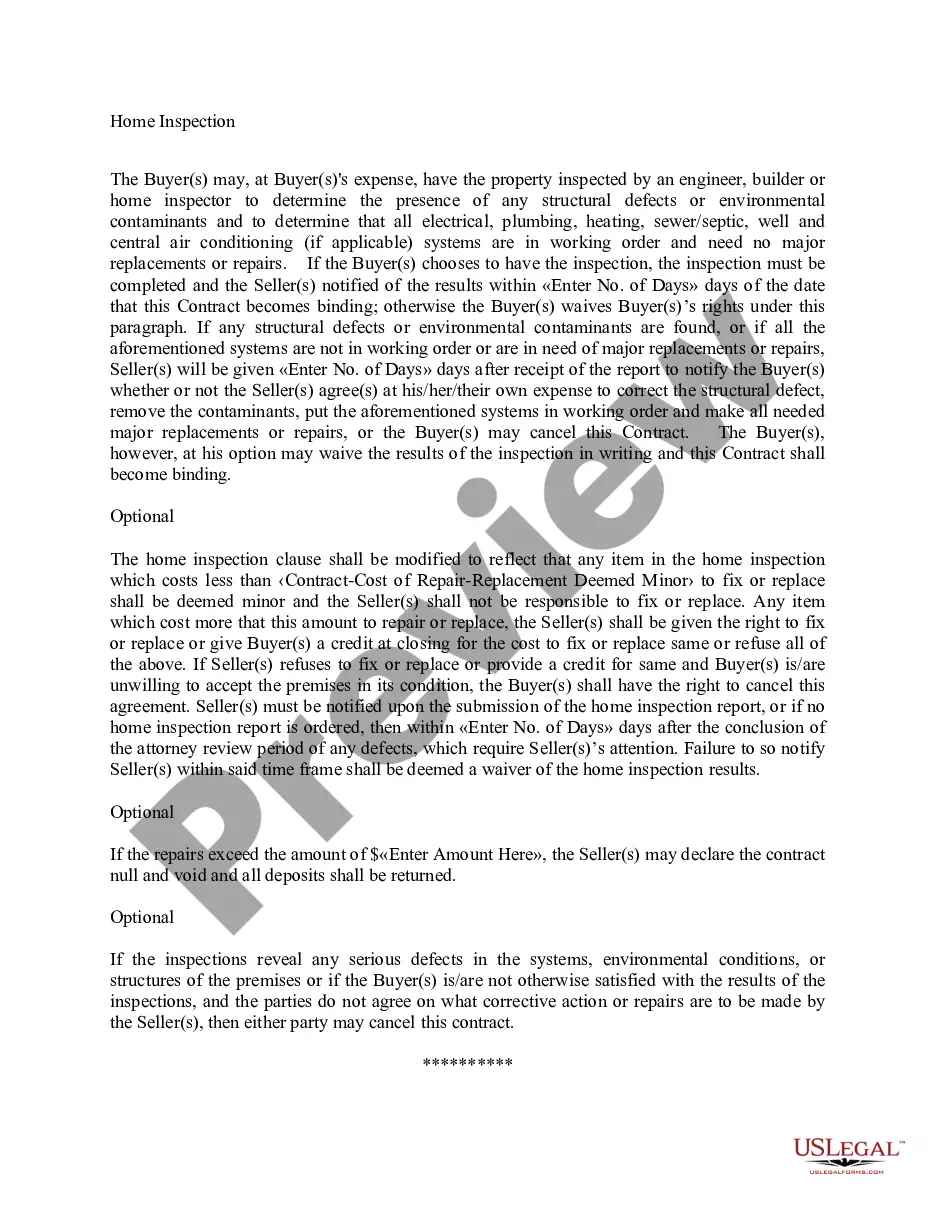
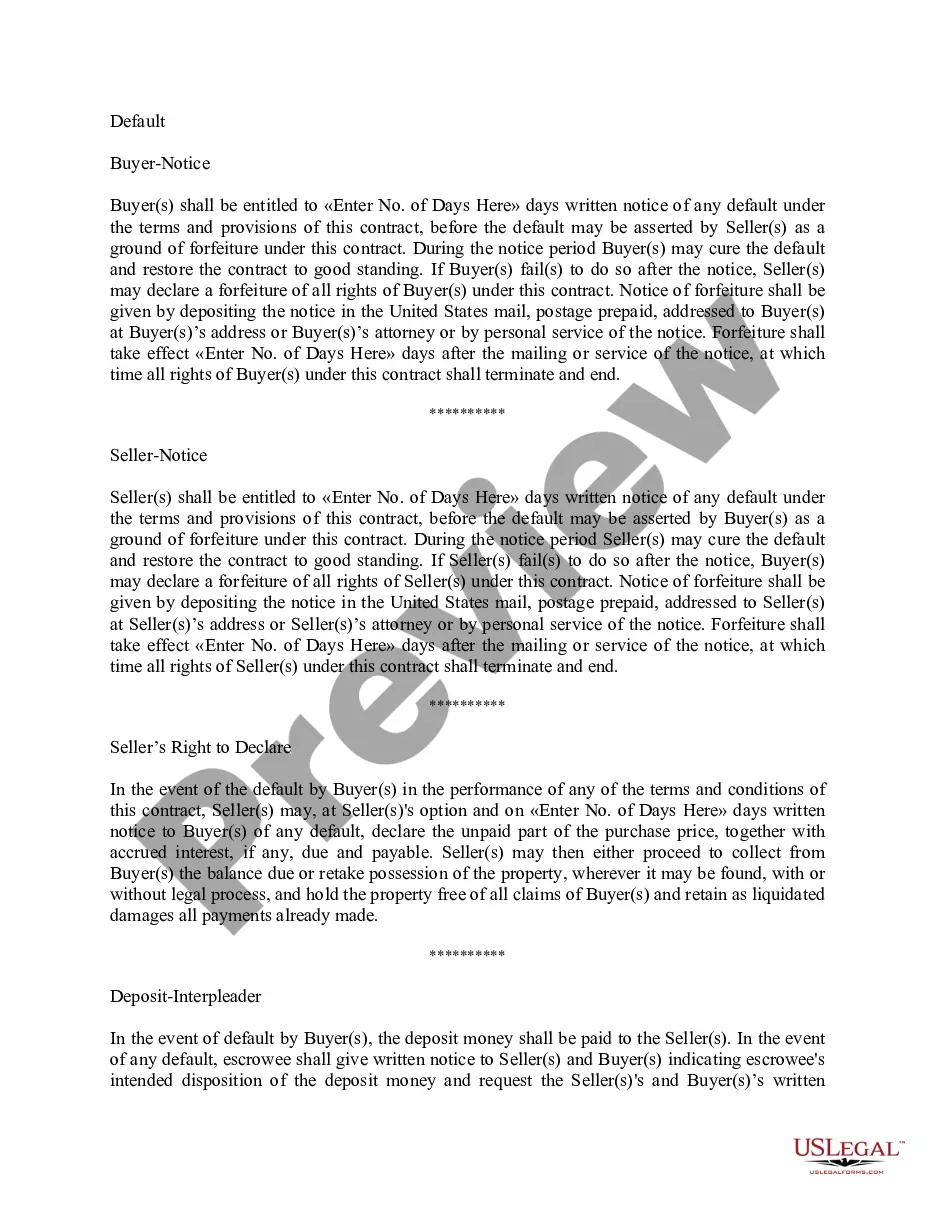
The FIRPTA Clauses: Contract for Real Property is a legal document that outlines the terms under which a contract for the sale of U.S. real property by a foreign person is enforceable. This form is specifically tailored to comply with the Foreign Investment in Real Property Tax Act (FIRPTA), which mandates tax withholding on certain transactions involving foreign sellers. Unlike standard real estate contracts, this form includes specific clauses regarding tax withholding and obligations of the transferor, ensuring compliance with federal law.
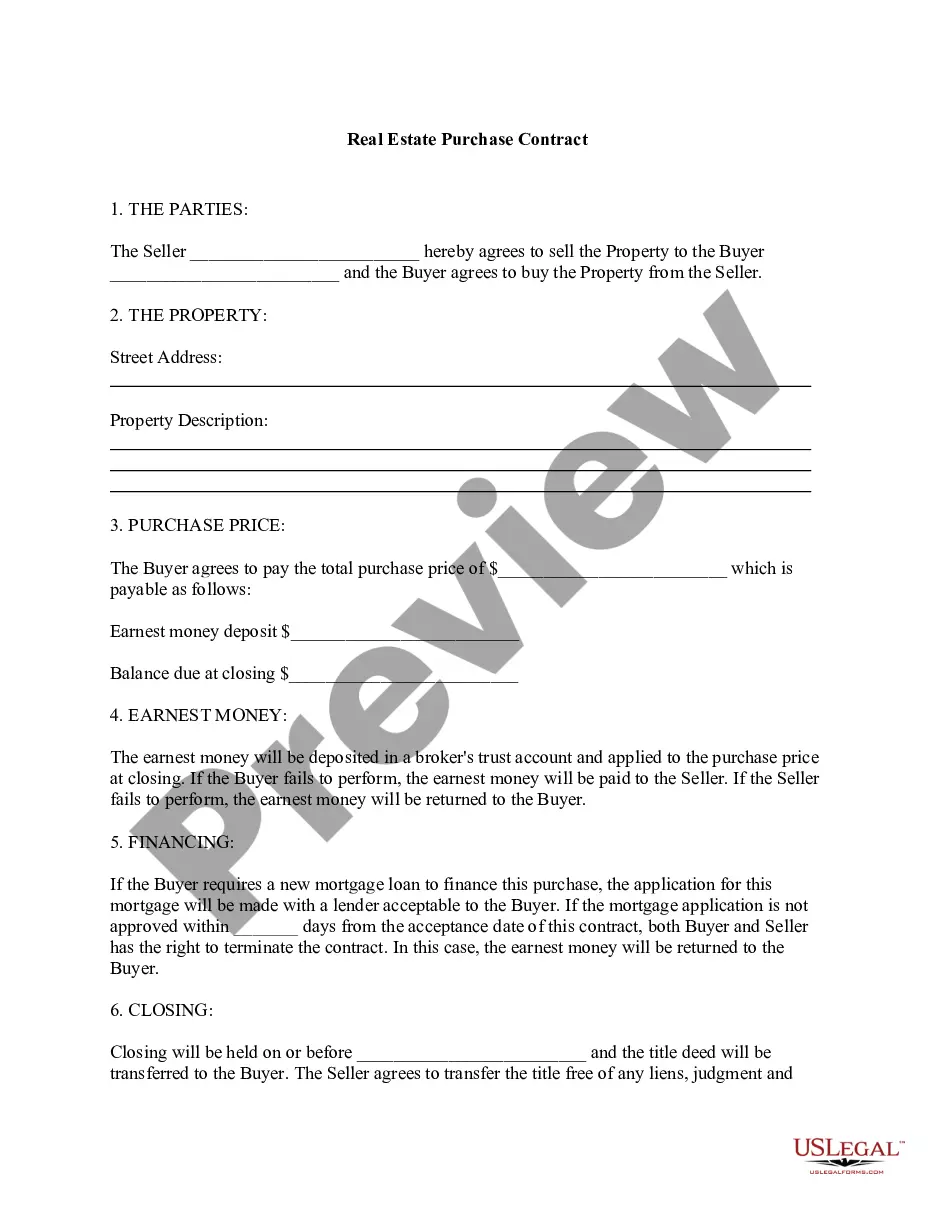
Key components of this form
- Identification of parties involved in the transaction.
- Description of the property being sold.
- Specific FIRPTA tax withholding obligations.
- Terms of the transferor's declarations regarding foreign status.
- Boilerplate clauses ensuring the enforceability of the contract.
When this form is needed
This form should be used whenever a foreign seller is involved in the conveyance of U.S. real property, as it assures compliance with FIRPTA requirements. Use it in transactions related to residential properties, commercial buildings, or land sales where the seller is a non-resident alien or foreign entity. It is crucial to use this form to avoid legal pitfalls and ensure proper tax withholding.
Who needs this form
The following individuals or entities should consider using the FIRPTA Clauses: Contract for Real Property:
- Foreign individuals or companies selling real estate in the U.S.
- Real estate agents working with foreign sellers.
- Buyers engaging in transactions with foreign sellers.
- Attorneys handling property sales involving non-resident sellers.
How to prepare this document
- Identify and enter the names of all parties involved in the transaction.
- Clearly specify the property details, including address and legal description.
- Confirm the transferor's foreign status and complete related declarations.
- Outline the FIRPTA tax withholding terms based on the selling price.
- Ensure all parties sign and date the form where indicated.
Notarization guidance
This form does not typically require notarization unless specified by local law. However, it is advisable to check local regulations regarding real estate transactions to ensure compliance.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
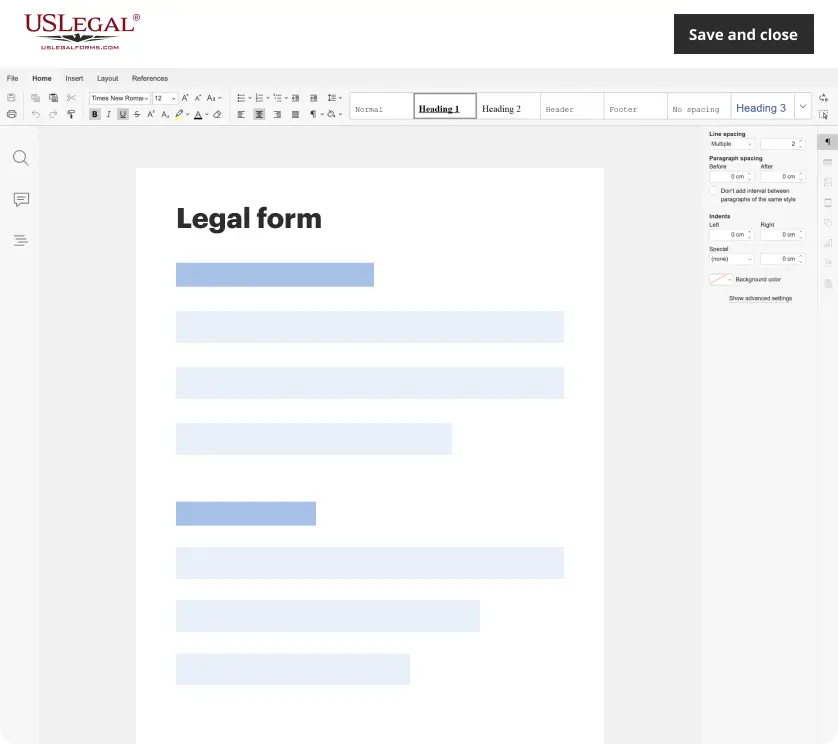
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Common mistakes to avoid
- Failing to accurately identify the foreign sellerâs status.
- Omitting detailed property descriptions.
- Overlooking the specific tax withholding calculations required by FIRPTA.
- Not obtaining signatures from all necessary parties.
Why complete this form online
- Convenience of downloading the form anytime and anywhere.
- Editability allows users to customize the document as per their needs.
- Access to templates reviewed by licensed attorneys enhances reliability.
Legal use & context
- The FIRPTA Clauses provide essential tax compliance for transactions involving foreign sellers.
- Failure to withhold the correct amount can lead to tax liabilities for buyers and sellers alike.
- Understanding the tax implications helps in minimizing legal risks during property transactions.
What to keep in mind
- Use this form when selling U.S. real estate as a foreign person.
- Ensure accurate completion to comply with FIRPTA tax obligations.
- Consult with legal professionals to navigate local requirements effectively.
Looking for another form?
Form popularity
FAQ
When a foreign transferor realizes zero financial gain on the transfer U.S. real property, you will be exempt from FIRPTA withholding taxes. While this is not necessarily common, it allows U.S. persons to avoid FIRPTA withholding taxes when purchasing a property from foreign persons or corporations.
If you plan to purchase property from a foreign person or corporation and want to avoid FIRPTA withholding taxes, you can apply for a withholding certificate from the IRS. The IRS only grants withholding certificates in certain situations, and applying for a certificate does not guarantee you will be granted one.
FIRPTA defines a foreign seller as a non-resident alien individual, a foreign corporation not treated as a domestic corporation, or a foreign partnership, trust or estate.
So long as the buyer has no actual knowledge that the seller is making a false statement regarding his or her status, or has not received any notice to the contrary, the buyer can rely on the FIRPTA affidavit signed at closing and will not be subject to any taxes or penalties.
FIRPTA is a tax law that imposes U.S. income tax on foreign persons selling U.S. real estate. Under FIRPTA, if you buy U.S. real estate from a foreign person, you may be required to withhold 10% of the amount realized from the sale. The amount realized is normally the purchase price.
The disposition of a U.S. real property interest by a foreign person (the transferor) is subject to the Foreign Investment in Real Property Tax Act of 1980 (FIRPTA) income tax withholding. FIRPTA authorized the United States to tax foreign persons on dispositions of U.S. real property interests.
Buyers (transferees), who are generally the withholding agents, must use Forms 8288 and 8288-A to report and pay to the IRS any tax withheld on the acquisition of U.S. real property interests from foreign persons.
FIRPTA is a tax law that imposes U.S. income tax on foreign persons selling U.S. real estate. Under FIRPTA, if you buy U.S. real estate from a foreign person, you may be required to withhold 10% of the amount realized from the sale. The amount realized is normally the purchase price.