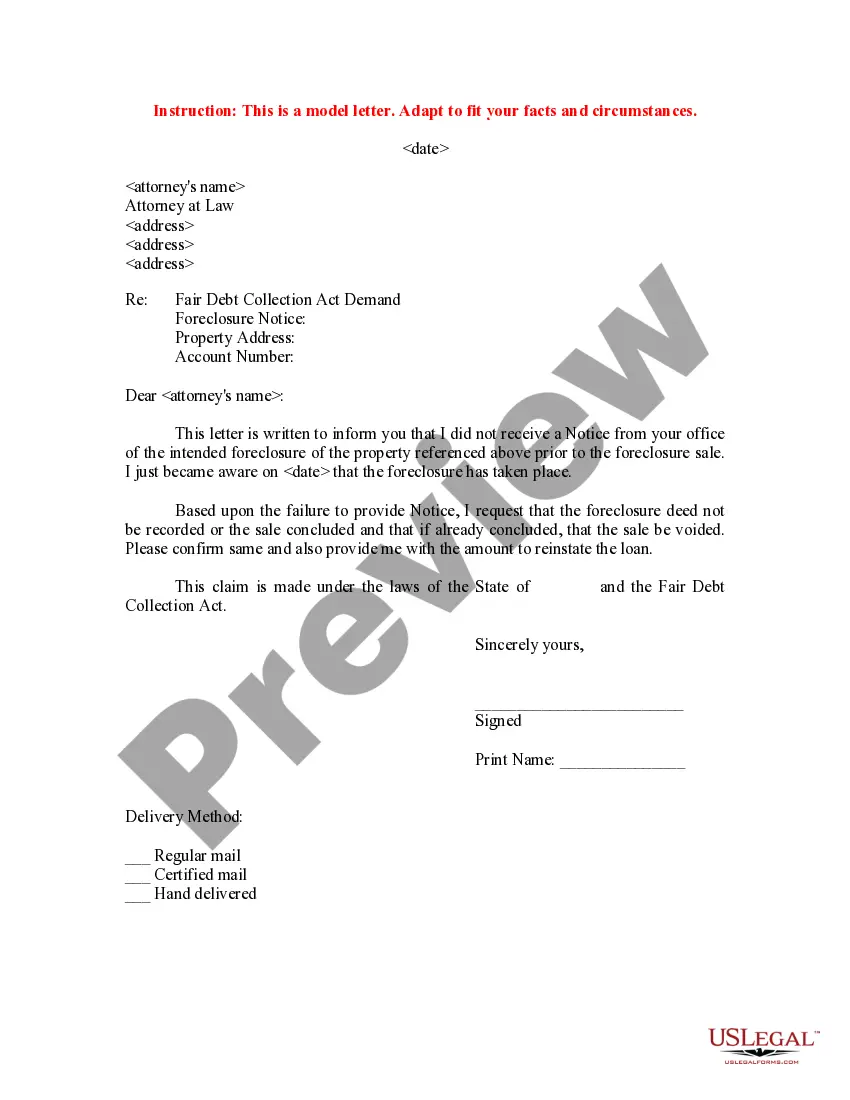
Hennepin Minnesota Sample Letter to Foreclosure Attorney - After Foreclosure - Did not Receive Notice
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
How to fill out Sample Letter To Foreclosure Attorney - After Foreclosure - Did Not Receive Notice?
Drafting documents, such as the Hennepin Sample Letter to Foreclosure Lawyer - Post Foreclosure - Did not Obtain Notification, to address your legal concerns is a challenging and lengthy undertaking.
Numerous scenarios demand the involvement of an attorney, which additionally renders this endeavor rather costly.
Nevertheless, you can take charge of your legal issues and manage them independently.
The onboarding process for new users is equally user-friendly! Here’s what you should accomplish prior to acquiring the Hennepin Sample Letter to Foreclosure Attorney - Post Foreclosure - Did not Obtain Notification: Ensure your template is tailored to your state/county since guidelines for drafting legal documents can differ from one state to another.
- US Legal Forms is here to assist.
- Our platform offers over 85,000 legal templates designed for diverse scenarios and life events.
- We ensure that each document aligns with the regulations of every state, so you don’t have to worry about possible compliance issues.
- If you are already familiar with our site and hold a subscription with US, you understand how straightforward it is to obtain the Hennepin Sample Letter to Foreclosure Lawyer - Post Foreclosure - Did not Obtain Notification form.
- Just Log In to your profile, download the document, and customize it to fit your needs.
- Lost your document? No stress. You can retrieve it in the My documents section within your account, whether on a desktop or mobile device.
Form popularity
FAQ
The Length of the Florida Foreclosure Process Timeline can vary. Generally, it lasts between 8 to 14 months. On the other hand, if you hire a Foreclosure Defense Attorney, it can take longer. If you are a in Foreclosure, contact the Law Office of Brian P.
A judicial foreclosure requires the lienholder to file a civil lawsuit against the homeowner. They must obtain a judgment from the court before they are allowed to sell the property. This procedure is rare in Texas. See Rule 309 of the Texas Rules of Civil Procedure for the court rule governing judicial foreclosures.
The sale is followed by a redemption period, which is usually six months. Accordingly, assuming there is no bankruptcy filing, a typical foreclosure by advertisement (including the typical six month redemption period) generally takes around eight to nine months.
In general, mortgage companies start foreclosure processes about 3-6 months after the first missed mortgage payment. Late fees are charged after 10-15 days, however, most mortgage companies recognize that homeowners may be facing short-term financial hardships.
The process may take as little as 41 days, depending on the timing between mailing the required notices and the actual foreclosure date. All foreclosure sales in Texas occur on the first Tuesday of the month between 10 a.m. and 4 p.m. The commissioner's court designates the loca- tion.
A demand letter simply restates the terms of the loan, and demands that the borrower rectify their accounts immediately. More common for a non-judicial foreclosure might be a breach letter, which is required before issuing an NOD.
The Most Commonly Used Foreclosure Procedure In the State A foreclosure can be either: judicial (the foreclosing party files a lawsuit, and the case goes through the court system) or. nonjudicial (the foreclosing party follows a set of state-specific, out-of-court procedural steps to foreclose).
Under Texas law, a lender has to use a quasi-judicial process to foreclose a home equity loan. In this process, the lender must get a court order approving the foreclosure before conducting a nonjudicial foreclosure. Also, Texas law doesn't allow deficiency judgments following the foreclosure of a home equity loan.
Most loans from a bank must be 120 days delinquent before any foreclosure activity starts. However, smaller lenders can sometimes start foreclosure even if you are only 1 day late. The lender is only required to send you two notices before a foreclosure sale.