Assumption of Existing Mortgage Addendum
About this form
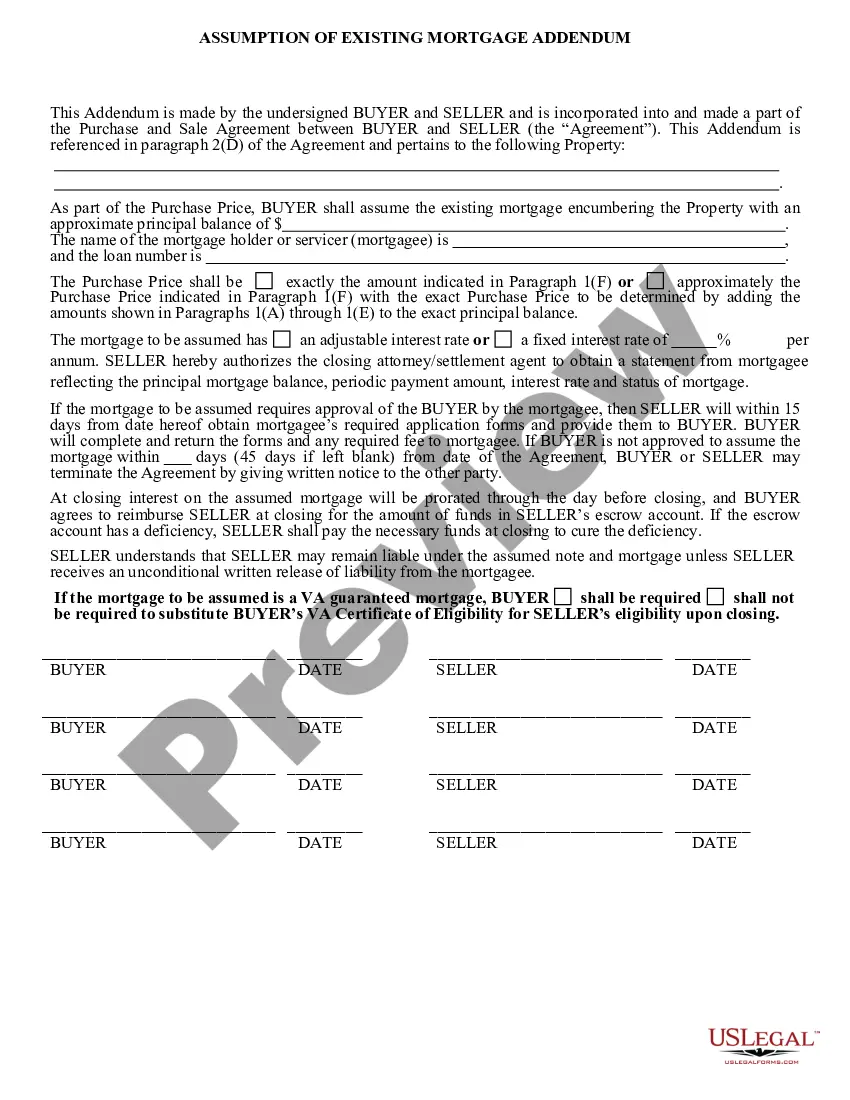
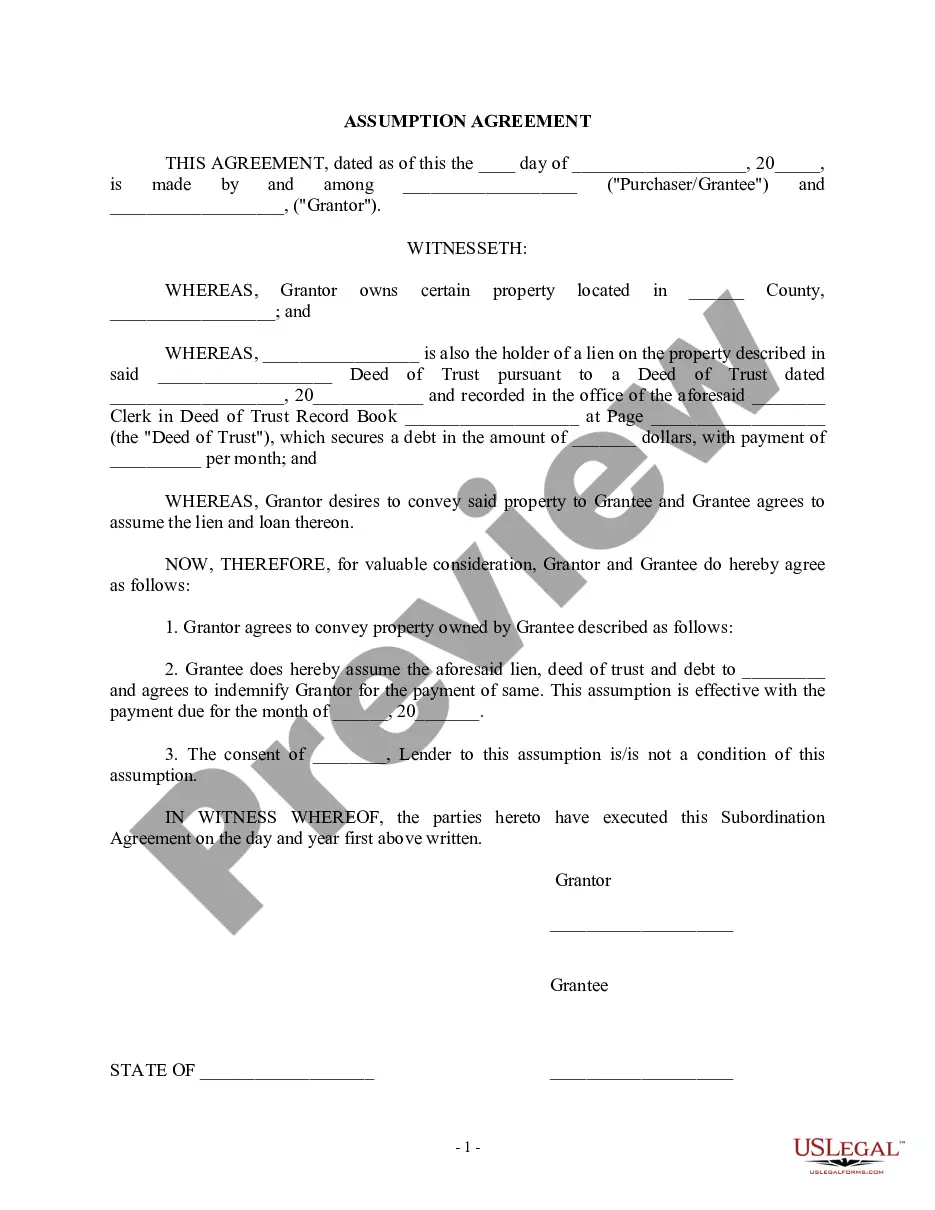
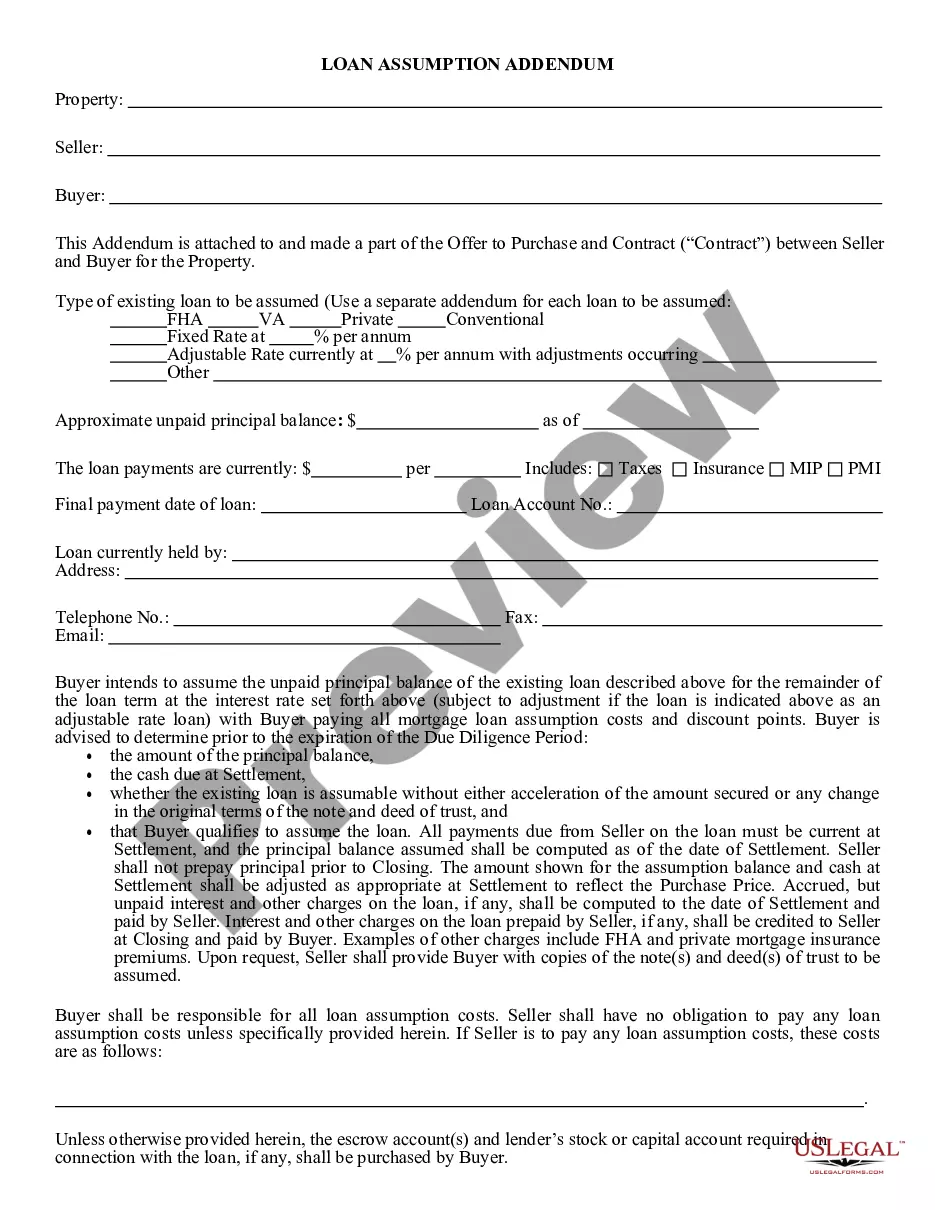
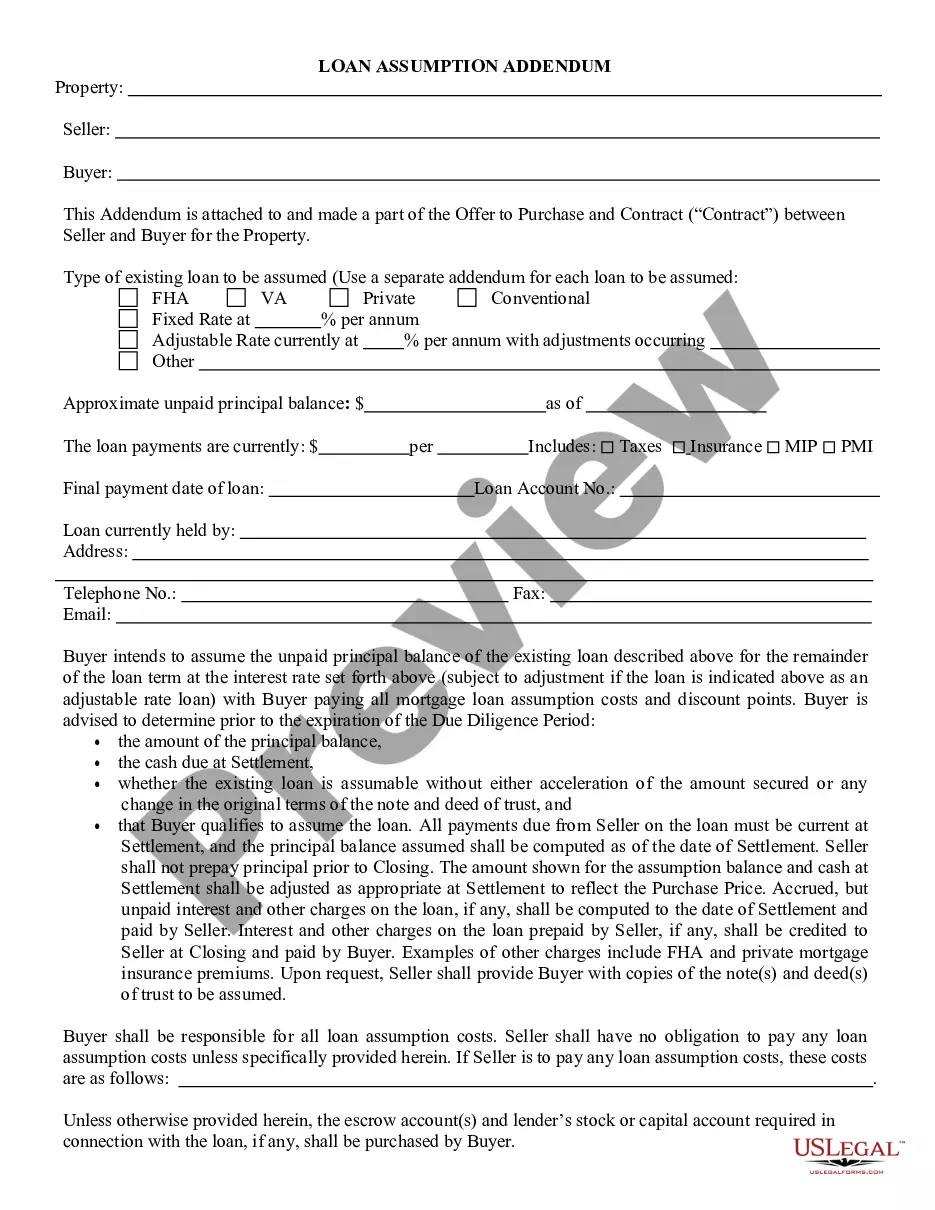
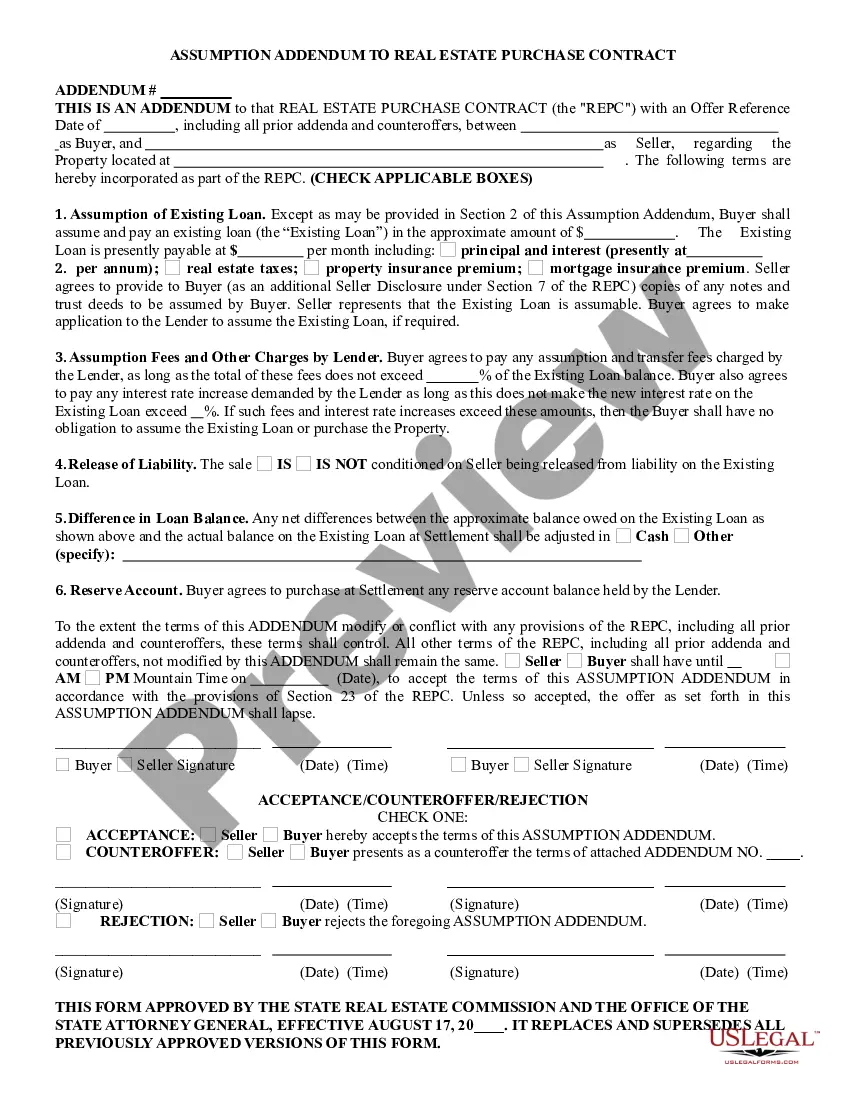
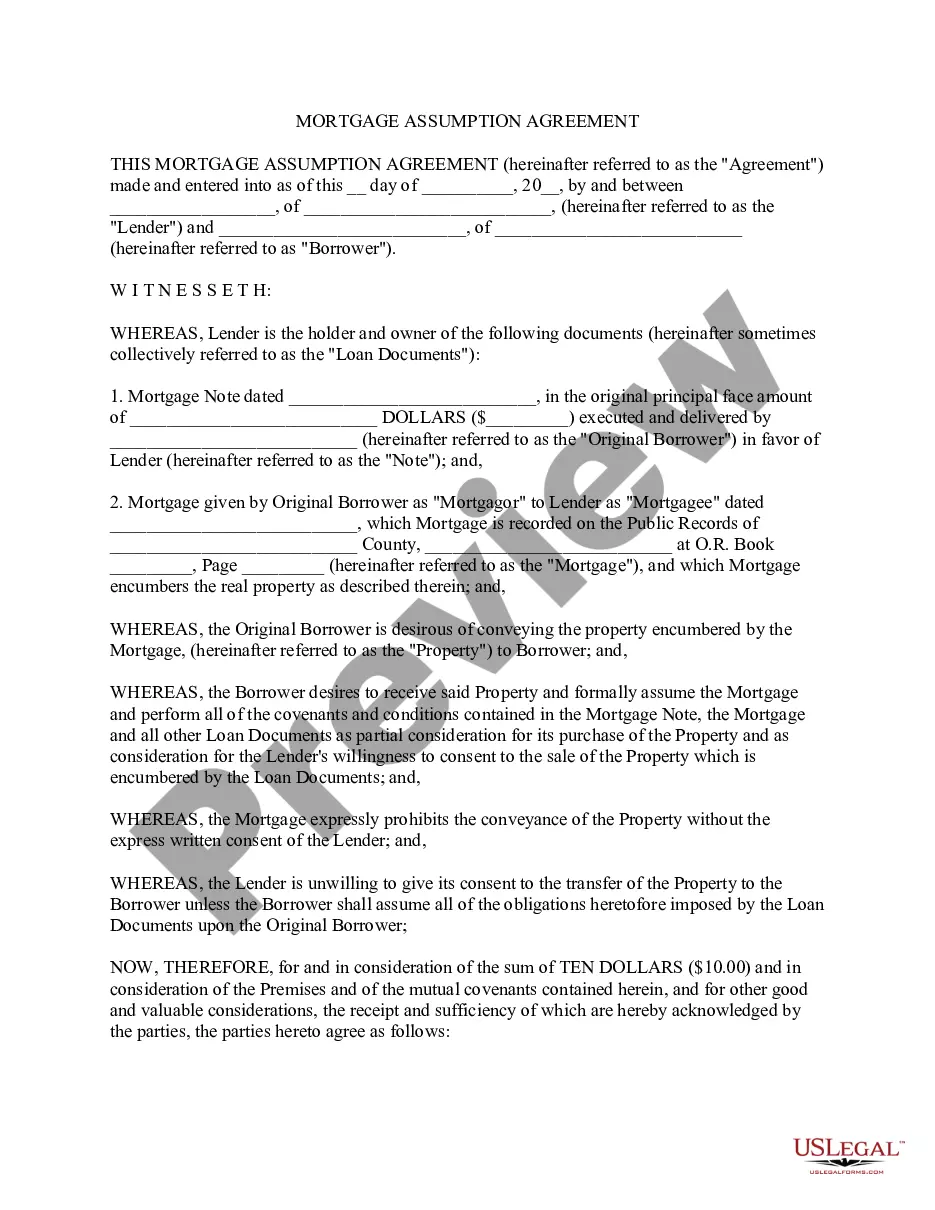
The Assumption of Existing Mortgage Addendum is a legal document that allows the buyer of a property to take over the seller's existing mortgage. This addendum is part of the Purchase and Sale Agreement and serves to assign the responsibilities of the mortgage from the seller to the buyer. Unlike a standard transfer of property, this form specifically addresses the mortgage obligation, which can affect both parties' liabilities during the home buying process.
What’s included in this form
- Identification of the property involved in the mortgage transfer.
- Details about the existing mortgage, including principal balance and mortgagee information.
- Indication of whether the mortgage has a fixed or adjustable interest rate.
- Approval process requirements for the buyer by the mortgagee.
- Provisions for the proration of interest at closing.
- Notices regarding continued liability for the seller if the mortgage is assumed.
When to use this document
This addendum is necessary when a buyer intends to assume responsibility for an existing mortgage as part of the real estate transaction. It is commonly used in situations where the seller is unable to pay off their mortgage at the time of sale, or when assuming the mortgage presents a financial advantage to the buyer. It is also useful if the mortgage terms are favorable compared to current market rates.
Who should use this form
- Home buyers looking to assume an existing mortgage from the seller.
- Sellers who want to transfer their mortgage obligations to the buyer.
- Real estate agents assisting clients in transactions involving the assumption of mortgages.
- Attorneys involved in real estate transactions needing a formal mortgage assumption agreement.
Completing this form step by step
- Identify the parties involved: the buyer and seller.
- Specify the property address and details relevant to the mortgage.
- Enter the existing mortgage principal balance and mortgage details.
- Determine and record whether the mortgage has a fixed or adjustable interest rate.
- Both parties should sign and date the addendum to finalize the agreement.
Notarization guidance
This form does not typically require notarization unless specified by local law. However, it is recommended to verify the requirements in your jurisdiction to ensure compliance.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Common mistakes to avoid
- Failing to accurately enter the mortgage holder's name and loan number.
- Leaving out required signatures from one or both parties.
- Not checking if the mortgage requires approval from the lender before assuming.
- Ignoring potential liabilities that might remain for the seller after the assumption.
Advantages of online completion
- Convenience of accessing and downloading the form at any time.
- Editable form templates that allow customization to fit your specific needs.
- Reliability of forms drafted by licensed attorneys to ensure legal accuracy.
Looking for another form?
Form popularity
FAQ
Assumable refers to when one party takes over the obligation of another. In terms of an assumable mortgage, the buyer assumes the existing mortgage of the seller. When the mortgage is assumed, the seller is often no longer responsible for the debt.
An assumable mortgage allows a home buyer to not just move into the seller's former house, but to step into the seller's loan, too. This means that the remaining balance, repayment schedule and rate will be taken over by the new owner.
The disadvantages of assumable mortgage are as follows: Assuming a mortgage may require the buyer to pay a significant amount as a down payment.One of the significant disadvantages of assumable mortgages is that there are strict income and credit requirements for this loan type.
An assumable mortgage allows the buyer to purchase a home by taking over the seller's mortgage loan. One reason buyers decide to buy a home with an assumable mortgage is to take advantage of financing with a lower interest rate if rates have risen since the seller originally purchased the home.
THIS IS AN ADDENDUM to that REAL ESTATE PURCHASE CONTRACT (the "REPC") with an Offer Reference Date. of. , including all prior addenda and counteroffers, between. as Buyer, and. as Seller, regarding the Property.
How do assumable mortgages work? When you assume a mortgage, the current borrower signs the balance of their loan over to you, and you become responsible for the remaining payments. That means the mortgage will have the same terms the previous homeowner had, including the same interest rate and monthly payments.
An assumable mortgage allows the buyer to purchase a home by taking over the seller's mortgage loan. One reason buyers decide to buy a home with an assumable mortgage is to take advantage of financing with a lower interest rate if rates have risen since the seller originally purchased the home.
Assumable refers to when one party takes over the obligation of another. In terms of an assumable mortgage, the buyer assumes the existing mortgage of the seller. When the mortgage is assumed, the seller is often no longer responsible for the debt.