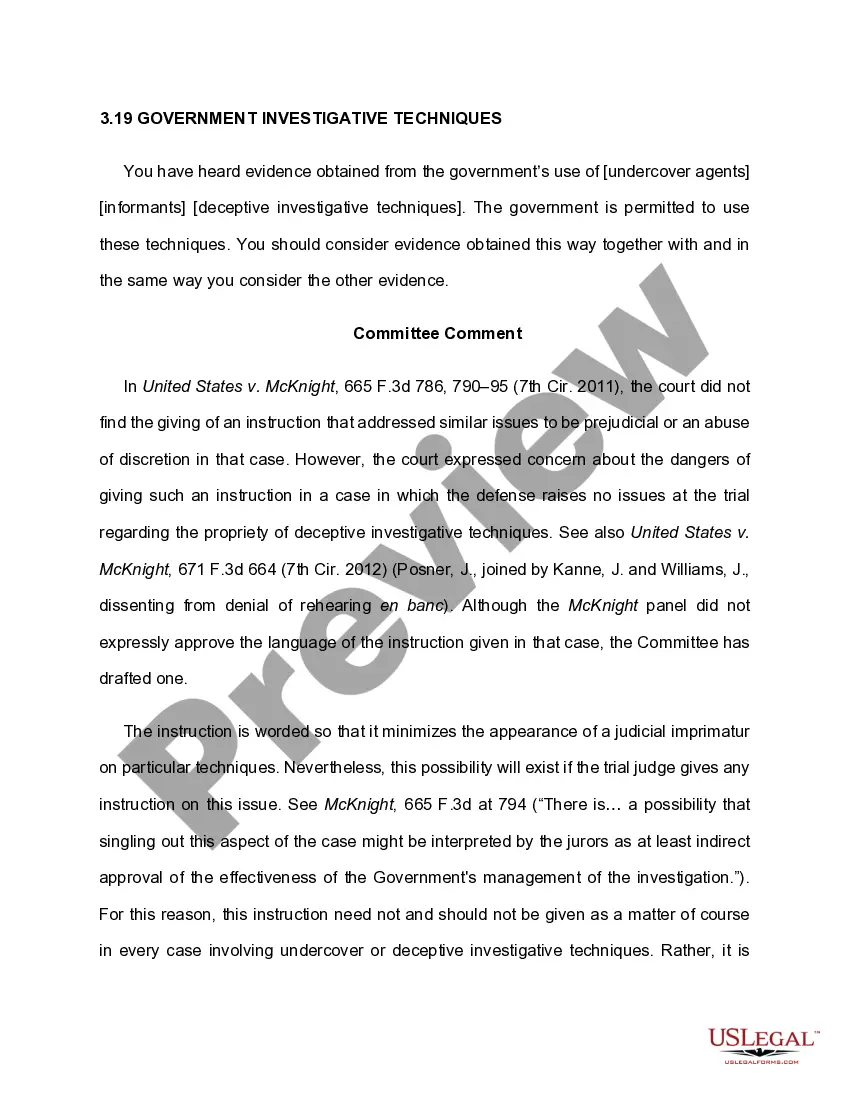
3.19 GOVERNMENT INVESTIGATIVE TECHNIQUES
What is this form?
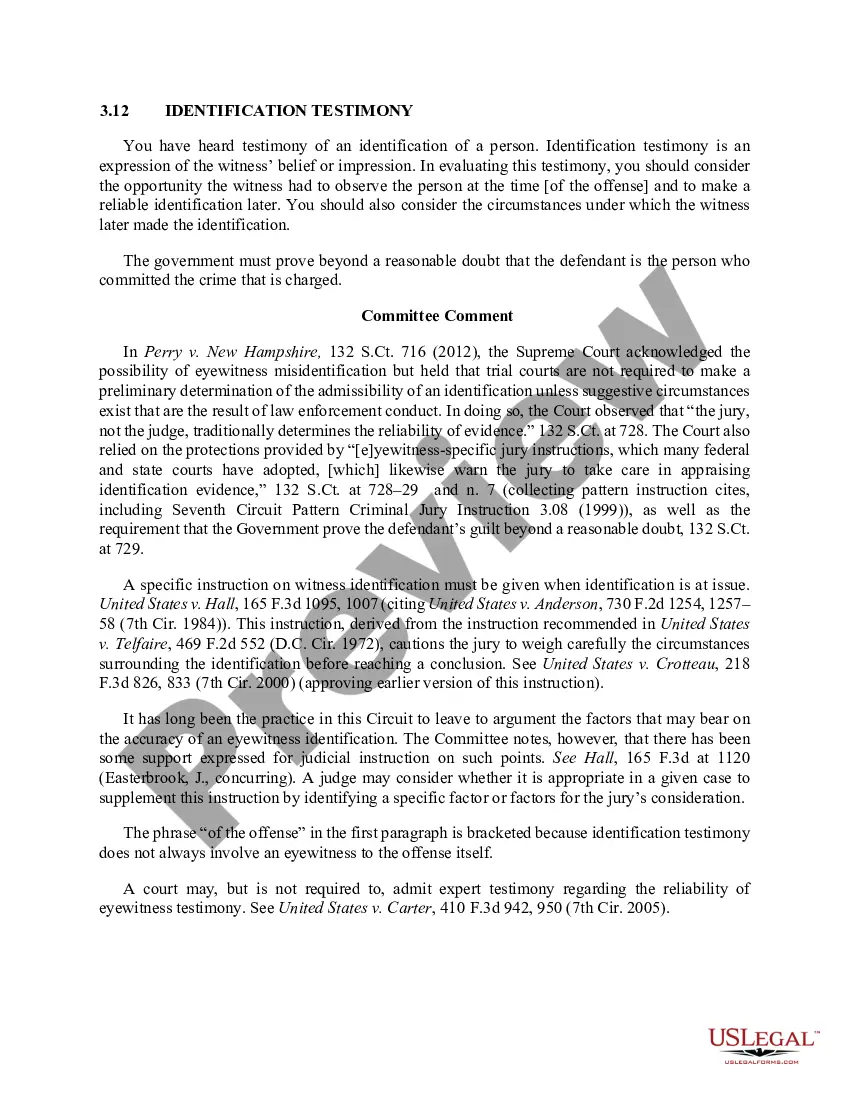
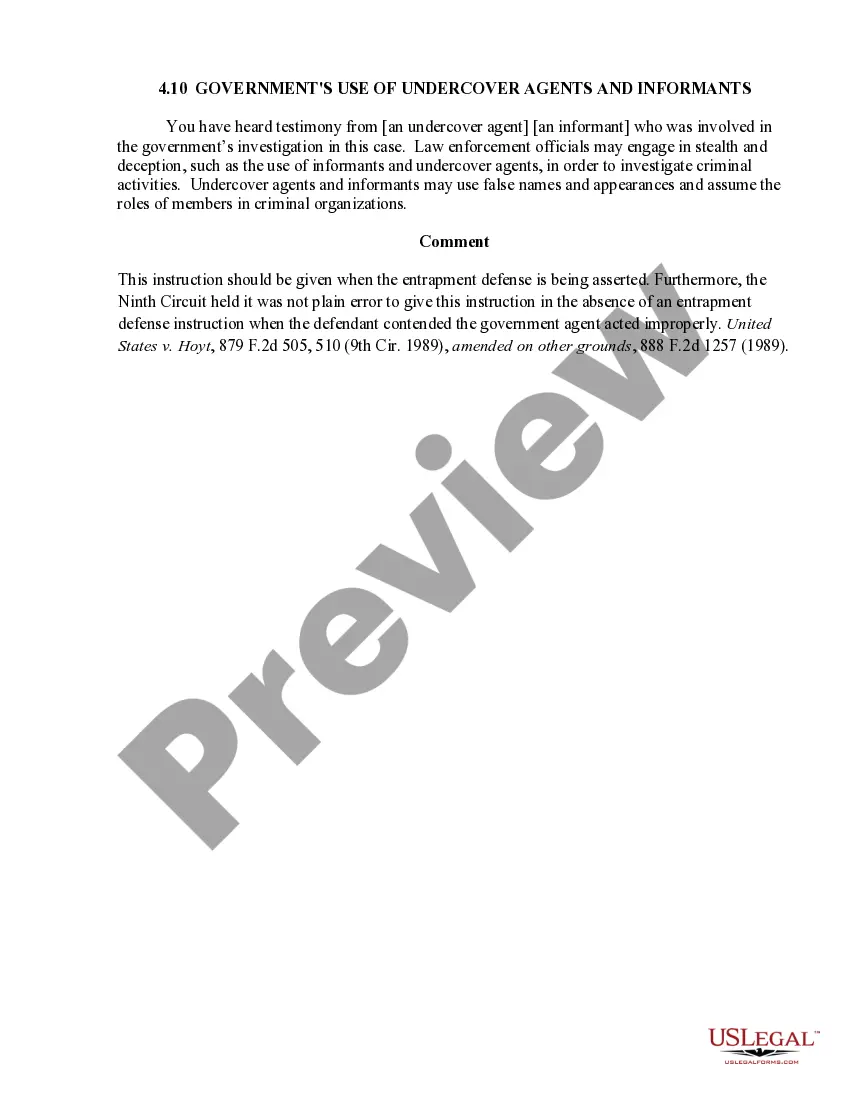
The 3.19 Government Investigative Techniques form provides official jury instruction related to evidence obtained through government methods, such as undercover agents and informants. This form is specifically designed for cases where the legality of these investigative techniques might come into question. Unlike other jury instructions, this form helps jurors understand how to evaluate evidence that was collected through potentially deceptive methods while ensuring that they do not view such techniques as inherently problematic without proper context.
Key components of this form
- Guidance on considering evidence obtained from undercover agents and informants.
- Clarification regarding the permissibility of using deceptive investigative techniques.
- Reference to relevant case law, highlighting implications of these instructions.
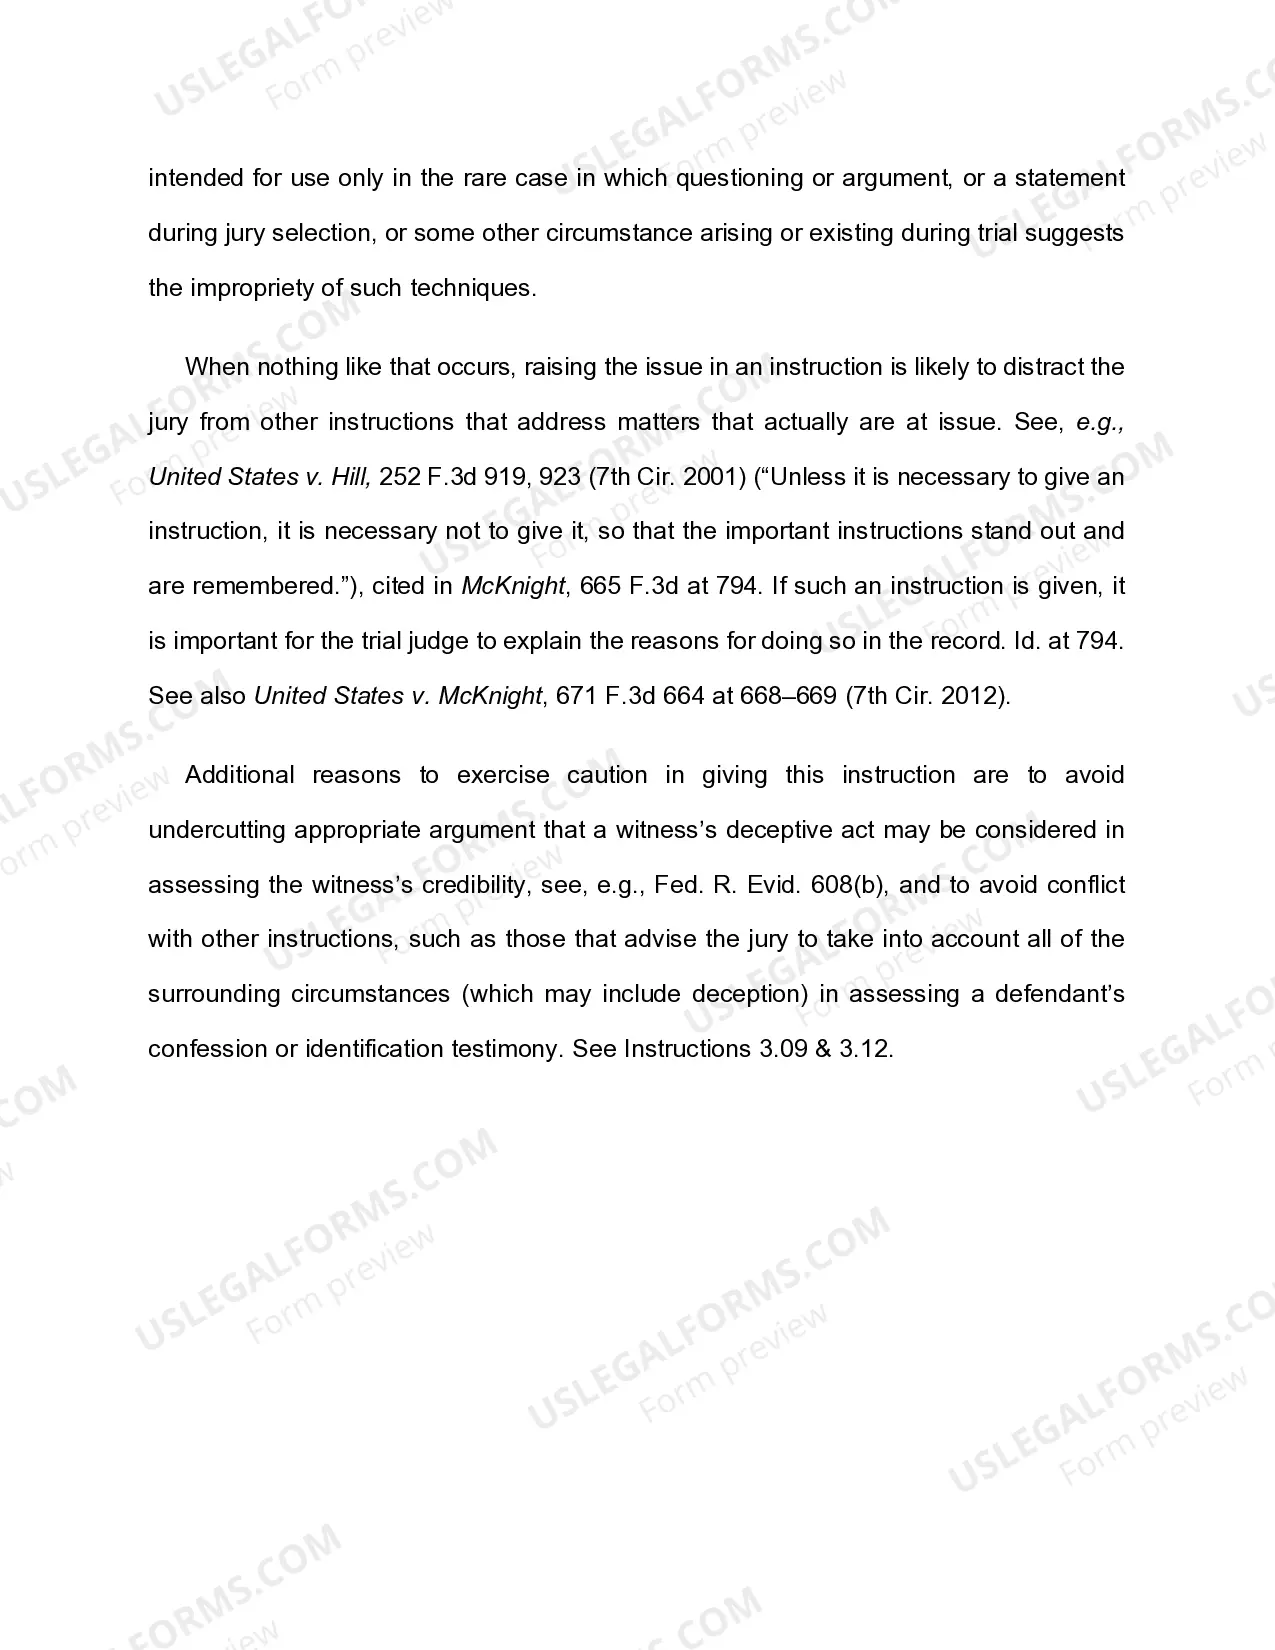
- Recommendations on when this instruction should be delivered to jurors during a trial.
- Advice on avoiding distractions from critical jury instructions in the trial.
When this form is needed
This form should be used in jury trials where evidence has been collected through government investigative techniques that may include undercover operations or informants. It is particularly relevant in cases where there are arguments raised about the legality or appropriateness of these methods. If the defense questions the collectiveness of such evidence during the proceedings, this form instructs the jury on how to assess it appropriately.
Who this form is for
- Judges overseeing criminal trials involving government investigations.
- Attorneys representing defendants or the government in cases involving undercover operations.
- Jury coordinators who need to ensure jurors receive relevant instructions.
Completing this form step by step
- Review the specific case details to determine relevance to investigative techniques.
- Incorporate this instruction into the jury instructions as needed depending on case arguments.
- Ensure that all jurors understand the implications of using evidence obtained through these methods.
- Document any rationale for delivering or omitting this instruction in the trial record.
- Clarify with the jury how they should weigh this evidence against other evidence presented during the trial.
Notarization requirements for this form
Notarization is generally not required for this form. However, certain states or situations might demand it. You can complete notarization online through US Legal Forms, powered by Notarize, using a verified video call available anytime.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Common mistakes
- Using the instruction in every case without considering the specific context of the investigation.
- Failing to document the reasons for including or excluding the instruction in the trial record.
- Overemphasizing the legitimacy of investigative techniques to jurors, which could bias their judgment.
Benefits of using this form online
- Immediate access to an up-to-date legal instruction template.
- Easily downloadable and editable to fit specific case needs.
- Prepared by licensed attorneys, ensuring reliability and compliance with legal standards.
Legal use & context
- This instruction addresses how jurors should handle evidence obtained through potentially controversial government practices.
- Helps to prevent any bias from jurors regarding the perceived legitimacy of evidence collection methods.
- Specific case law provides context that aids in the impartiality of the jury's decision-making.
Looking for another form?
Form popularity
FAQ
All public companies (registrants) must include management's report on internal control over financial reporting in their Form 10-K annual report filed with the SEC, per SOX 404(a).
Internal control is a process, effected by an entity's board of directors, management and other personnel, designed to provide reasonable assurance: That information is reliable, accurate and timely. Of compliance with applicable laws, regulations, contracts, policies and procedures.
The auditor should form an opinion on the effectiveness of internal control over financial reporting by evaluating evidence obtained from all sources, including the auditor's testing of controls, misstatements detected during the financial statement audit, and any identified control deficiencies.
What is GAGAS? Generally Accepted Government Auditing Standards (GAGAS) , also known as the Yellow Book, are the guidelines for audits created by the Comptroller General and the audit agency of the United States Congress, the Government Accountability Office.
Reporting on internal control to meet the requirements of Government Auditing Standards differs from reporting under other generally accepted auditing standards in that Government Auditing Standards requires a: Report describing the scope of the auditor's testing of compliance and of internal control.
These standards are established by the Comptroller General of the United States in conjunction with the Government Accountability Office (GAO), and are found in its publication, Government Auditing Standards.
In short, GAGAS are the standards that ensure that audit reports are unbiased and can be trusted to be truthful and accurate. It means that OIG audits conform to audit standards accepted by governments around the country.
Independence. 3.12 Auditors and audit organizations have a responsibility to maintain independence, so that opinions, conclusions, judgments, and recommendations will be impartial and will be viewed as impartial by knowledgeable third parties.