Request for Loan Modification RMA Under Home Affordable Modification Program HAMP
Overview of this form
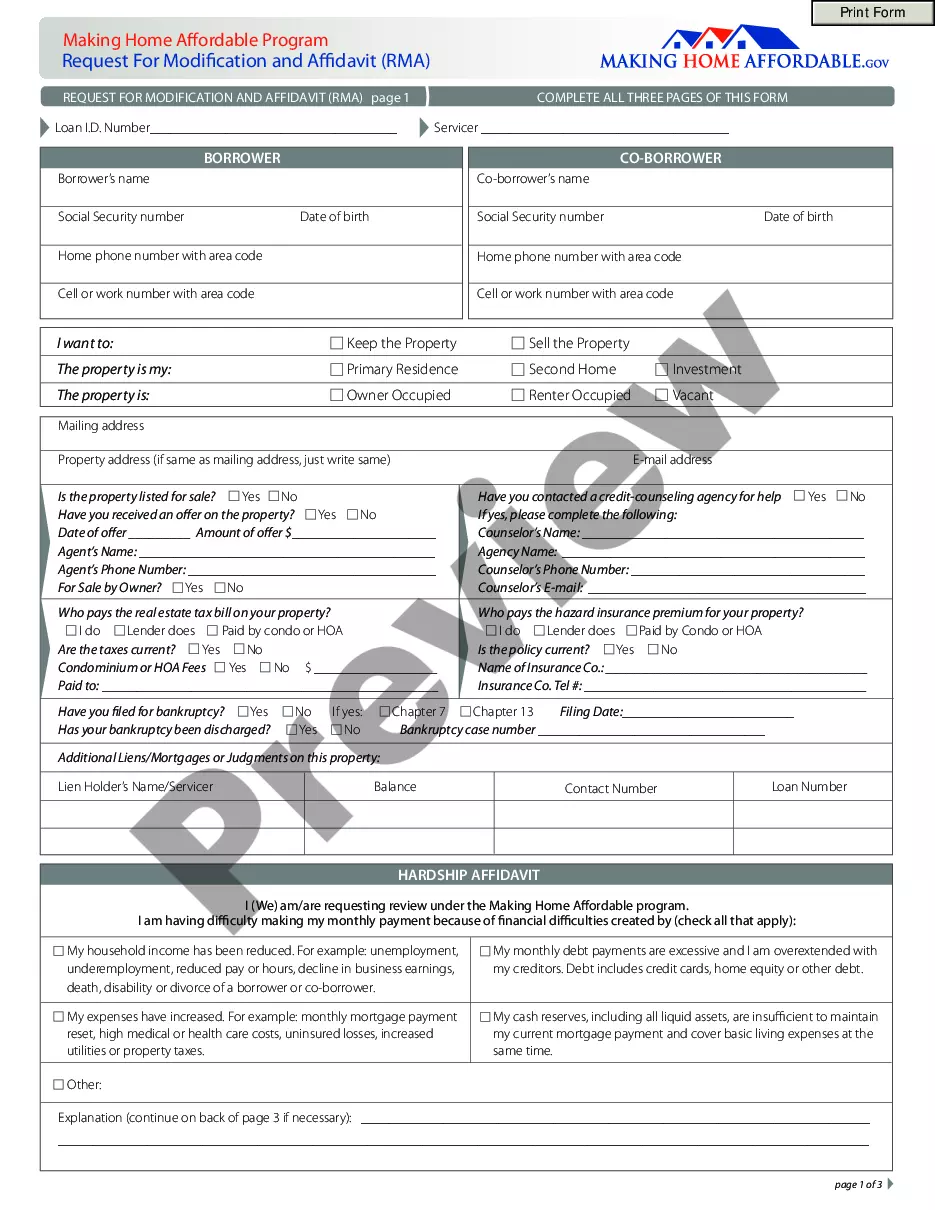
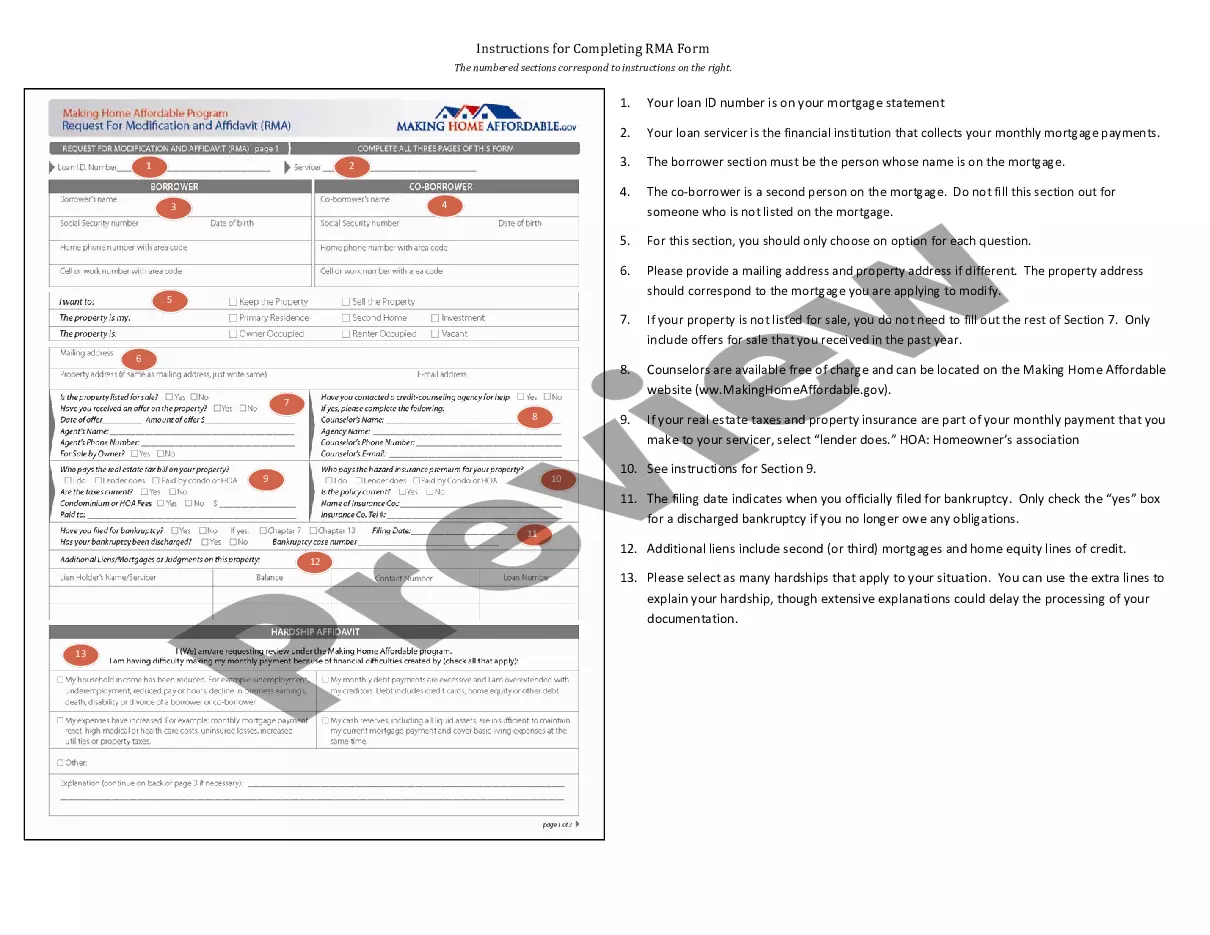
This Request for Loan Modification RMA Under Home Affordable Modification Program (HAMP) is a crucial document for homeowners seeking to modify their mortgage loans. The form allows borrowers to provide necessary information about their home and financial situation to their mortgage servicer. This form is specifically tailored for use under the HAMP, making it distinct from other loan modification requests as it adheres to specific federal guidelines designed to assist struggling homeowners.
Main sections of this form
- Identification of property type (primary residence, second home, investment)
- Borrower and co-borrower information including personal contact details
- Disclosure of current financial hardship and reasons for requesting modification
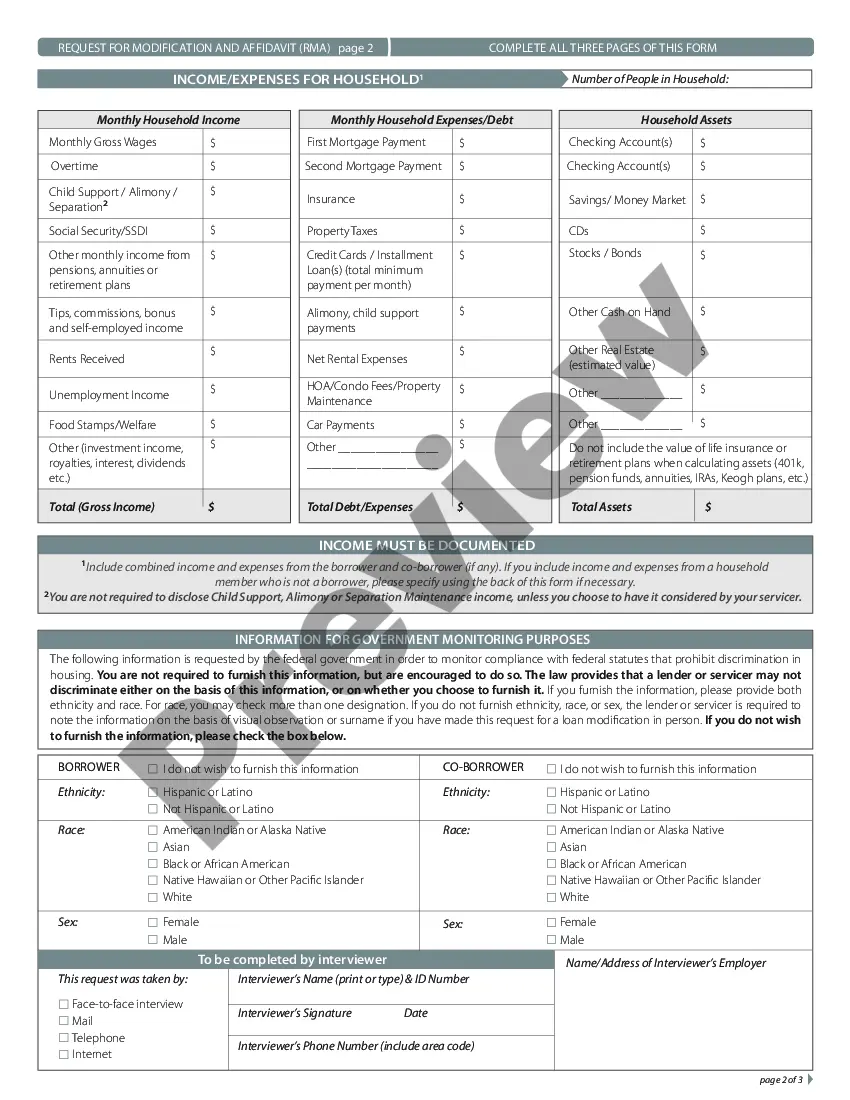
- Income and expenses overview to assess the borrowerâs financial situation
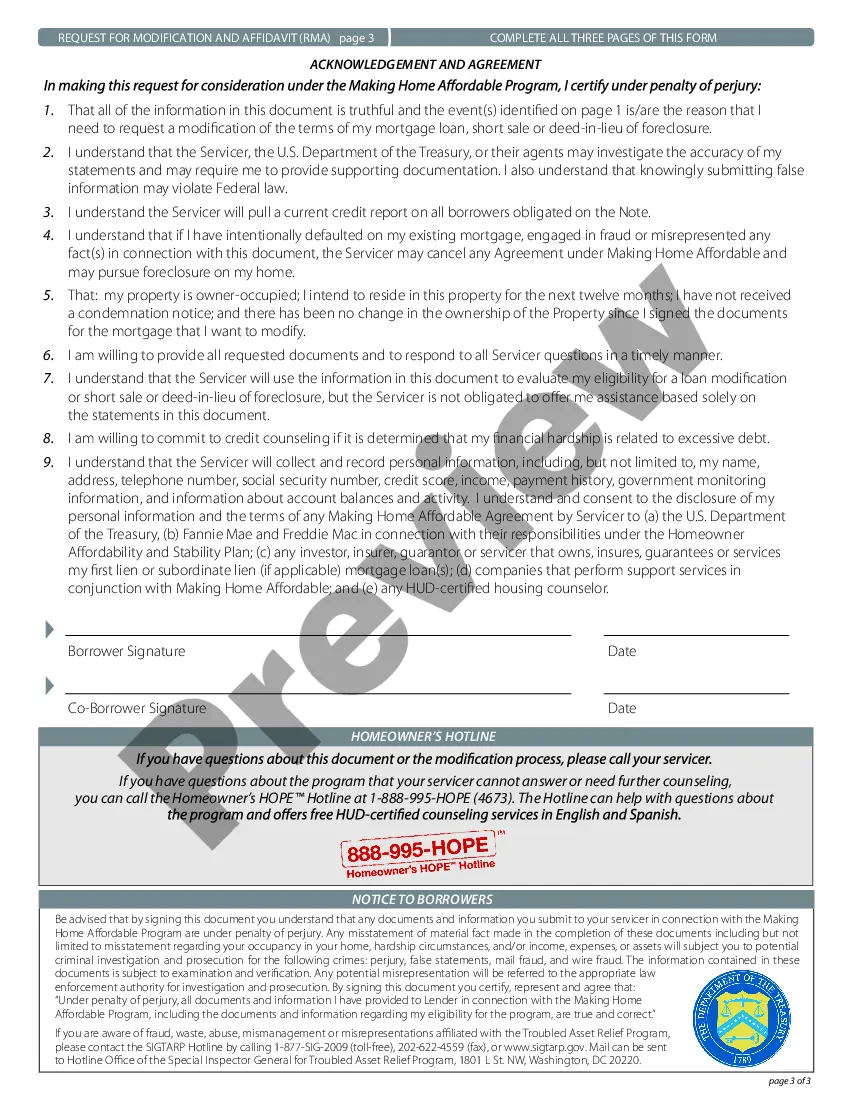
- Signature and agreement section confirming the truthfulness of provided information
When to use this form
This form should be used when homeowners are experiencing financial difficulties that affect their ability to make monthly mortgage payments and are interested in participating in the HAMP program. Scenarios for using this form include job loss, reduced income, increased living expenses, or any situation leading to financial strain that requires assistance in modifying existing mortgage terms.
Who should use this form
- Homeowners who hold a mortgage that they are struggling to pay
- Individuals seeking to reduce their monthly payment through modification
- Borrowers whose financial circumstances have changed significantly
- Those considering keeping their home and maintaining ownership
Completing this form step by step
- Identify the property type and occupancy status
- Provide accurate personal information for all borrowers
- Detail the financial hardship and check all applicable reasons
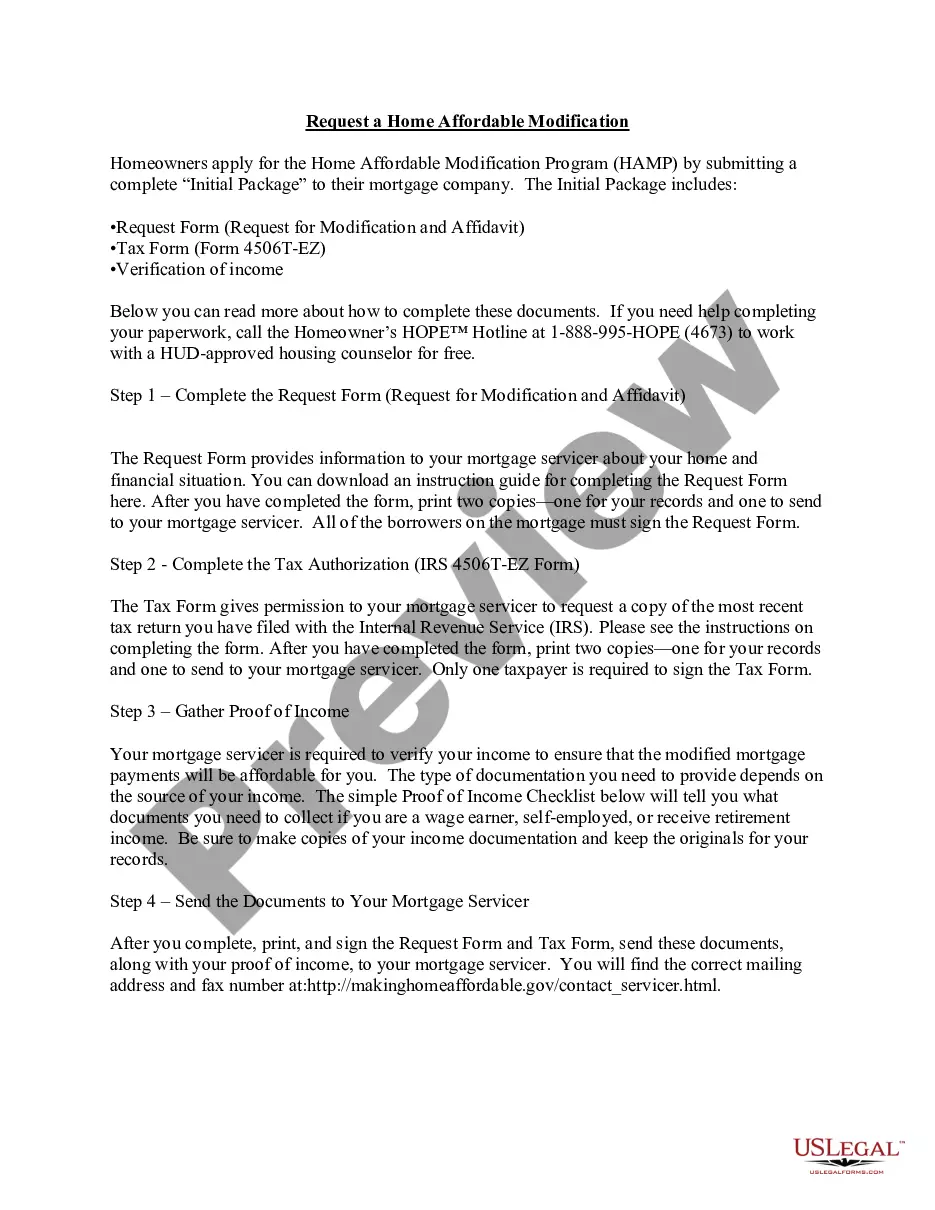
- List monthly income and expenses clearly, including relevant supporting documentation
- Sign the form, ensuring all information is truthful and accurate
Is notarization required?
This form does not typically require notarization unless specified by local law. Always verify specific requirements in your state to ensure compliance with local regulations.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Common mistakes to avoid
- Failing to provide complete and accurate financial information
- Not signing the form or having all borrowers sign it
- Omitting required supporting documentation
- Incorrectly stating the property occupancy status
Benefits of completing this form online
- Convenience of filling out the form at your own pace
- Availability of guidance and suggestions while completing the form
- Ability to easily edit and update information before submission
- Secure and organized digital storage of important documents
Looking for another form?
Form popularity
FAQ
Homeowners go through the process of a loan modification to stay afloat in times that their mortgage payments are becoming too difficult to maintain. It is possible to refinance the loan again in the future, but do not expect it to come without challenges.
All modifications be in writing. All parties involved sign the modification. In appropriate cases, the modification should be recorded. The title company and attorneys be involved early in the process to properly structure the modification to protect the lender's interest at the lowest cost.
A loan modification is a change to the original terms of your mortgage loan. Unlike a refinance, a loan modification doesn't pay off your current mortgage and replace it with a new one.Loan term changes: If you're having trouble making your monthly payments, your lender may modify your loan and extend your term.
An income and expenses financial worksheet. tax returns (often, two years' worth) recent pay stubs or a profit and loss statement. proof of any other income (including alimony, child support, Social Security, disability, etc.) recent bank statements, and.
HAMP borrowers can also refinance if there is a clear benefit. "A borrower who has applied for or received a loan modification is eligible to refinance under DU Refi Plus" (this is Fannie's name for the HARP program).The terms of the modified loan (trial or permanent) must be used for this comparison.
HAMP is designed specifically to help homeowners impacted by financial hardship. With HAMP, the loan is modified to make the monthly mortgage payment no more than 31% of the Borrower's Gross (pre-tax) Monthly Income. If eligible, the modification permanently changes the original terms of the mortgage.
The loan modification underwriter will analyze and review the particular circumstances which justify a loan modification. The underwriter will evaluate and assess the borrower's financial status, current income and asset situation and ability to pay.
A loan modification can result in an initial drop in your credit score, but at the same time, it's going to have a far less negative impact than a foreclosure, bankruptcy or a string of late payments.If it shows up as not fulfilling the original terms of your loan, that can have a negative effect on your credit.
HAMP's goal is to offer homeowners who are at risk of foreclosure reduced monthly mortgage payments that are affordable and sustainable over the long-term.HAMP was designed to help families who are struggling to remain in their homes and show: Documented financial hardship.