Assignment by Beneficiary of Trust Income for One Year
Overview of this form
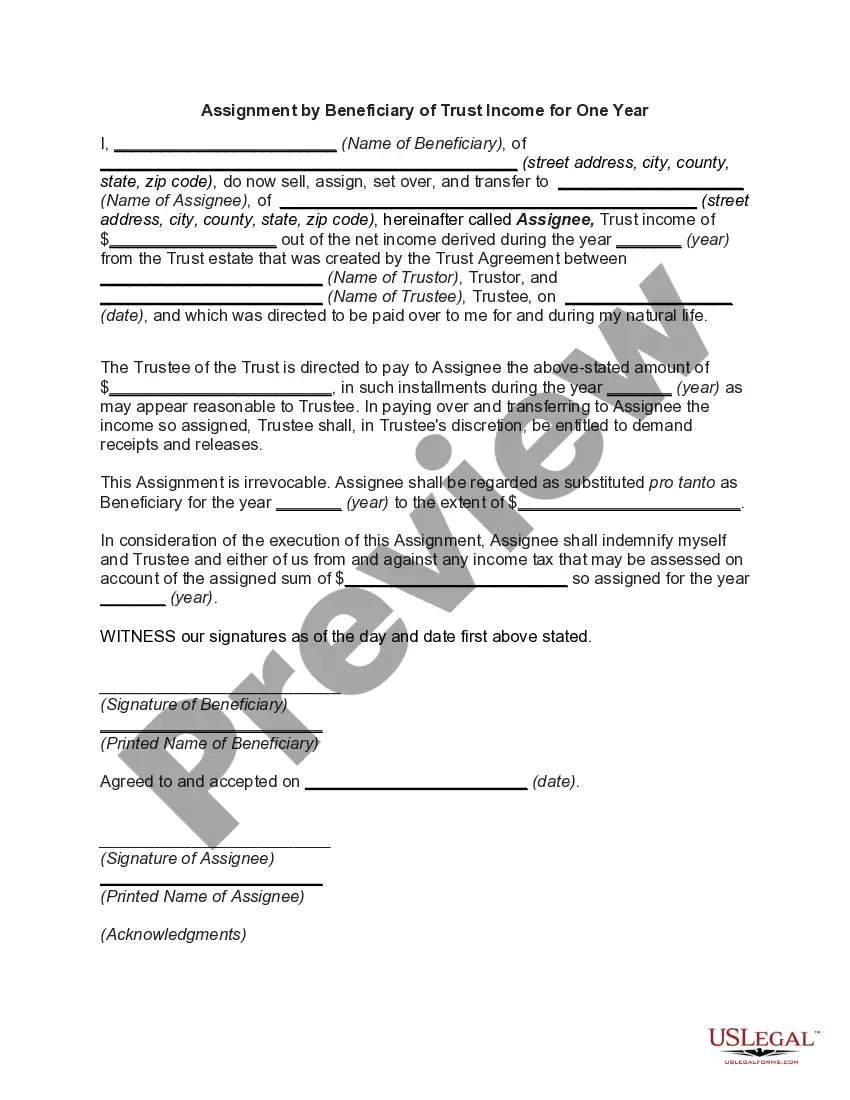
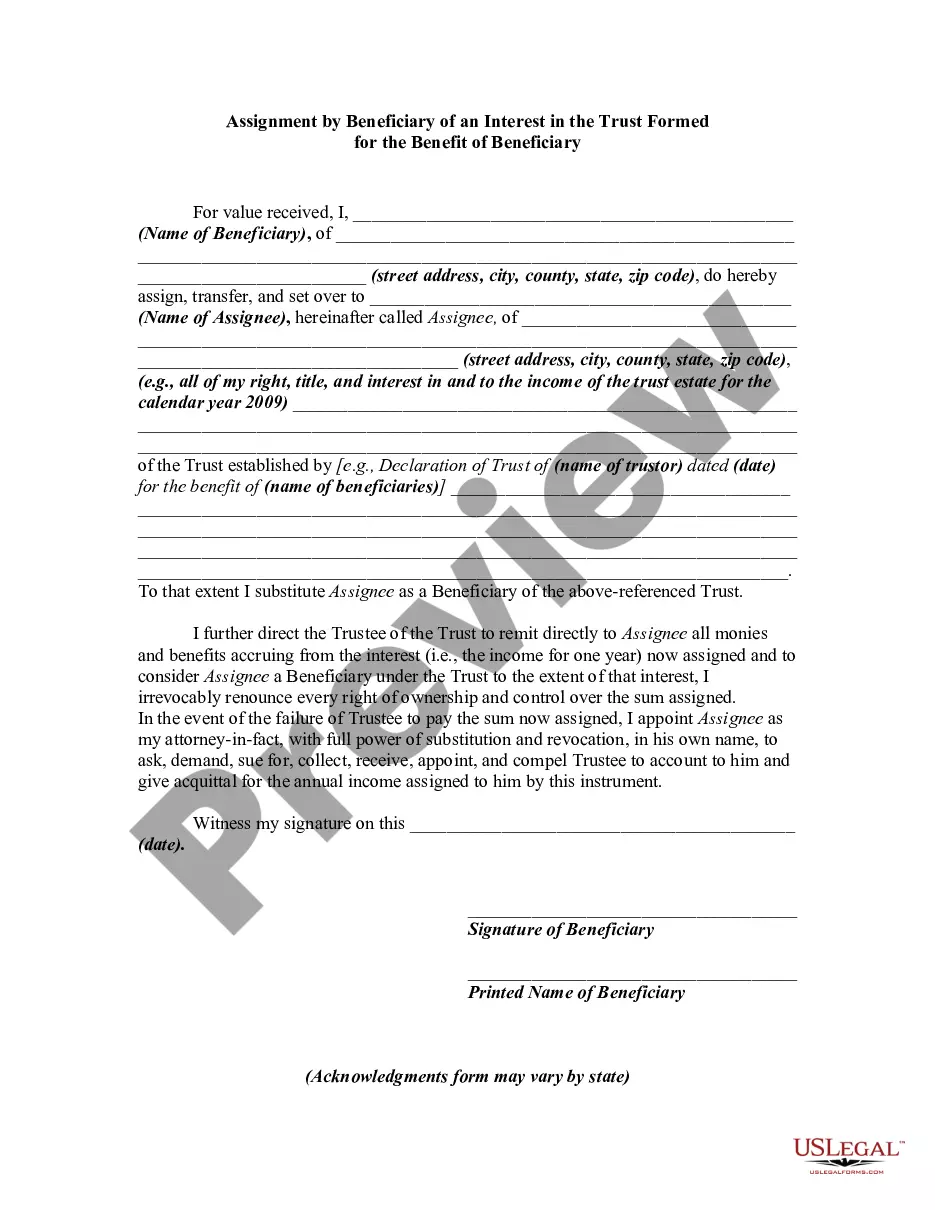
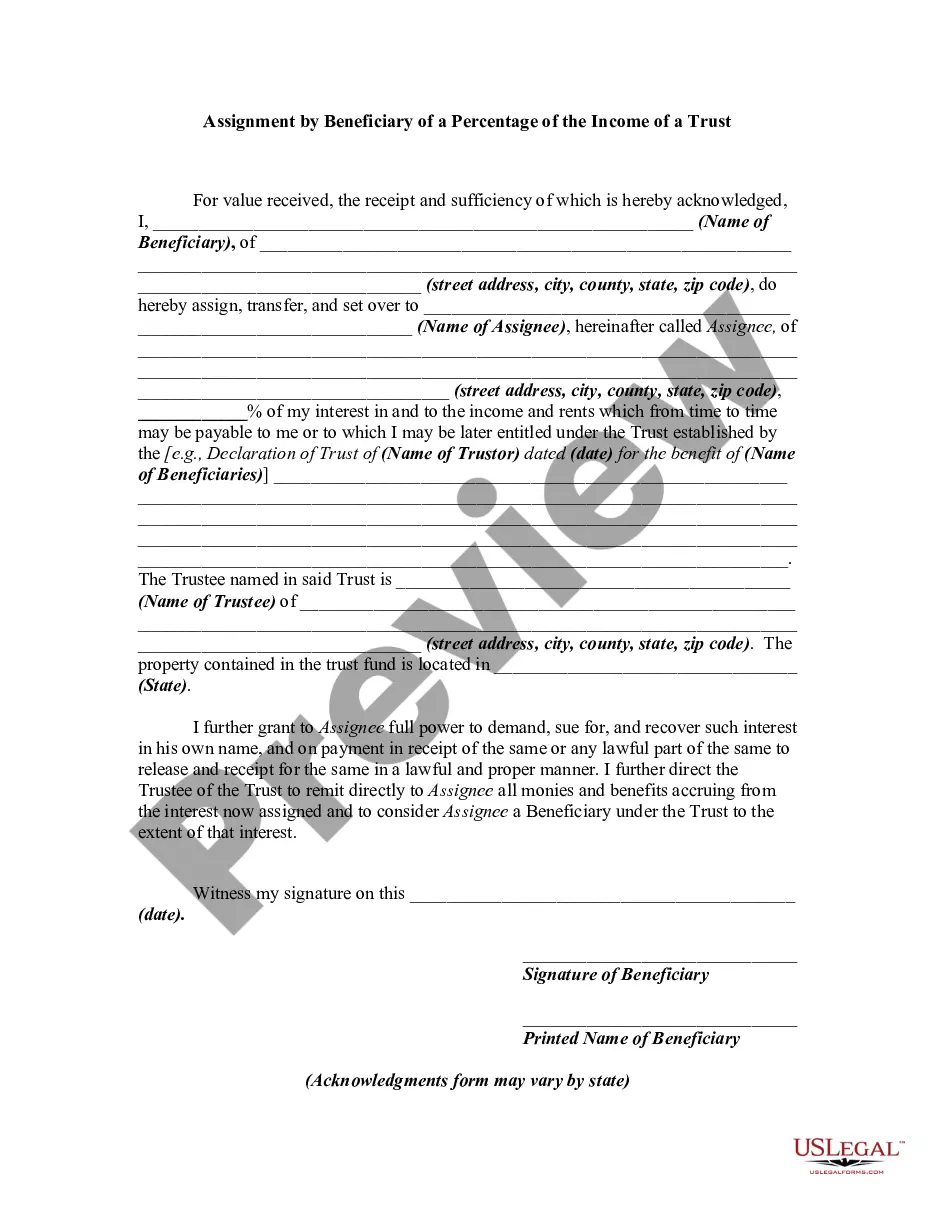
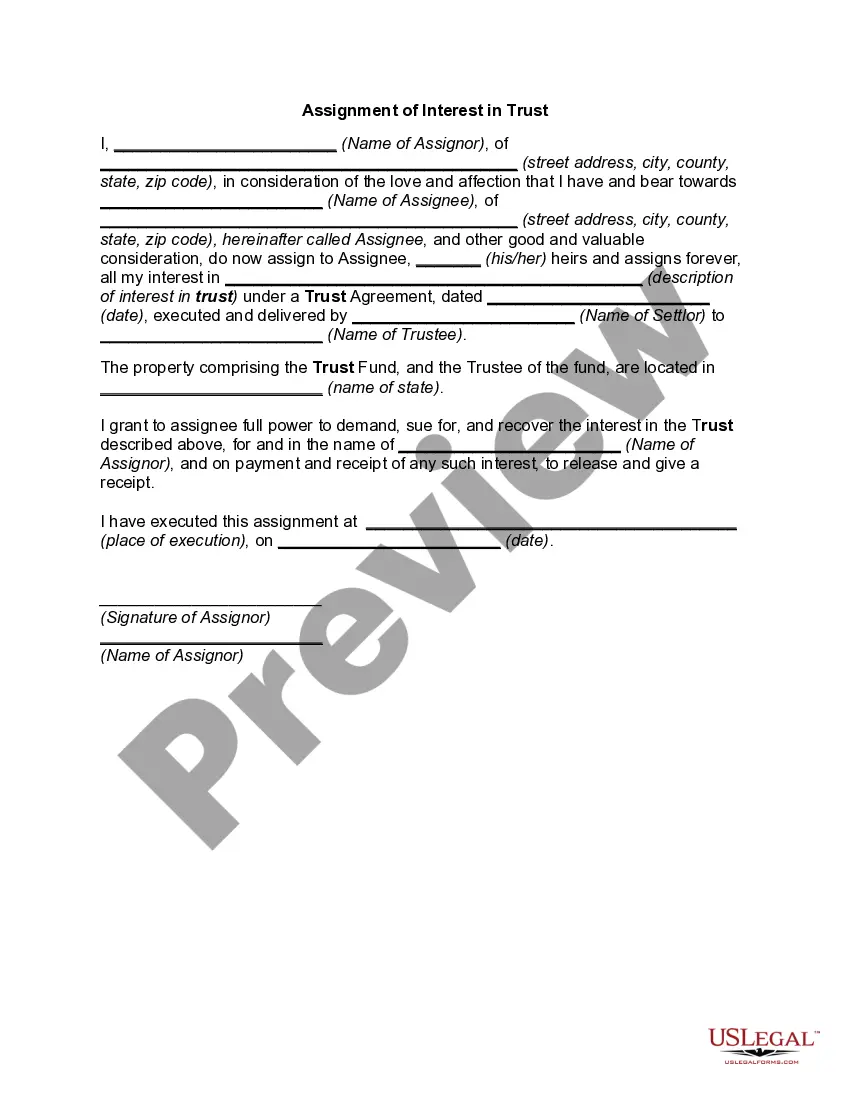
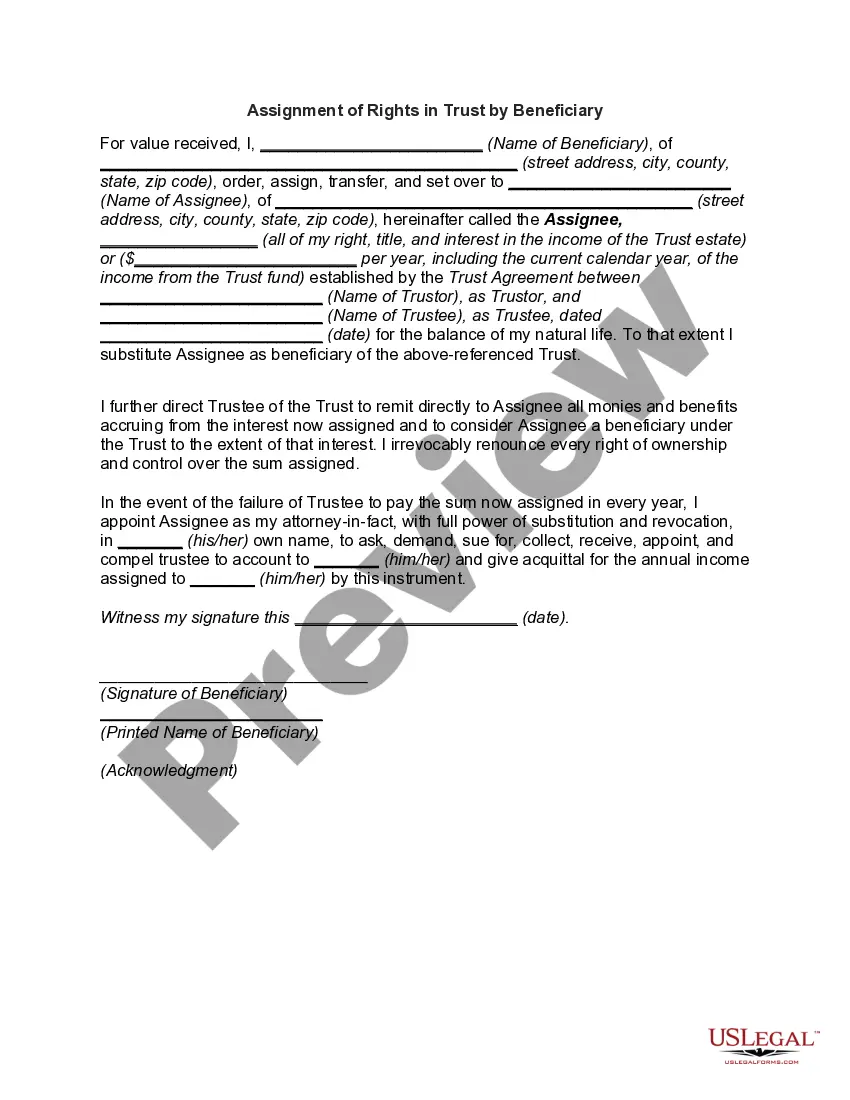
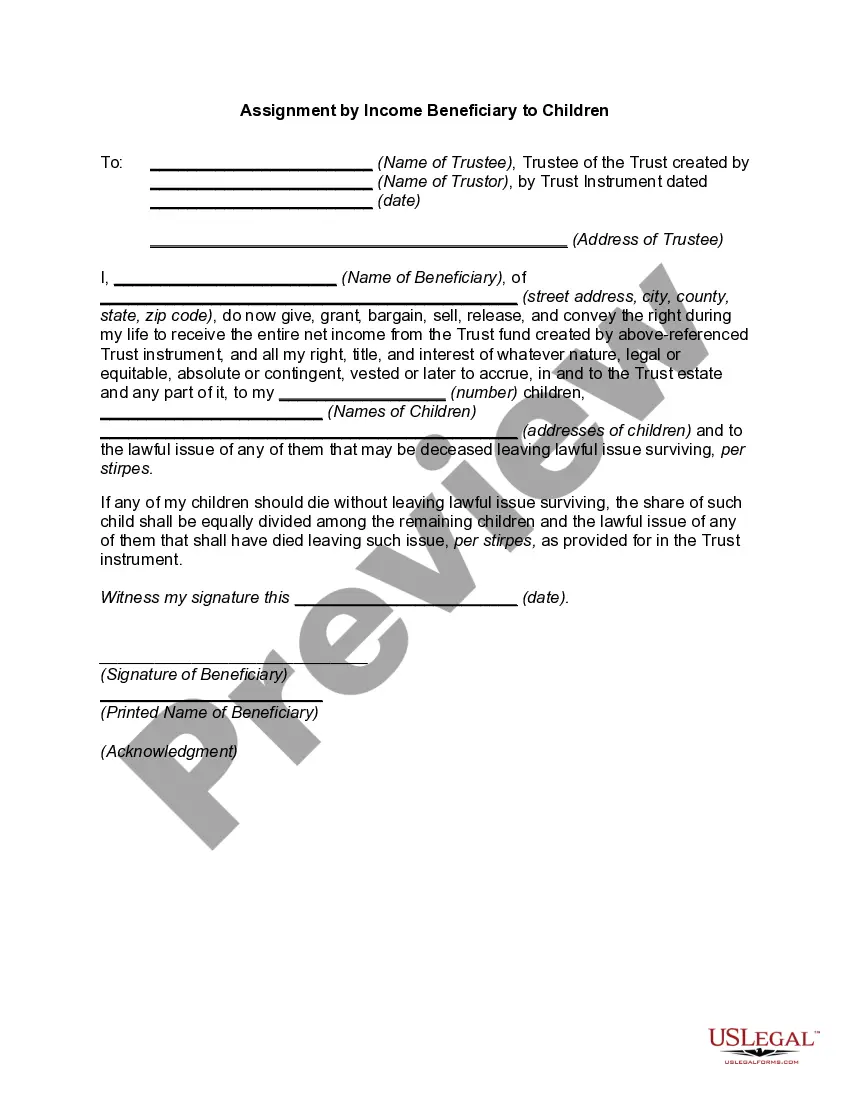
The Assignment by Beneficiary of Trust Income for One Year is a legal document that allows a beneficiary of a trust to assign their right to receive trust income to another party for a specified period, typically one year. This form is distinct from other trust-related documents because it emphasizes the transfer of income rights rather than a complete transfer of the trust property itself. It ensures that the assignee receives the assigned income directly while protecting the interests of all parties involved in the trust agreement.
Key parts of this document
- Beneficiary's name and address.
- Assignee's name and address.
- Details of the trust, including name of the trustor and trustee.
- Amount of income being assigned.
- Specified year for which the income is assigned.
- Indemnification clause regarding tax liabilities.
- Signatures of both beneficiary and assignee, along with their printed names.
When this form is needed
This form is useful when a trust beneficiary desires to temporarily transfer their right to receive income generated by the trust. Situations may arise where the beneficiary may need immediate funds, wish to help someone financially, or simply prefer to delegate their income rights to another party for a defined period. By using this form, beneficiaries can ensure that the terms of their trust are honored while also providing for their financial needs or those of the assignee.
Who this form is for
- Trust beneficiaries seeking to assign income rights to another individual or entity.
- Assignees who are expected to receive trust income for a temporary period.
- Trustees needing a clear and legally compliant method to process income assignments.
- Individuals with a basic understanding of trusts and income assignments.
Steps to complete this form
- Identify the beneficiary and assignee by filling in their names and addresses.
- Specify the amount of income being assigned from the trust.
- Include the name of the trustor and trustee, along with the date the trust was established.
- Clearly state the year for which the income is assigned.
- Ensure both parties sign and print their names to validate the assignment.
Does this document require notarization?
In most cases, this form does not require notarization. However, some jurisdictions or signing circumstances might. US Legal Forms offers online notarization powered by Notarize, accessible 24/7 for a quick, remote process.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Avoid these common issues
- Failing to specify the exact amount of income being assigned.
- Omitting required signatures from either the beneficiary or the assignee.
- Not clearly identifying the trustor and trustee, which may lead to confusion.
- Neglecting to indicate the correct year for which the income assignment is effective.
Why complete this form online
- Convenient access to legal forms from anywhere, at any time.
- Editable templates that allow you to customize the form to your specific needs.
- Reliable legal frameworks drafted by licensed attorneys to ensure compliance.
Looking for another form?

Form popularity
FAQ
Income beneficiary:? can only receive income generated by the trust, not the principal. Principal beneficiary: must wait to receive income from the trust until the income beneficiary interest ends (such as death or a specific period of time).
A primary beneficiary is the person (or people or organizations) you name to receive your stuff when you die. A contingent beneficiary is second in line to receive your assets in case the primary beneficiary passes away. And a residuary beneficiary gets any property that isn't specifically left to another beneficiary.
As a beneficiary of a trust, you have the right to a reasonable report of information about the assets, liabilities, income, bank statements, receipts, and disbursements on the trust property. Beneficiaries are entitled to trust accounting. However, not all beneficiaries are entitled to an accounting.
Income beneficiary includes someone who receives payments from (1) a pooled income fund, (2) a charitable remainder annuity trust, or (3) a charitable remainder unitrust. Return to Life Cycle of a Private Foundation.
Irrevocable trust: If a trust is not a grantor trust, it is considered a separate taxpayer. Taxable income retained by the trust is taxed to the trust. Distributed income is taxed to the beneficiary who receives it.
Income beneficiary includes someone who receives payments from (1) a pooled income fund, (2) a charitable remainder annuity trust, or (3) a charitable remainder unitrust.
Beneficiaries of a trust typically pay taxes on the distributions they receive from a trust's income rather than the trust paying the tax. However, beneficiaries aren't subject to taxes on distributions from the trust's principal, the original sum of money put into the trust.
A current beneficiary (previously referred to as an ?income beneficiary?) is one who receives the income generated by the trust assets. A remainder beneficiary inherits the trust assets when the current beneficiary's dies or his or her interest in the trust terminates.