Irrevocable Trust for Future Benefit of Trustor with Income Payable to Trustor after Specified Time
What is this form?
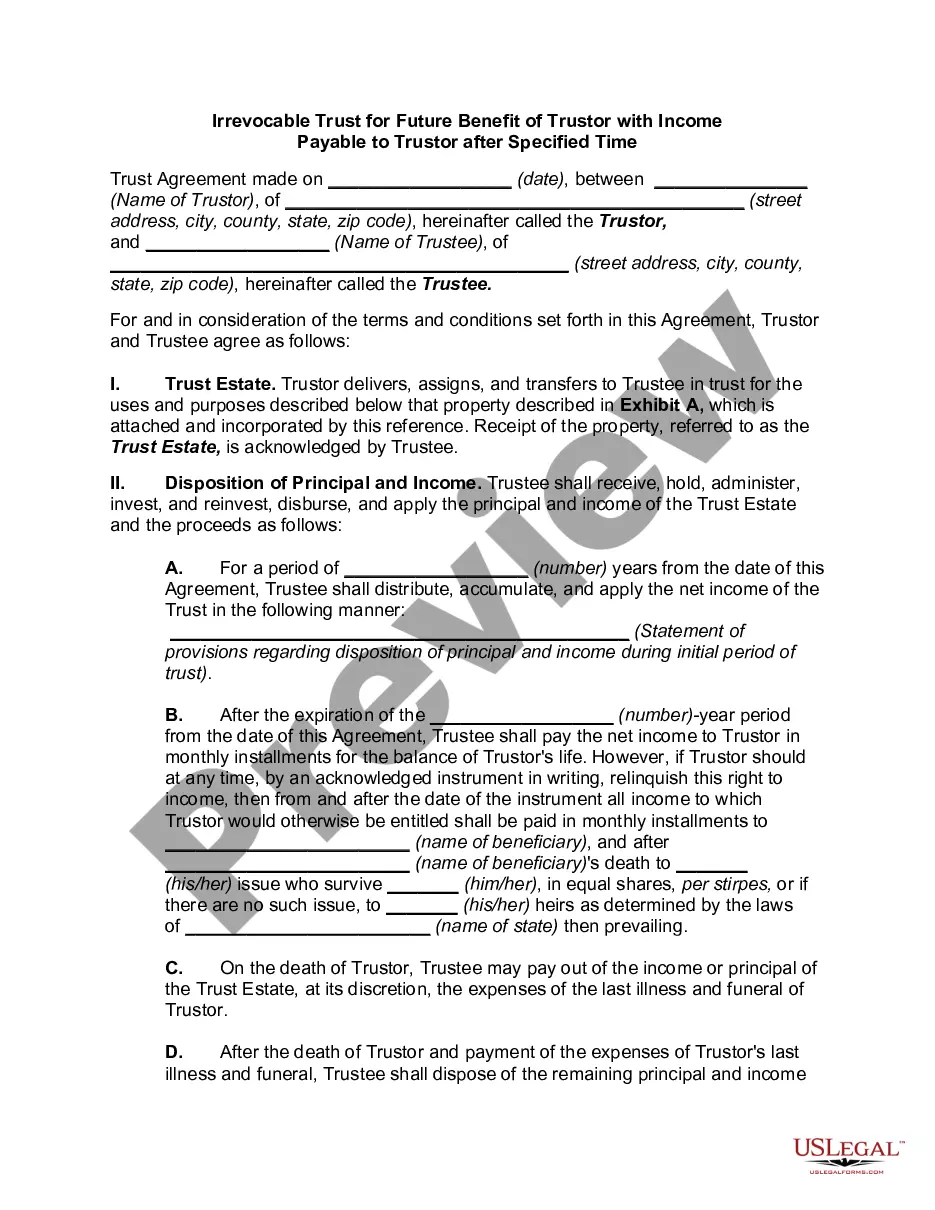
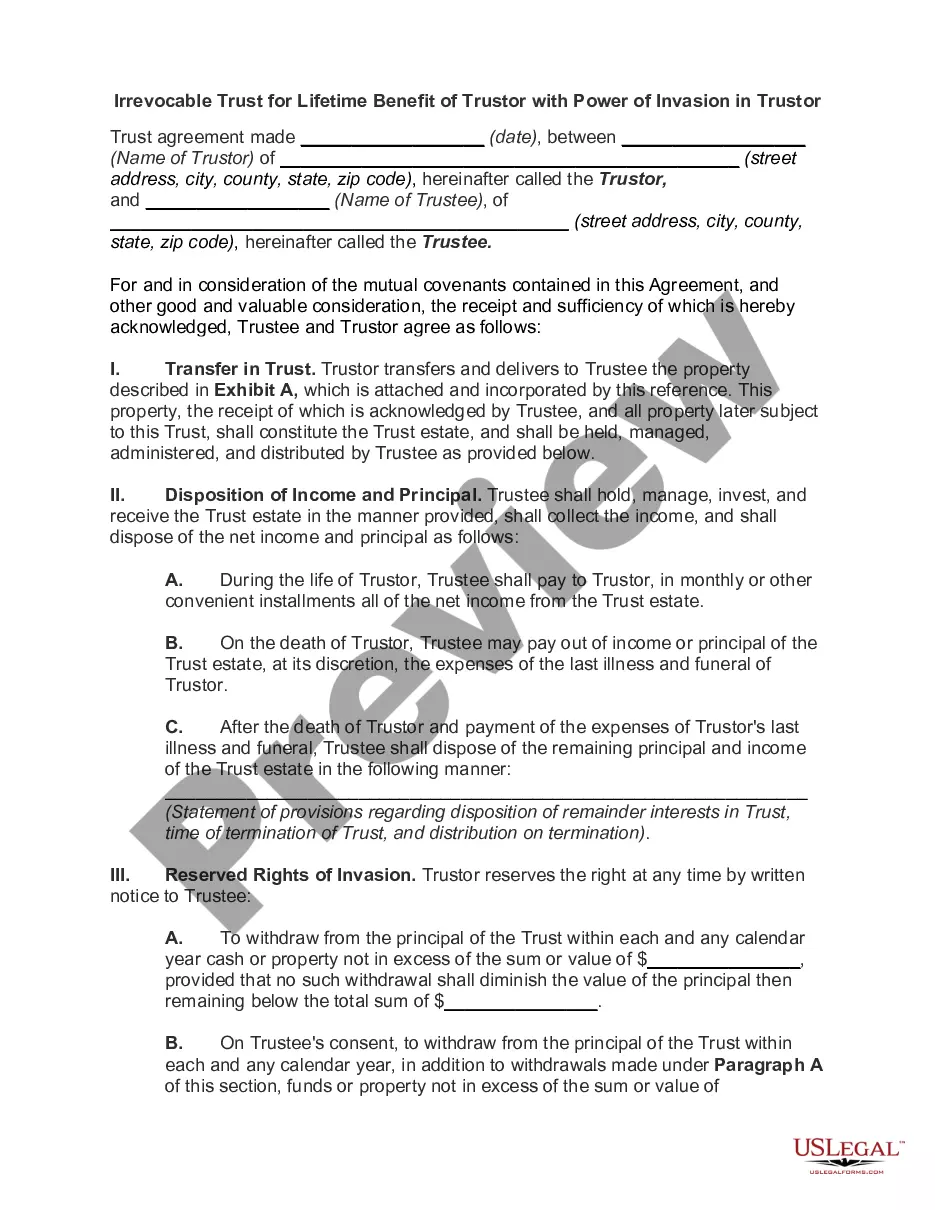
An irrevocable trust is a legal instrument that establishes a trust that cannot be modified or terminated without the consent of the beneficiary. This specific form, the Irrevocable Trust for Future Benefit of Trustor with Income Payable to Trustor after Specified Time, outlines the management of assets placed into the trust. It differentiates itself by allowing the Trustor to benefit from the trust's income after a specified period, making it a valuable option for estate planning and financial management.
What’s included in this form
- Trust Agreement details the parties involved: Trustor and Trustee.
- Trust Estate specifies the property transferred to the trust.
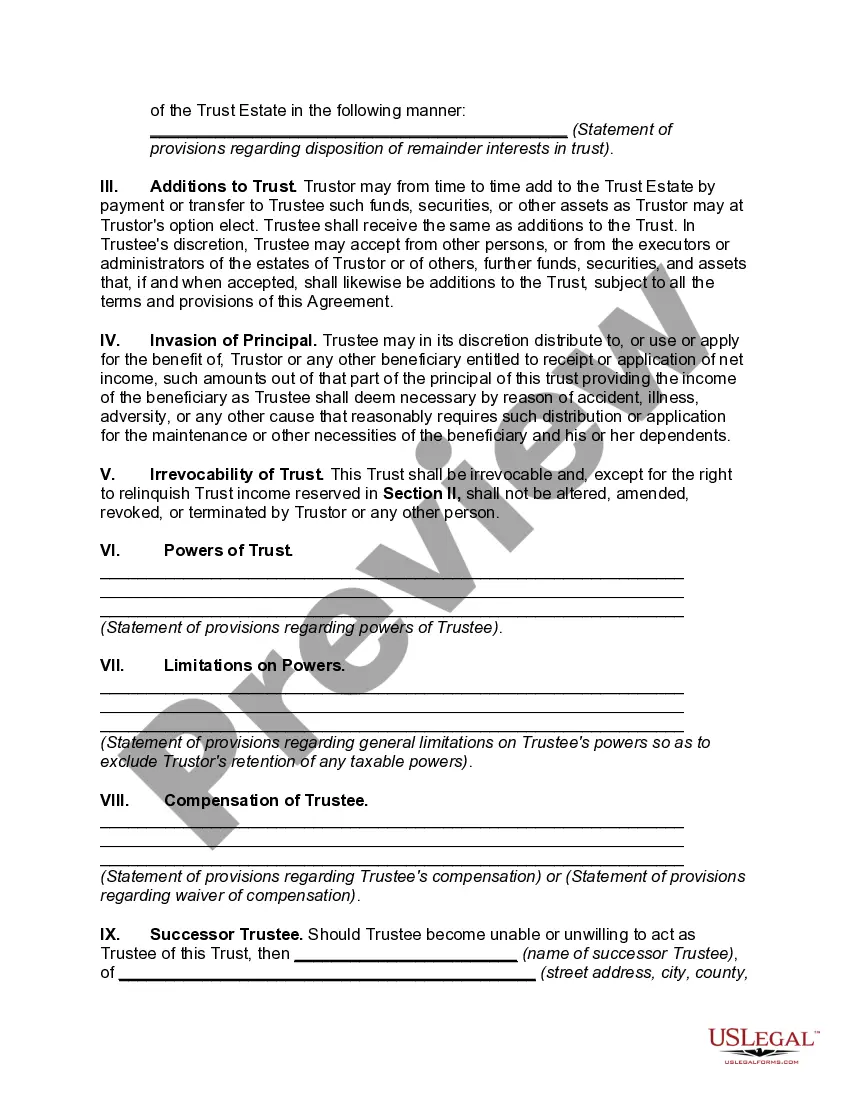
- Disposition of Principal and Income outlines how income and principal will be handled during and after the trust period.
- Additions to Trust allows the Trustor to add more assets over time.
- Irrevocability clause confirms that the trust cannot be altered or revoked.
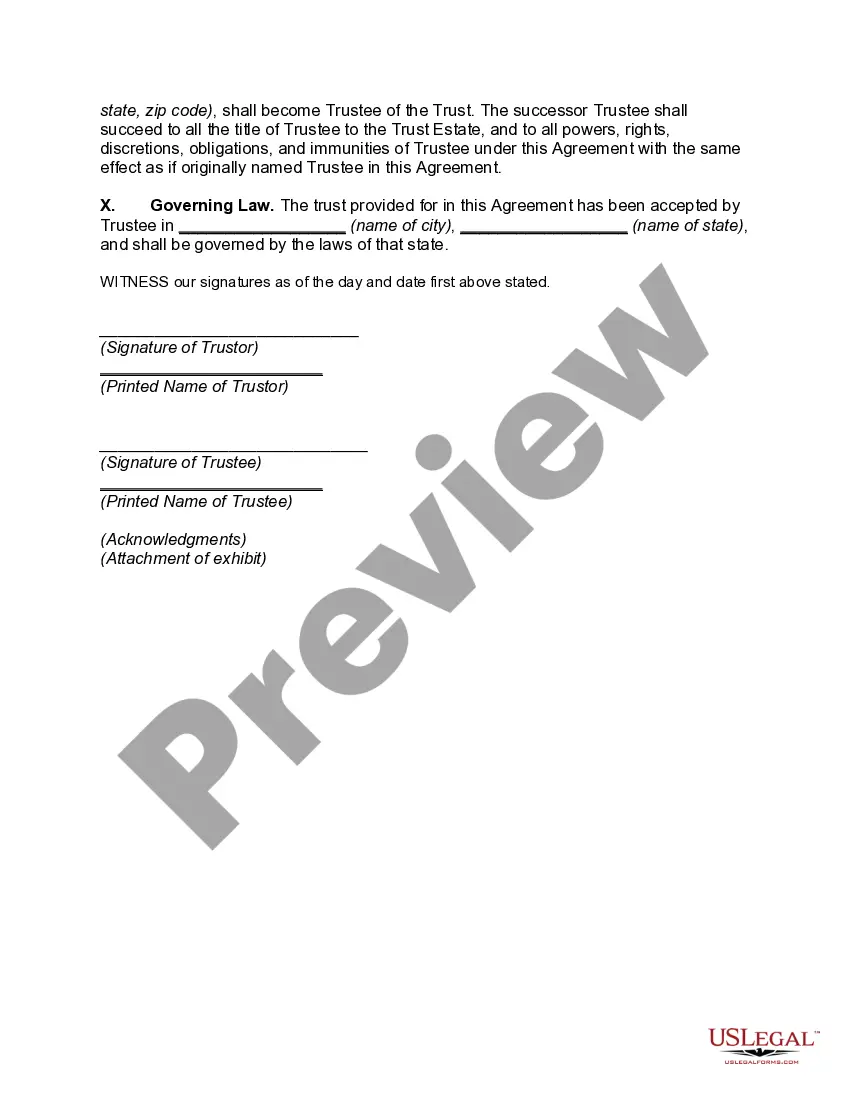
- Successor Trustee provisions detail what happens if the original Trustee can no longer serve.
When to use this document
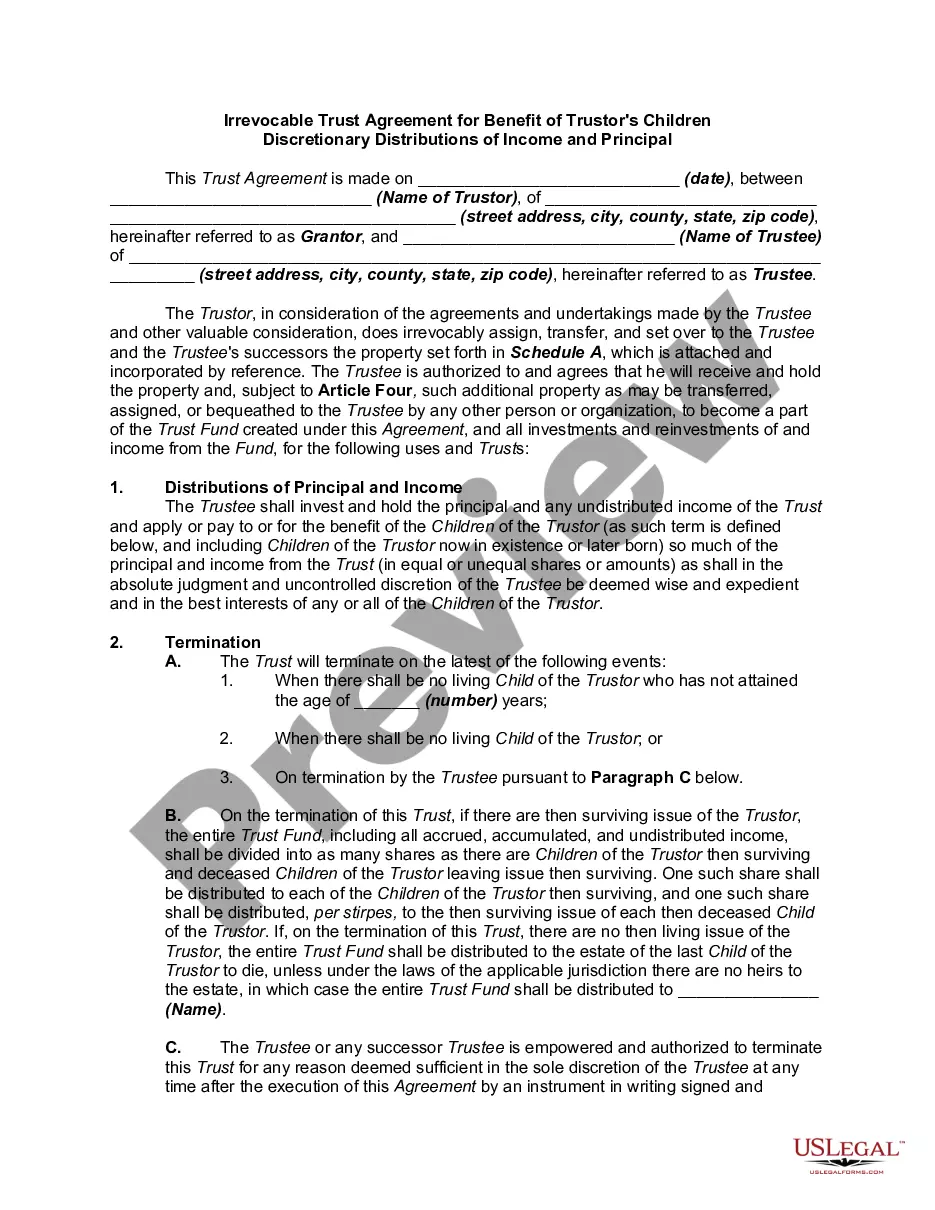
This form is ideal for individuals looking to establish an irrevocable trust that benefits them and their future beneficiaries. Use this trust when you want to ensure that assets are preserved for specific beneficiaries while still allowing yourself access to income after an established waiting period. This can be beneficial in estate planning, tax planning, and ensuring that your financial goals are met while providing for others.
Who should use this form
This form is suitable for:
- Individuals (Trustors) who wish to set up an irrevocable trust for their benefit and that of their beneficiaries.
- Trustees responsible for managing the trust according to its terms.
- Estate planners and advisors looking for a specific strategy to allocate assets over time.
How to complete this form
- Identify and enter the date of creation of the trust agreement.
- Fill in the names and addresses of both the Trustor and the Trustee.
- Specify the property being transferred to the trust in detail.
- Outline any unique handling of principal and income, including the duration before the Trustor receives income.
- Designate a successor Trustee in case the original Trustee is unable to fulfill their duties.
- Include signatures and witness acknowledgments to finalize the agreement.
Does this document require notarization?
This form does not typically require notarization unless specified by local law. However, having the document notarized can provide additional legal validity and assurance in many jurisdictions.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Common mistakes to avoid
- Failing to clearly specify the trust estate's assets.
- Not addressing the income distribution correctly during the specified time frame.
- Overlooking the designation of a successor Trustee.
- Incorrectly indicating the irrevocable nature of the trust.
Why use this form online
- Convenience of downloading and printing at your convenience.
- Editability to customize the form according to your unique situation.
- Access to a reliable, attorney-drafted document to ensure legal compliance.
- Immediate availability without the need for an in-person appointment.
Legal use & context
- This form establishes a legally binding agreement between the Trustor and Trustee for asset management and income distribution.
- It is ideal for individuals wanting to ensure their financial wishes are honored after their death.
- The irrevocable nature ensures that the terms cannot be easily altered, providing certainty for beneficiaries.
Key takeaways
- An irrevocable trust provides a structured approach to asset management and income generation for the Trustor and beneficiaries.
- The form allows for additions to the trust, ensuring flexibility for future contributions.
- Proper completion is crucial to avoid common mistakes and ensure legality.
Looking for another form?
Form popularity
FAQ
As noted above, an irrevocable trust must pay income tax on its earnings. However, a trust is also entitled to take a deduction for income distributions made to a beneficiary.As a trust beneficiary, then, you would owe income tax on distributions made from trust income but not from the principal.
The main downside to an irrevocable trust is simple: It's not revocable or changeable. You no longer own the assets you've placed into the trust. In other words, if you place a million dollars in an irrevocable trust for your child and want to change your mind a few years later, you're out of luck.
An irrevocable trust is taxed as a legally independent entity, in much the same way as an individual taxpayer is taxed in terms of income tax rates and available deductions. Contributing income-earning property to an irrevocable trust means that the IRS will treat the resulting income as trust income, not your income.
Irrevocable trust: The purpose of the trust is outlined by an attorney in the trust document. Once established, an irrevocable trust usually cannot be changed. As soon as assets are transferred in, the trust becomes the asset owner. Grantor: This individual transfers ownership of property to the trust.
Most irrevocable trusts provide Medicaid Asset Protection by not allowing you, the Grantor and Trustee, the ability to access the principal that's placed into the trust.
The trust can pay for any amount of medical costs, as long as the trust pays the expenses directly to the medical provider or institution. Just remember that the terms of the trust are irrevocable regardless of how much you transfer into the trust's name.
An irrevocable trust reports income on Form 1041, the IRS's trust and estate tax return. Even if a trust is a separate taxpayer, it may not have to pay taxes. If it makes distributions to a beneficiary, the trust will take a distribution deduction on its tax return and the beneficiary will receive IRS Schedule K-1.
As noted above, an irrevocable trust must pay income tax on its earnings.Typically, the beneficiary isn't required to pay income taxes on distributions that come from principal because tax law presumes that the grantor already paid income taxes on it when he placed it in the trust and tries to avoid double taxation.
The grantor (as an individual or couple) transfers their assets to an irrevocable trust. However, unlike other irrevocable trusts, the grantor can be the income beneficiary.The grantor can receive income from the trust to the maximum amount allowed by Medicaid.