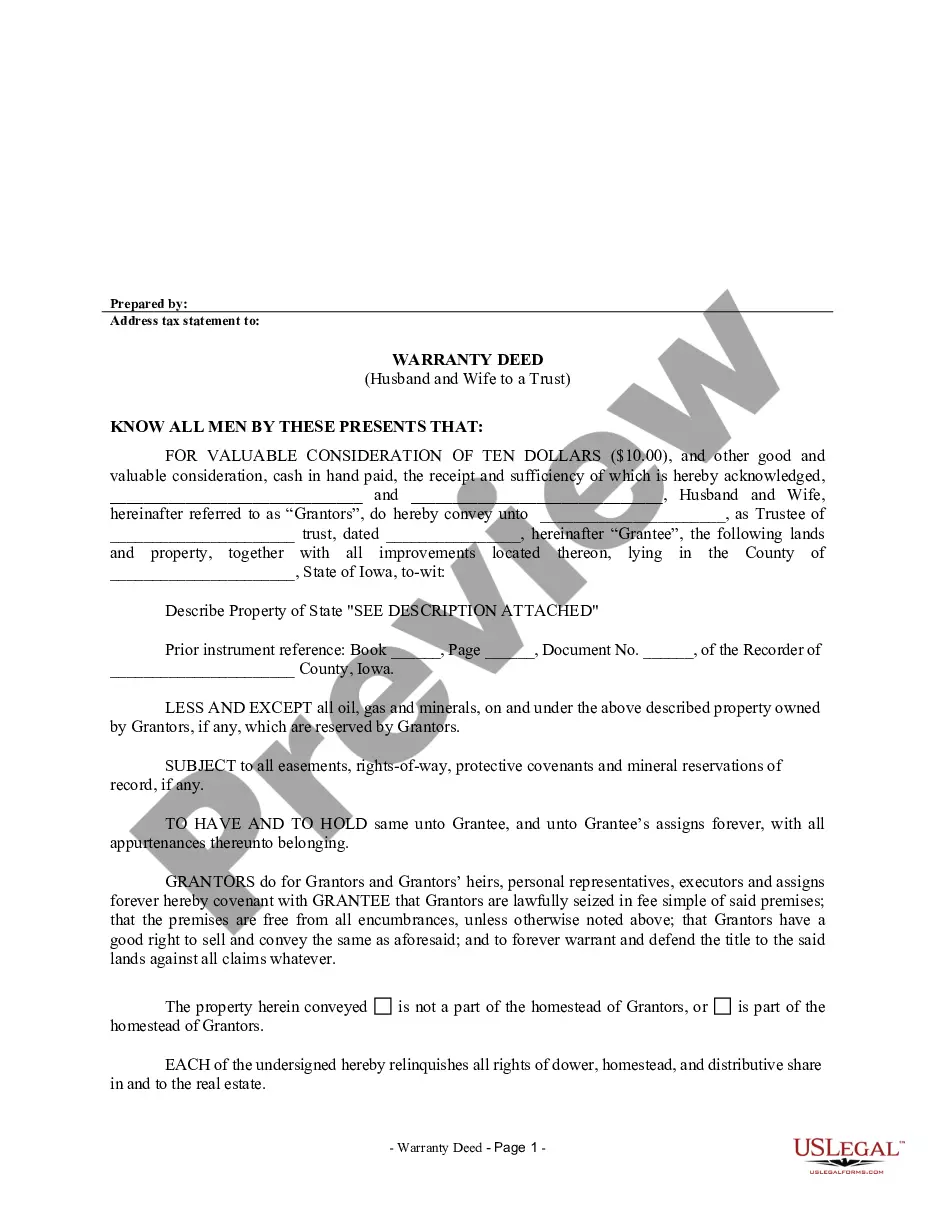
Revocable Trust for Lifetime Benefit of Trustor for Lifetime Benefit of Surviving Spouse after Death of Trustor's with Annuity
What this document covers
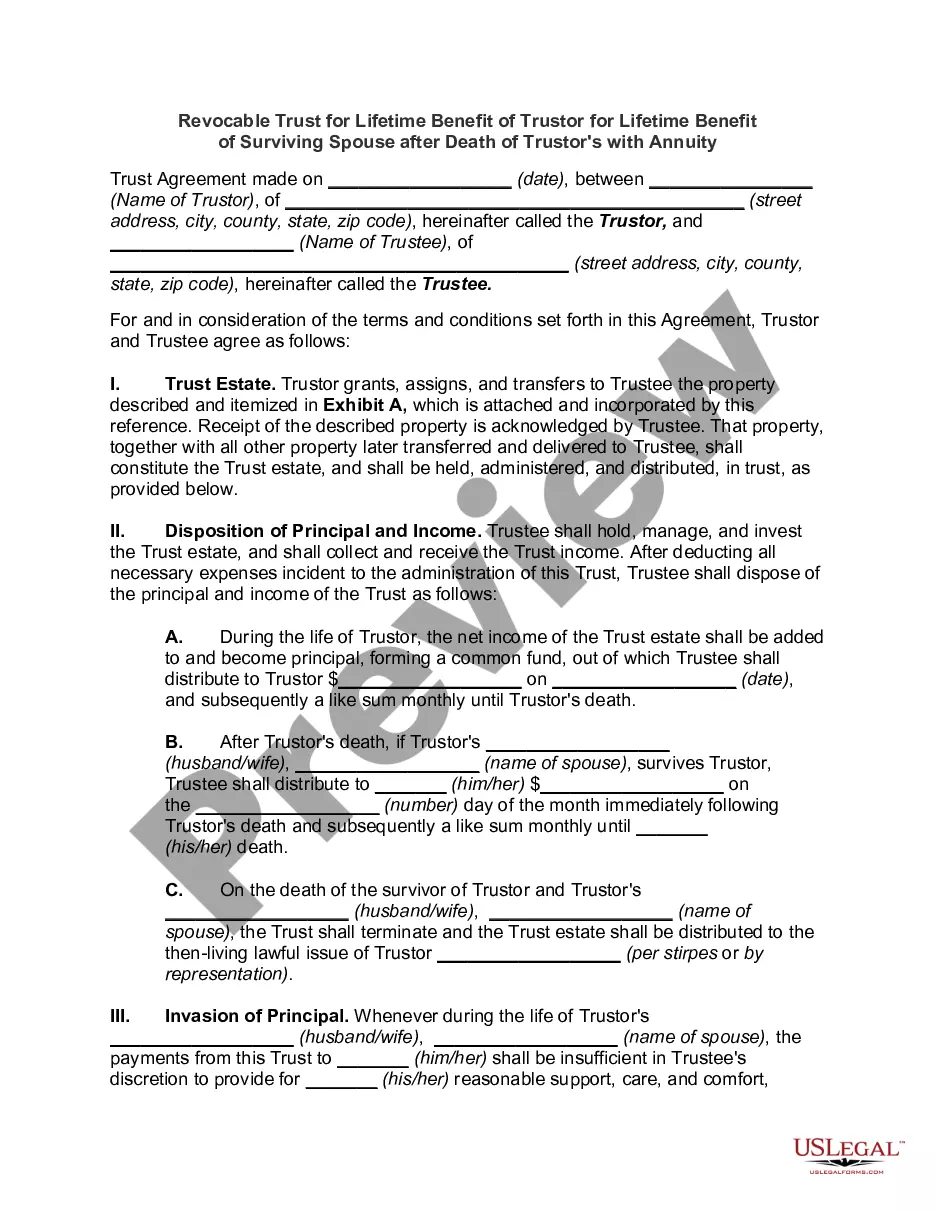
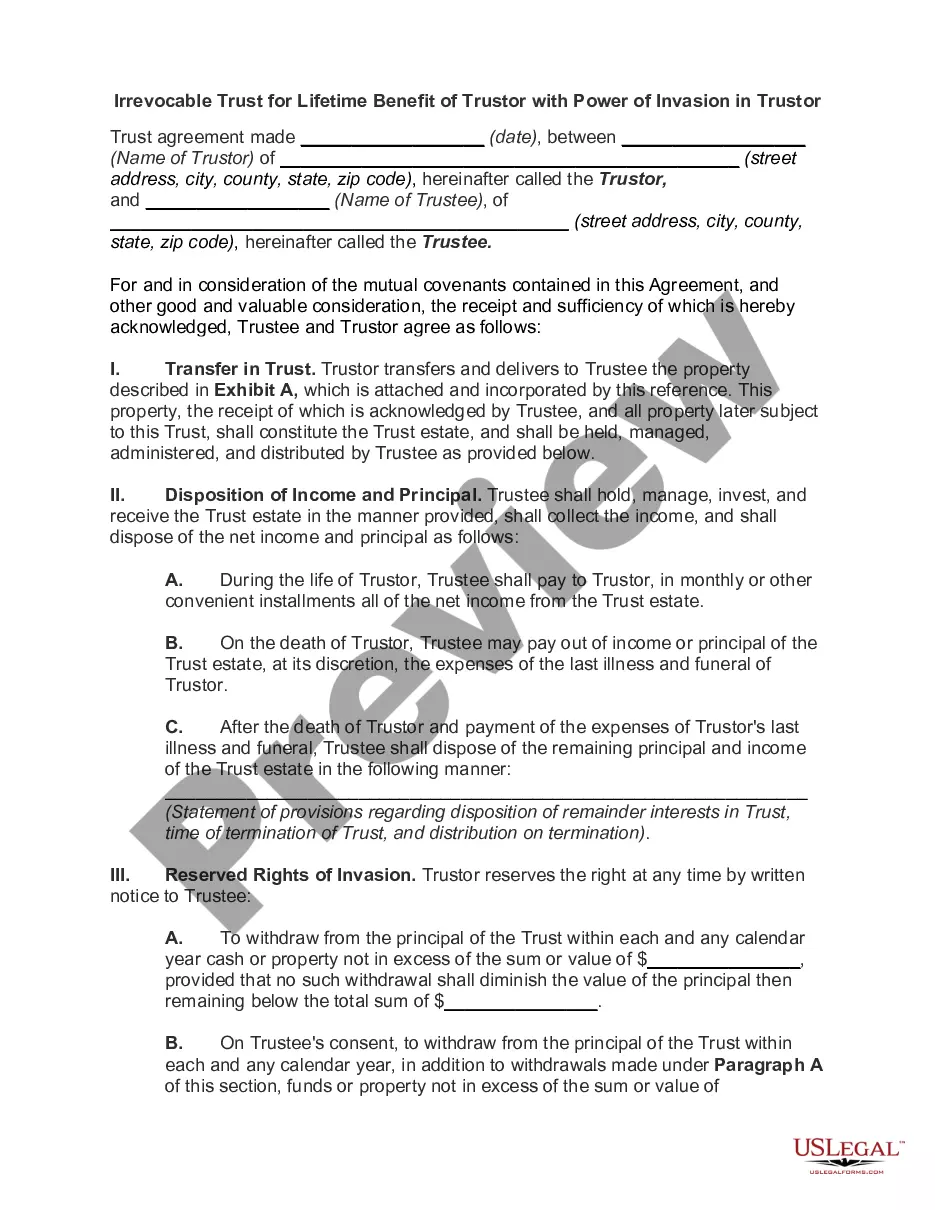
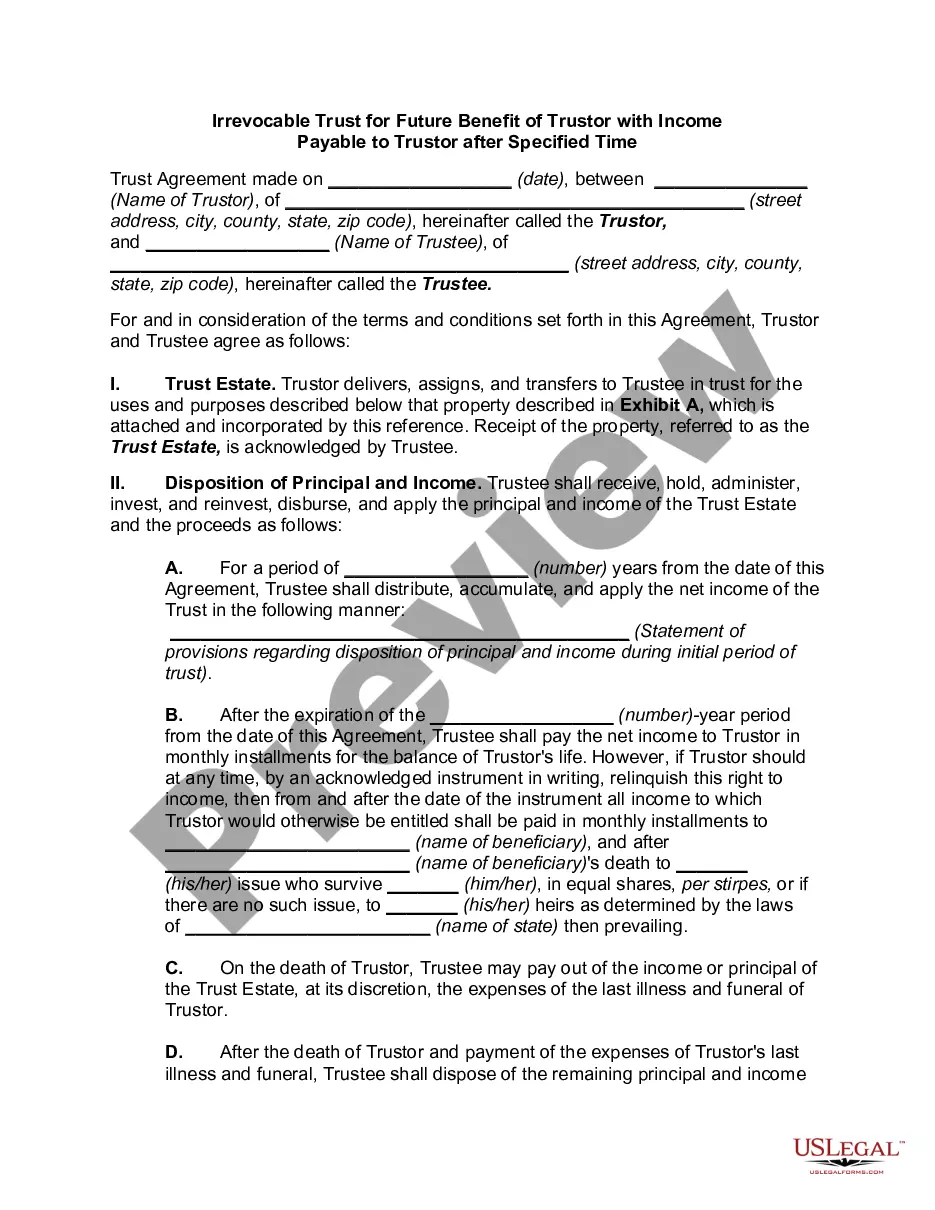
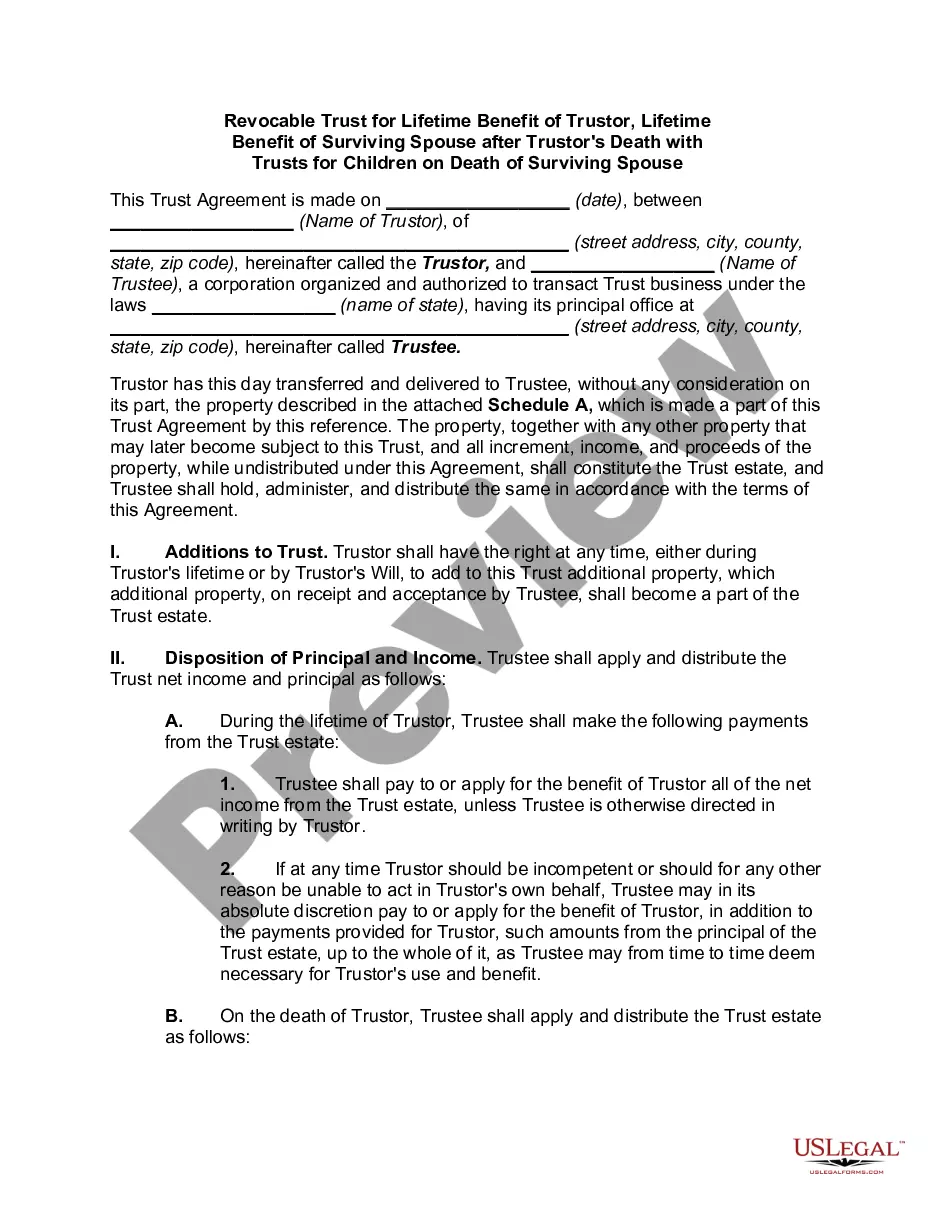
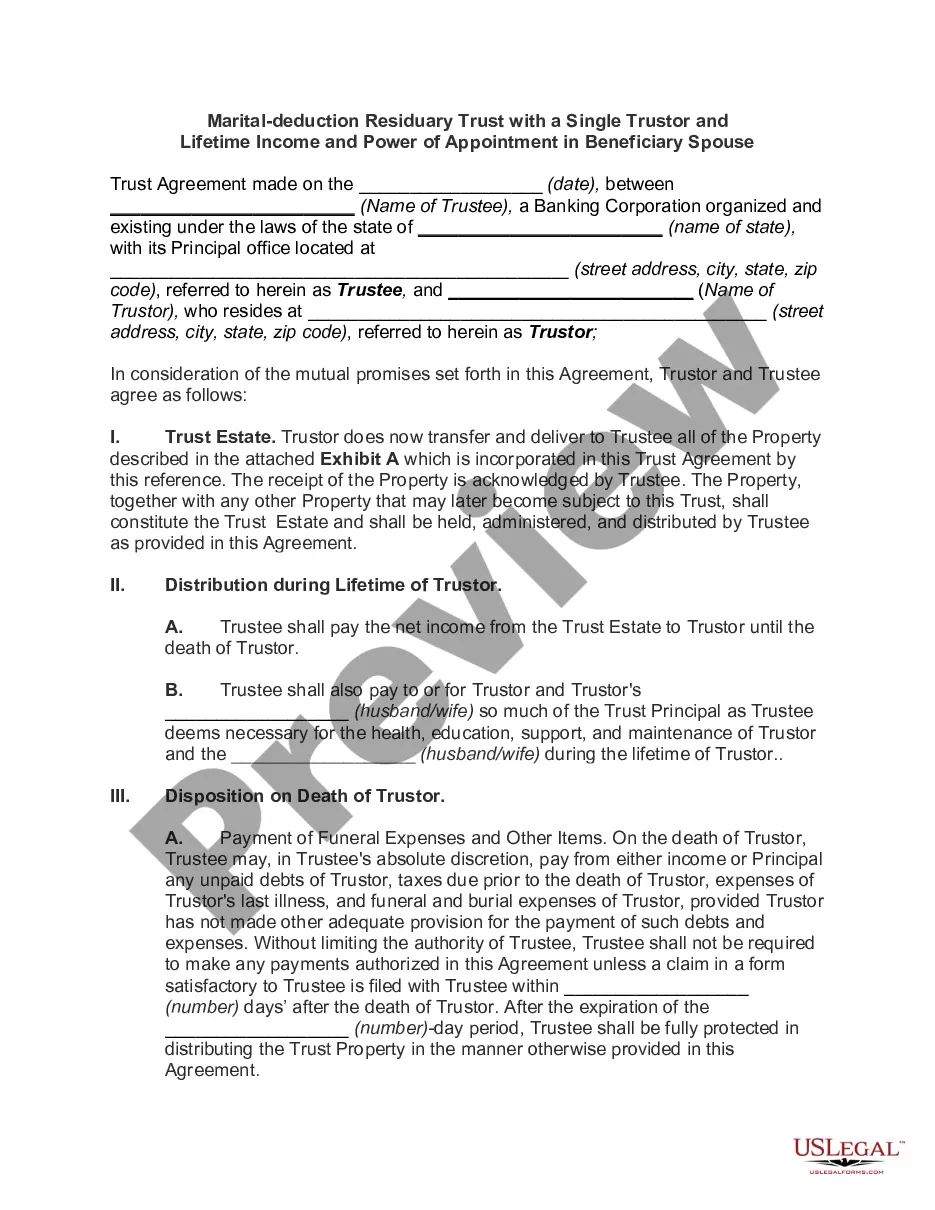
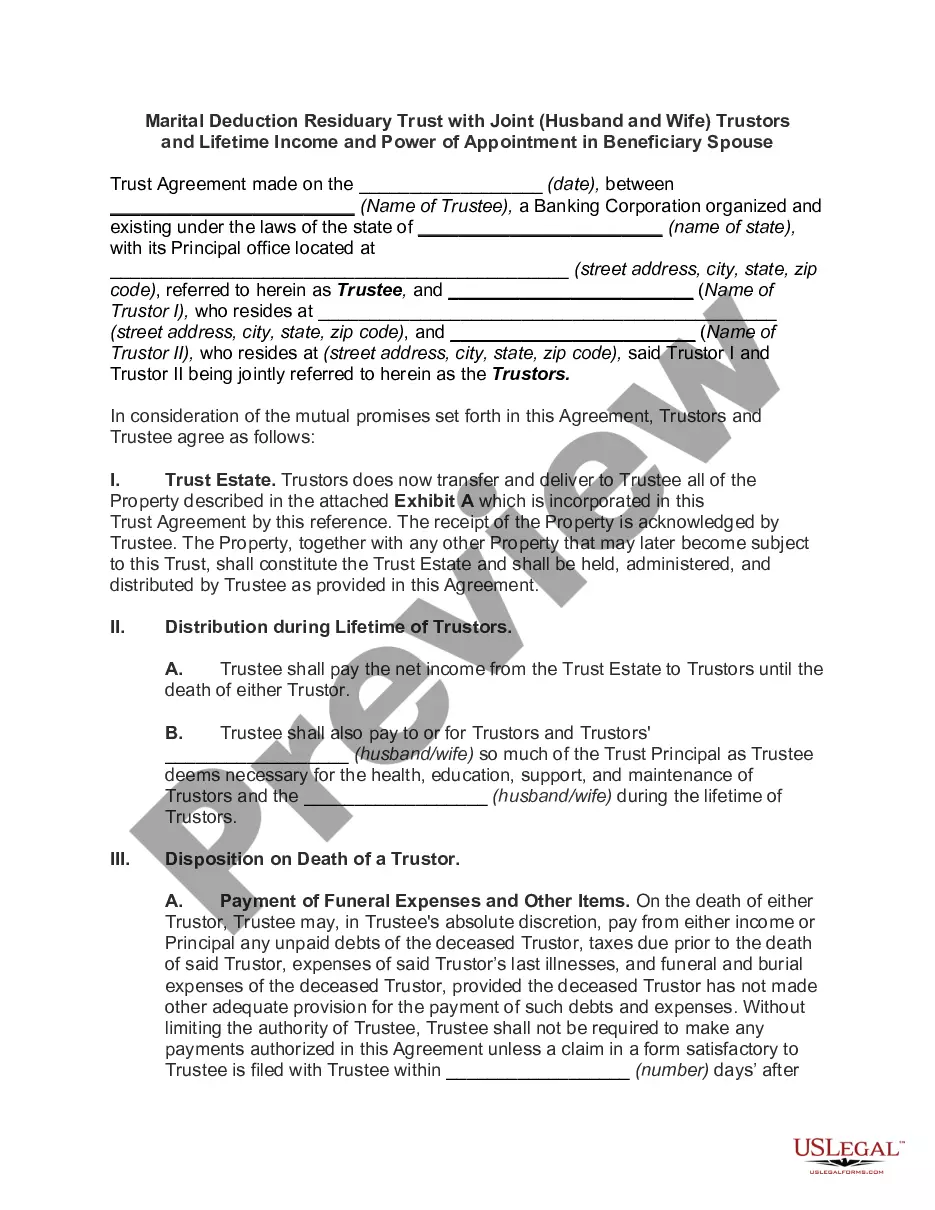
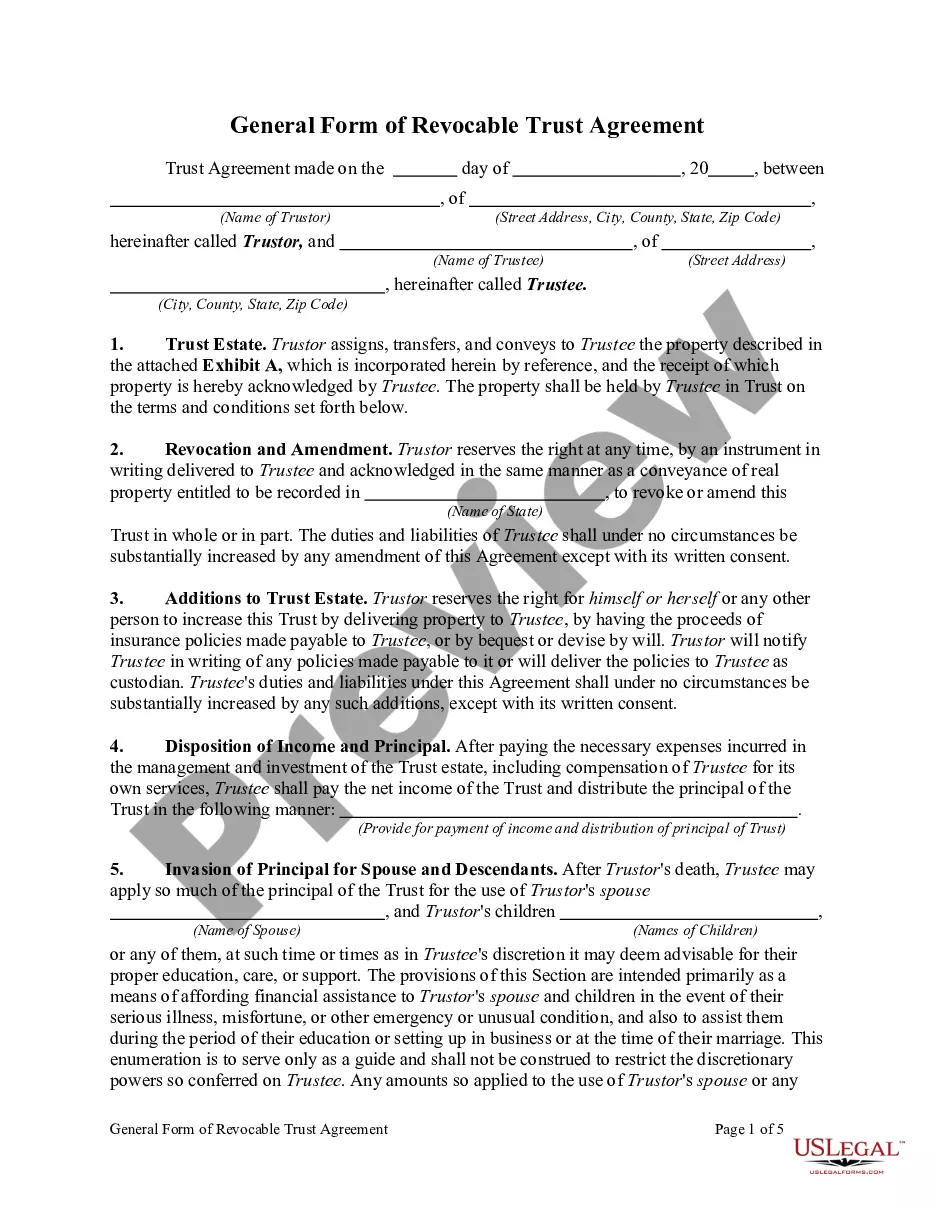
A revocable trust for lifetime benefit of trustor allows the trustor to establish a trust that provides income to beneficiaries during their lifetime, specifically designed to support a surviving spouse after the trustor's death. This form is essential in estate planning as it ensures a steady income through annuity payments while maintaining flexibility for the trustor to modify or revoke the trust at any time during their lifetime.
Main sections of this form
- Identification of the trustor and trustee.
- Description of the trust estate and any property included.
- Provisions for the distribution of trust income and principal during and after the trustor's lifetime.
- Details regarding the invasion of principal for the surviving spouse's support.
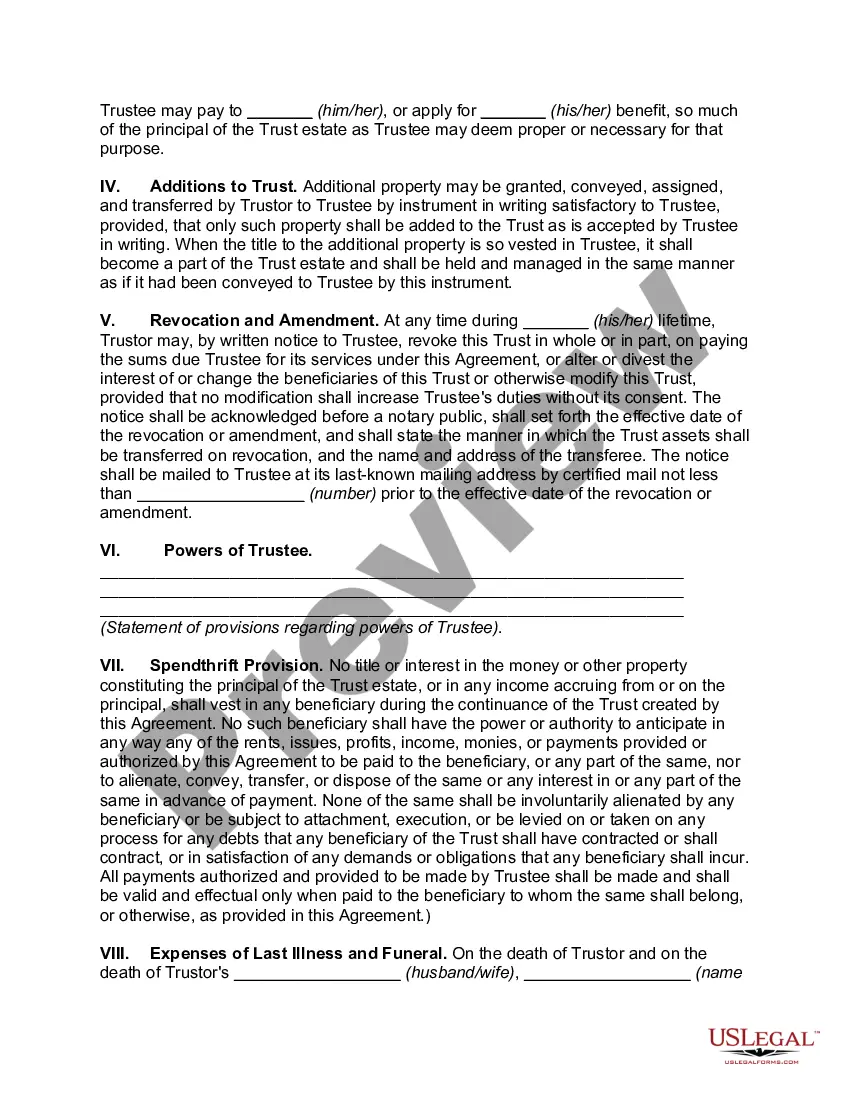
- Instructions for revocation or amendment of the trust.
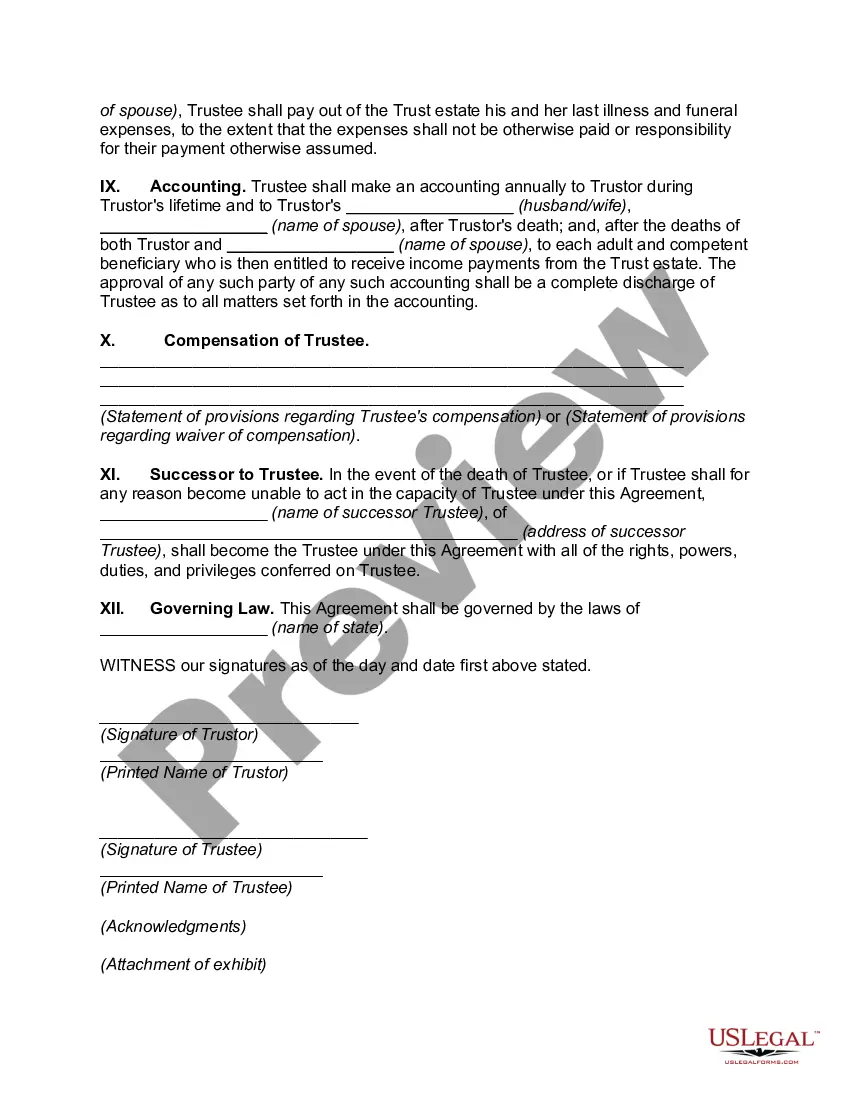
- Trustee powers and responsibilities.
- Guidelines for covering last illness and funeral expenses from trust funds.
Common use cases
This form is useful when a trustor wants to ensure financial support for a surviving spouse while retaining control over the trust assets during their lifetime. Itâs ideal for individuals looking to manage their estate efficiently and streamline the transfer of assets after death. This form can also be utilized when additional property needs to be added to the trust over time.
Who needs this form
This form is intended for:
- Individuals who wish to establish a trust to benefit their surviving spouse.
- Trustors who want to maintain control over their assets during their lifetime.
- People looking for a flexible estate planning solution that can adapt to changing circumstances.
- Those who have specific financial needs or obligations for their spouse that must be considered.
Instructions for completing this form
- Identify the trustor and trustee by entering their full names and addresses.
- List the property included in the trust in Exhibit A.
- Specify the distributions of trust income and principal during the trustor's and spouse's lifetime.
- Outline the conditions for the invasion of trust principal if necessary for the spouse's support.
- Enter any provisions related to revocation or amendment of the trust.
- Sign the document in the presence of a notary public if required by local law.
Does this form need to be notarized?
This form does not typically require notarization unless specified by local law. However, having the document notarized can help ensure its validity and may be advisable depending on the jurisdiction.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Avoid these common issues
- Failing to properly identify the trustor and trustee.
- Neglecting to list all pertinent property in the trust deed.
- Not updating the trust when circumstances change, such as marriage or divorce.
- Omitting necessary witness or notarization requirements.
Benefits of completing this form online
- Convenience of completing the form from anywhere, at any time.
- Editability allows you to customize your trust easily.
- Access to professionally drafted templates increases reliability.
- Immediate download option to expedite the planning process.
Summary of main points
- This revocable trust allows for flexible asset management and distribution plans.
- It provides financial security to the Trustor and their surviving spouse.
- Provisions allow for modifications to the trust during the Trustor's lifetime.
- Understanding state-specific regulations is crucial for valid implementation.
Looking for another form?
Form popularity
FAQ
A revocable trust becomes irrevocable at the death of the person that created the trust.The Trust becomes its own entity and needs a tax identification number for filing of returns. 2. The Grantor (also called the Trustor) of the Trust becomes incapacitated.
The process of funding your living trust by transferring your assets to the trustee is an important part of what helps your loved ones avoid probate court in the event of your death or incapacity. Qualified retirement accounts such as 401(k)s, 403(b)s, IRAs, and annuities, should not be put in a living trust.
When they pass away, the assets are distributed to beneficiaries, or the individuals they have chosen to receive their assets. A settlor can change or terminate a revocable trust during their lifetime. Generally, once they die, it becomes irrevocable and is no longer modifiable.
When the maker of a revocable trust, also known as the grantor or settlor, dies, the assets become property of the trust. If the grantor acted as trustee while he was alive, the named co-trustee or successor trustee will take over upon the grantor's death.
Assets in a revocable living trust will avoid probate at the death of the grantor, because the successor trustee named in the trust document has immediate legal authority to act on behalf of the trust (the trust doesn't die at the death of the grantor).
The procedure for settling a trust after death entails: Step 1: Get death certificate copies. Step 2: Inventory the assets in the estate. Step 3: Work with a trust attorney to understand the grantor's distribution wishes, timelines, and fiduciary responsibilities. Step 4: Asset appraisal. Step 5: Pay taxes.
For capital gains purposes, the value of the assets would be equal to their value when you inherited them. Assets that have been conveyed into a revocable living trust do get a step-up in basis when they are distributed to the beneficiaries after the passing of the grantor.
Beneficiaries of a trust typically pay taxes on the distributions they receive from the trust's income, rather than the trust itself paying the tax. However, such beneficiaries are not subject to taxes on distributions from the trust's principal.
The Revocable Trust tax implications, following the death of the Grantor, impact both the Grantor's Estate and the Beneficiaries'.However, any income earned by the Trust assets or principal after the date of the Grantor's death is reported in a separate tax return for the Trust.