New York Building Loan Agreement
About this form
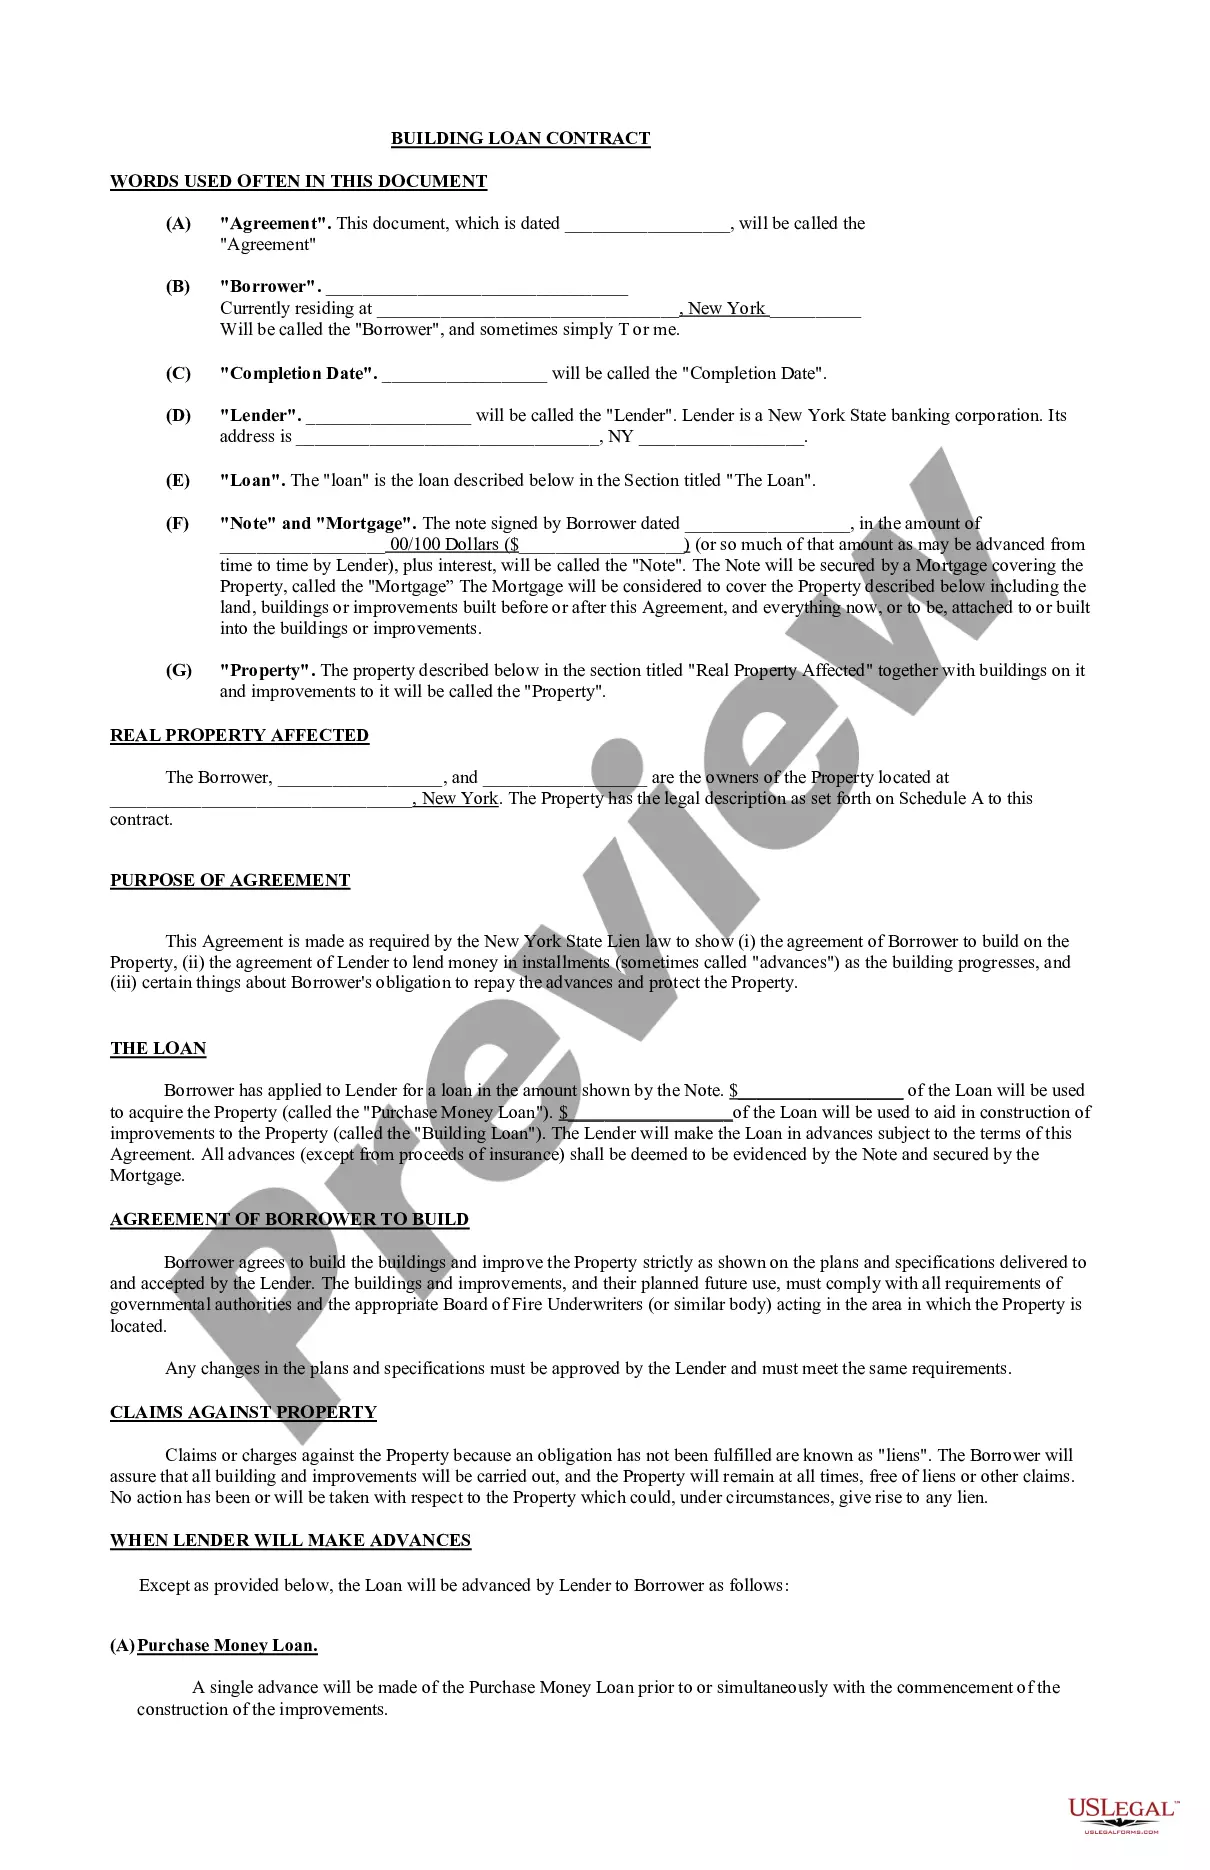
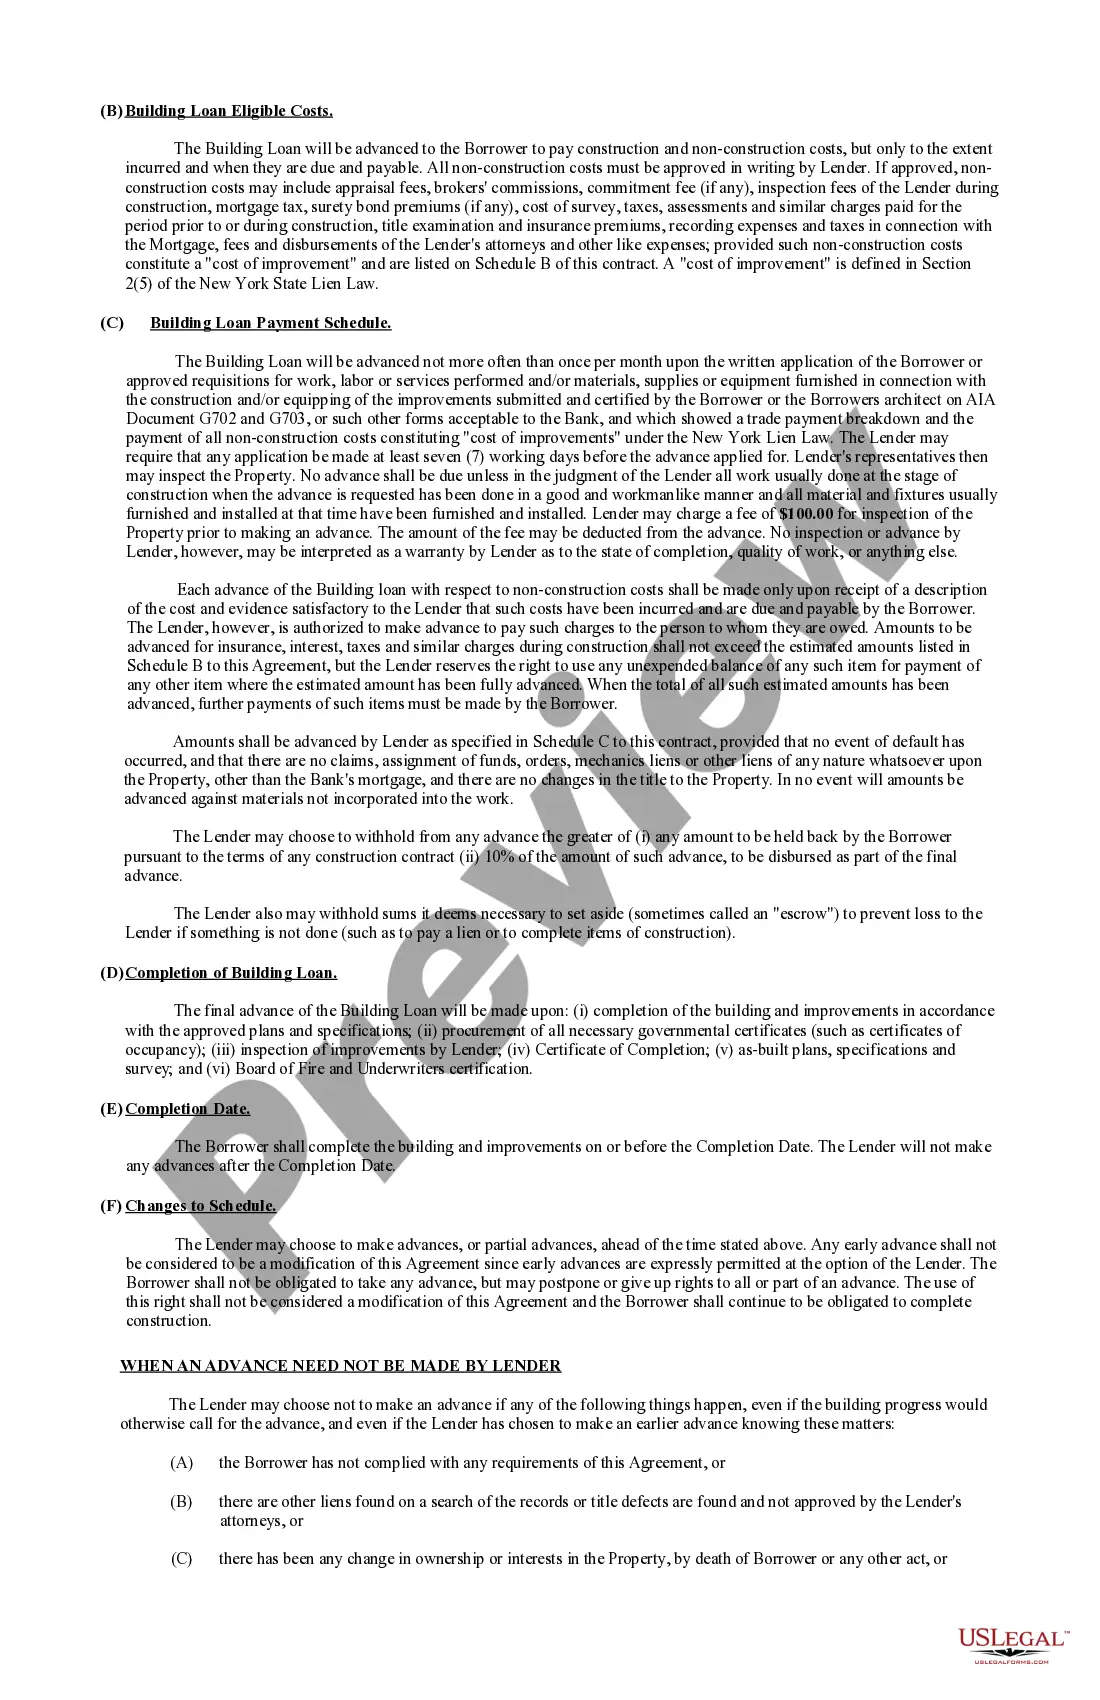
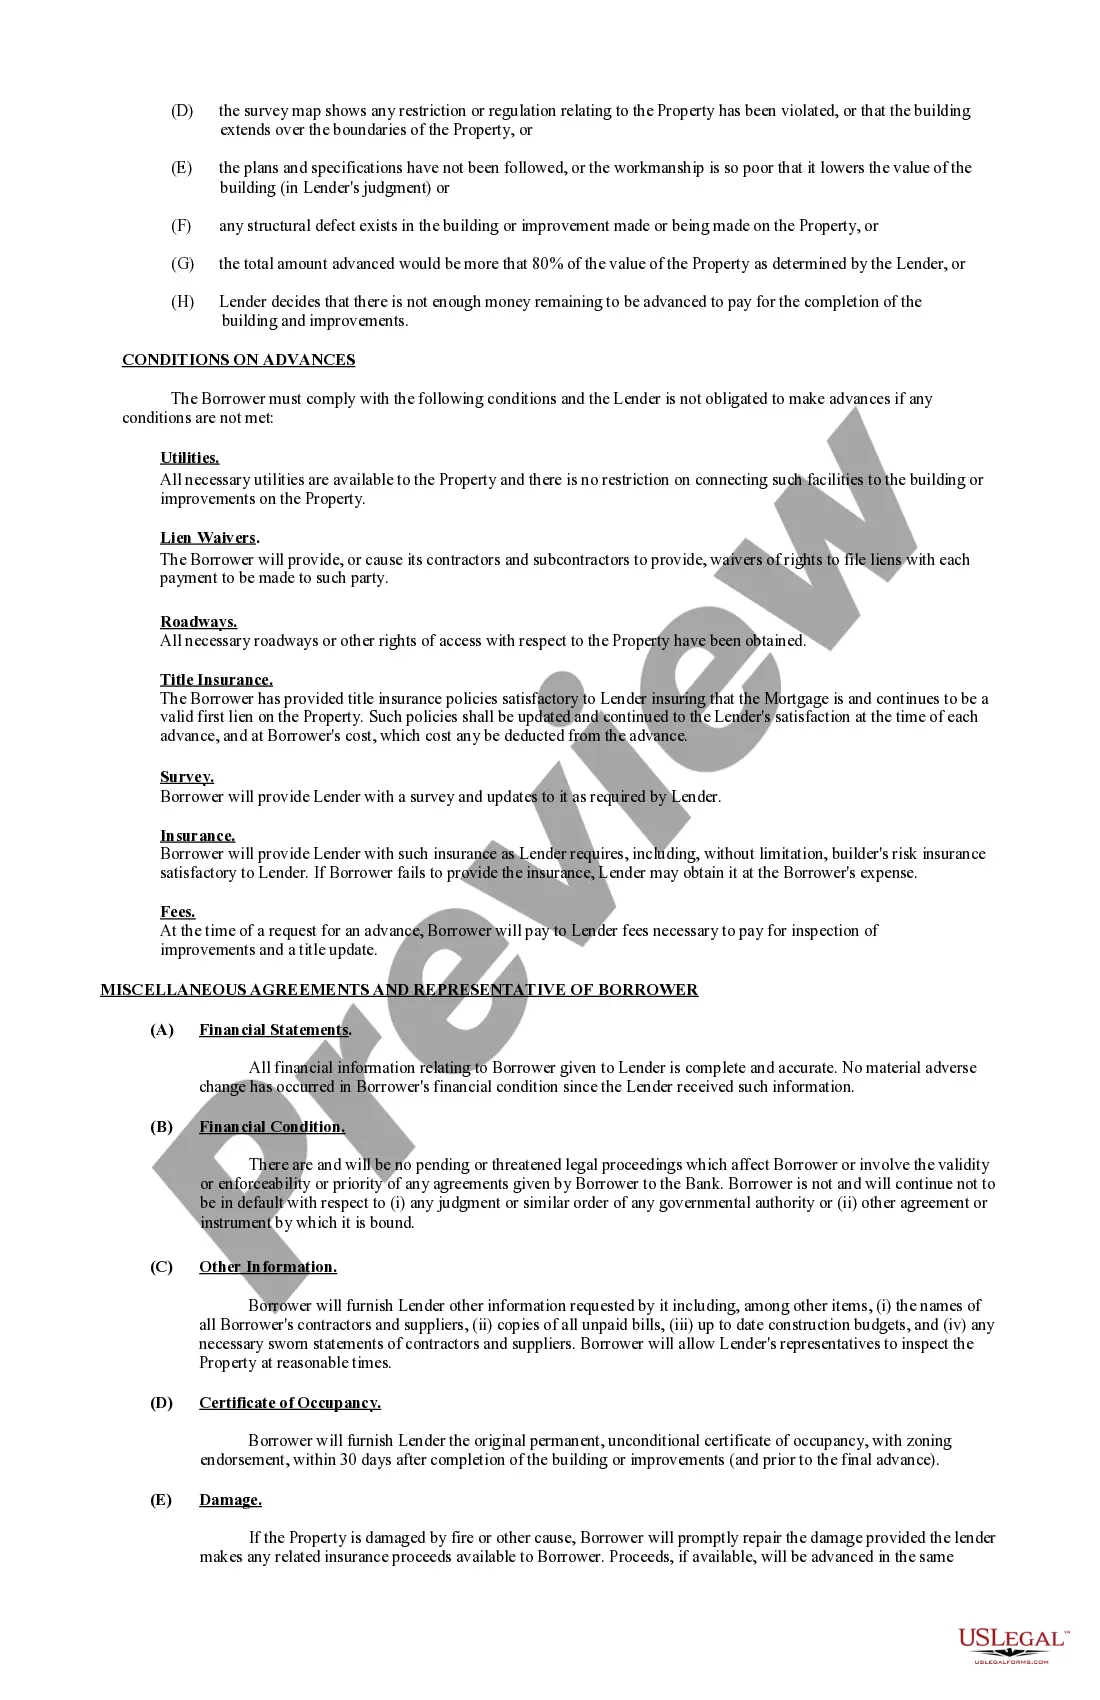
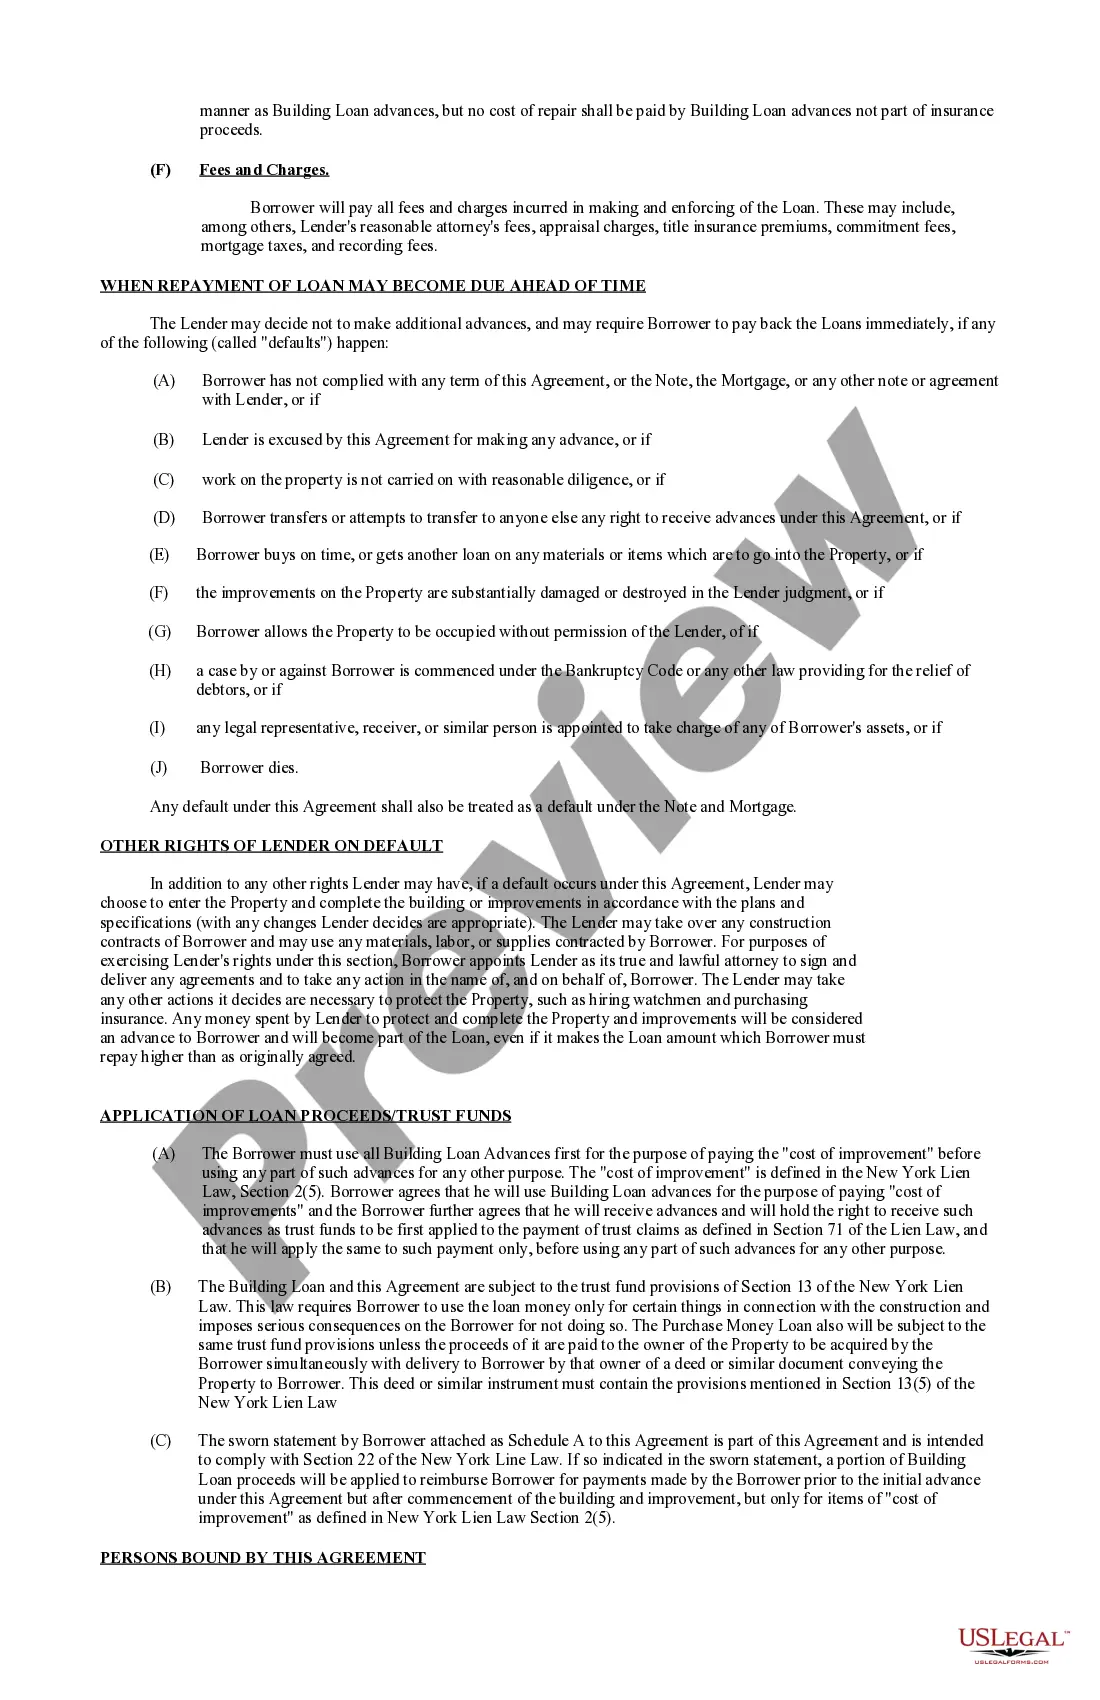
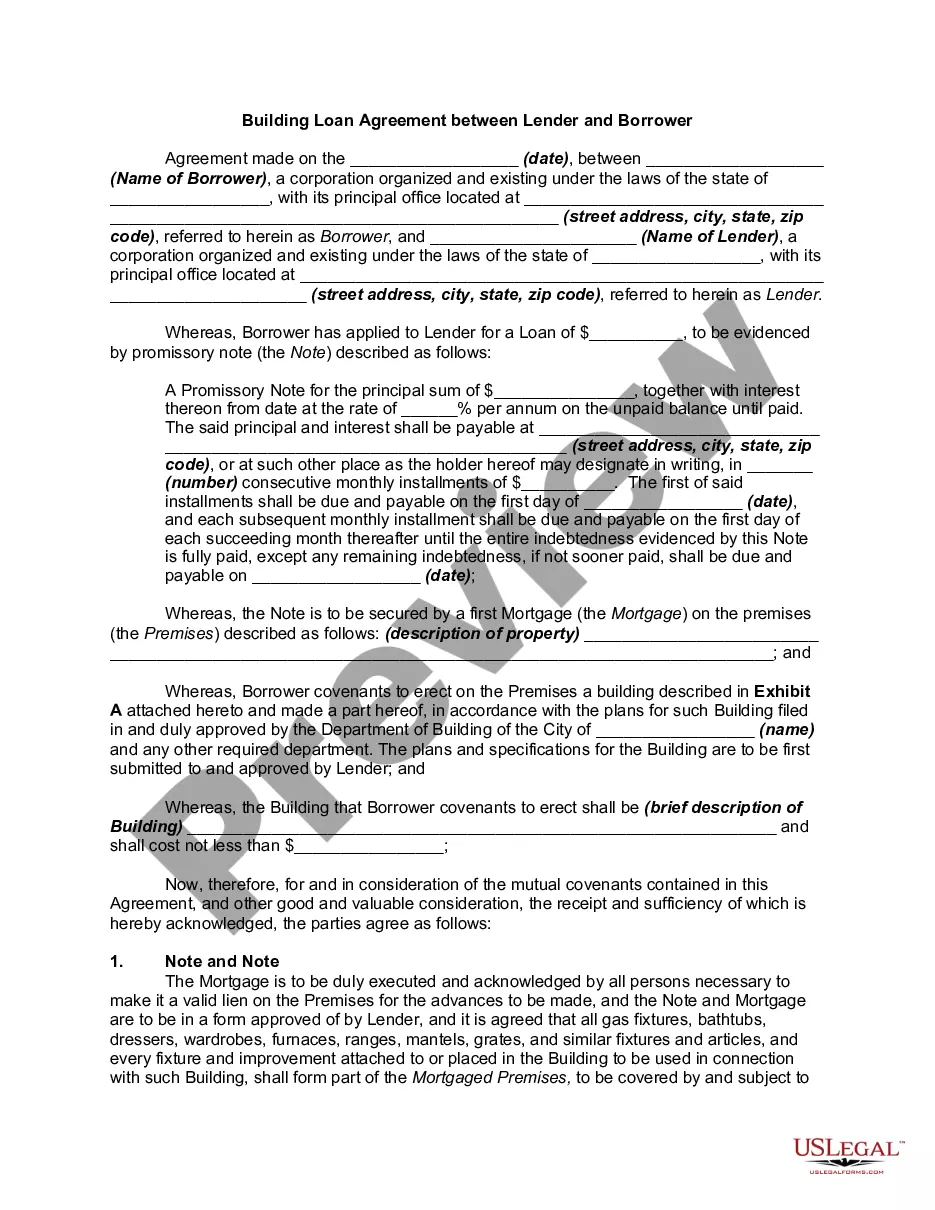
The building loan agreement is a legal document that outlines the terms under which a lender will provide financial support to a borrower for the construction of a specific property. Unlike a regular loan agreement, this form specifically details stages of funding tied to construction milestones, ensuring that the funds are used appropriately for improvements on the property.
Form components explained
- Agreement Details: Defines the parties involved, including the borrower and lender, and their responsibilities.
- Loan Information: Specifies the total loan amount, its usage, and the conditions under which funds will be released.
- Construction Agreement: Mandates that the construction must align with approved plans and legal requirements.
- Advance Schedule: Outlines how and when funds will be released during the construction process.
- Lien Clauses: Addresses the obligation to ensure the property remains free of liens during construction.
Situations where this form applies
This form should be utilized when an individual or entity plans to borrow money for the construction of a new building or significant improvement on an existing property. It is particularly useful in scenarios where funding is needed in stages, aligning with construction progress, and when there is a need to guarantee that the funds will be utilized solely for the intended construction purposes.
Who needs this form
- Property owners who are planning to construct new buildings or undertake significant renovations.
- Borrowers seeking financial assistance from banks or lending institutions specifically for construction purposes.
- Contractors or developers managing construction projects who require installment funding based on progress.
Steps to complete this form
- Identify the parties: Enter the names and addresses of both the borrower and the lender.
- Specify the property: Provide the legal description and address of the property being constructed.
- Enter loan details: Fill in the loan amount, specifying how much is allocated for the purchase and building costs.
- Outline construction plans: Attach and reference the approved plans and specifications for the construction project.
- Sign and date: Ensure all parties review the agreement, sign, and date the document to make it legally binding.
Notarization guidance
This form does not typically require notarization unless specified by local law. It is recommended to verify specific requirements in your jurisdiction to ensure legal validity.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Avoid these common issues
- Failing to provide a complete legal description of the property.
- Not specifying the correct amounts allocated for construction and acquisition.
- Overlooking necessary approvals for changes in construction plans.
- Neglecting to ensure that lien waivers are obtained with each payment made.
Why complete this form online
- Immediate access: Download and complete the form at your convenience without delays.
- Editability: Customize the document to suit specific requirements or circumstances.
- Legal reliability: All forms are drafted by licensed attorneys, ensuring compliance with current laws.
Quick recap
- This building loan agreement is crucial for borrowers seeking stage-based financing for construction projects.
- Proper completion of the form ensures that financial support is properly allocated and protected.
- Awareness of local state laws is vital, particularly those related to liens and construction contracts.
Looking for another form?
Form popularity
FAQ
Loan agreements are binding contracts between two or more parties to formalize a loan process.Loan agreements typically include covenants, value of collateral involved, guarantees, interest rate terms and the duration over which it must be repaid.
For loans by a commercial lender, the lender will provide the agreement. But for loans between friends or relatives, you will need to create your own loan agreement.
Starting the Document. Write the date at the top of the page. Write the Terms of the Loan. State the purpose of the personal payment agreement and the terms for returning the money. Date the Document. Statement of Agreement. Sign the Document. Record the Document.
(a) If funds are advanced to or on behalf of a trustee, for the purposes of the trust, either the trustee or the person advancing the funds may file a "Notice of Lending" as provided in this subdivision.Each such notice shall be indexed by the name of the trustee to whom or on whose behalf the advances are made.
For a personal loan agreement to be enforceable, it must be documented in writing and signed by both parties.
The purpose of a loan agreement is to detail what is being loaned and when the borrower has to pay it back as well as how.Once it has been executed, it is essentially a promise to pay from the lender to the borrower.
A loan agreement is a contract between a borrower and a lender which regulates the mutual promises made by each party.Loan agreements are usually in written form, but there is no legal reason why a loan agreement cannot be a purely oral contract (although oral agreements are more difficult to enforce).
The purpose of a loan agreement is to detail what is being loaned and when the borrower has to pay it back as well as how. The loan agreement has specific terms that detail exactly what is given and what is expected in return.
A personal loan agreement is a legally binding document regardless of whether the lender is a financial institution or another person.As a borrower, you could be sued by the lender or lose the asset or assets used to secure the loan.