New Jersey Assignment of Mortgage
Understanding this form
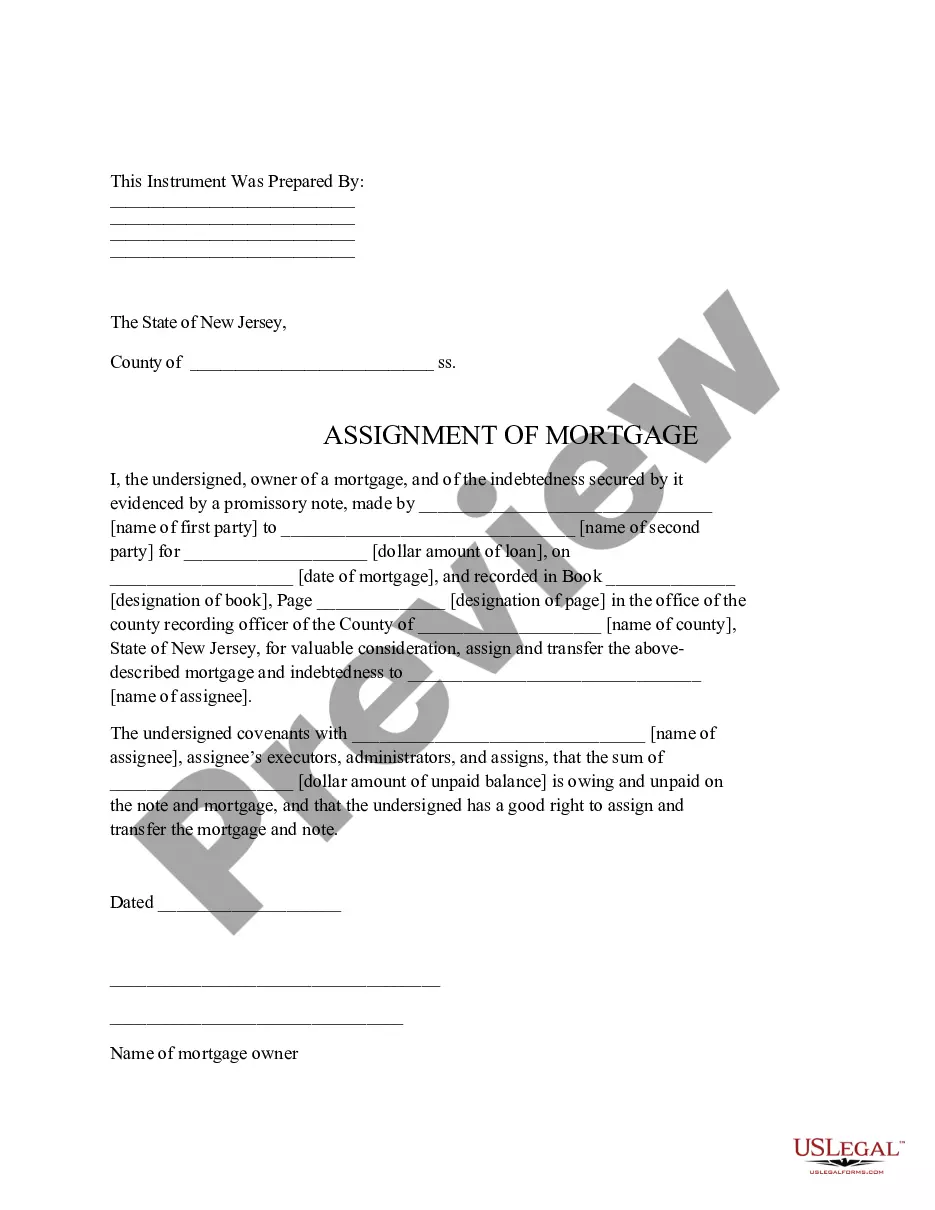
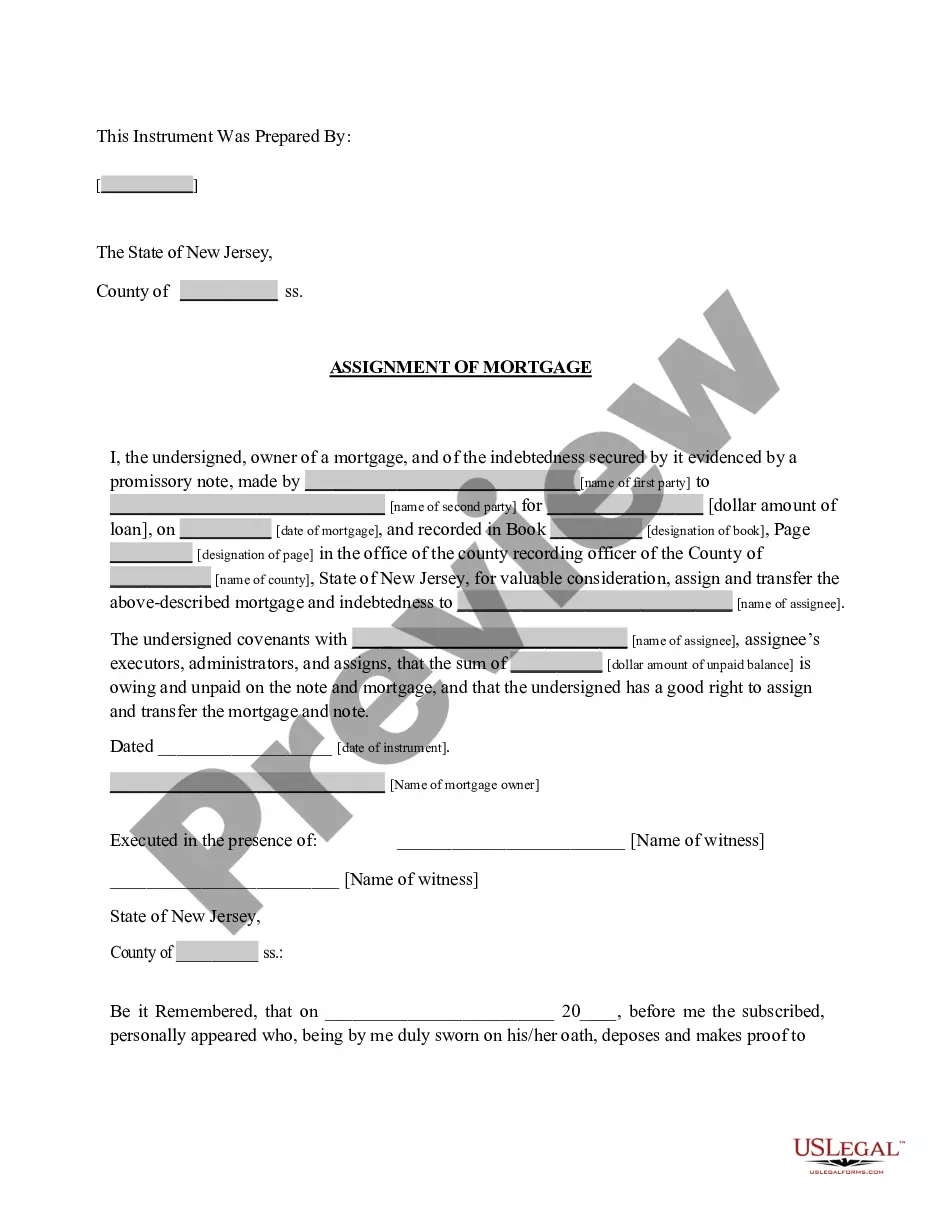
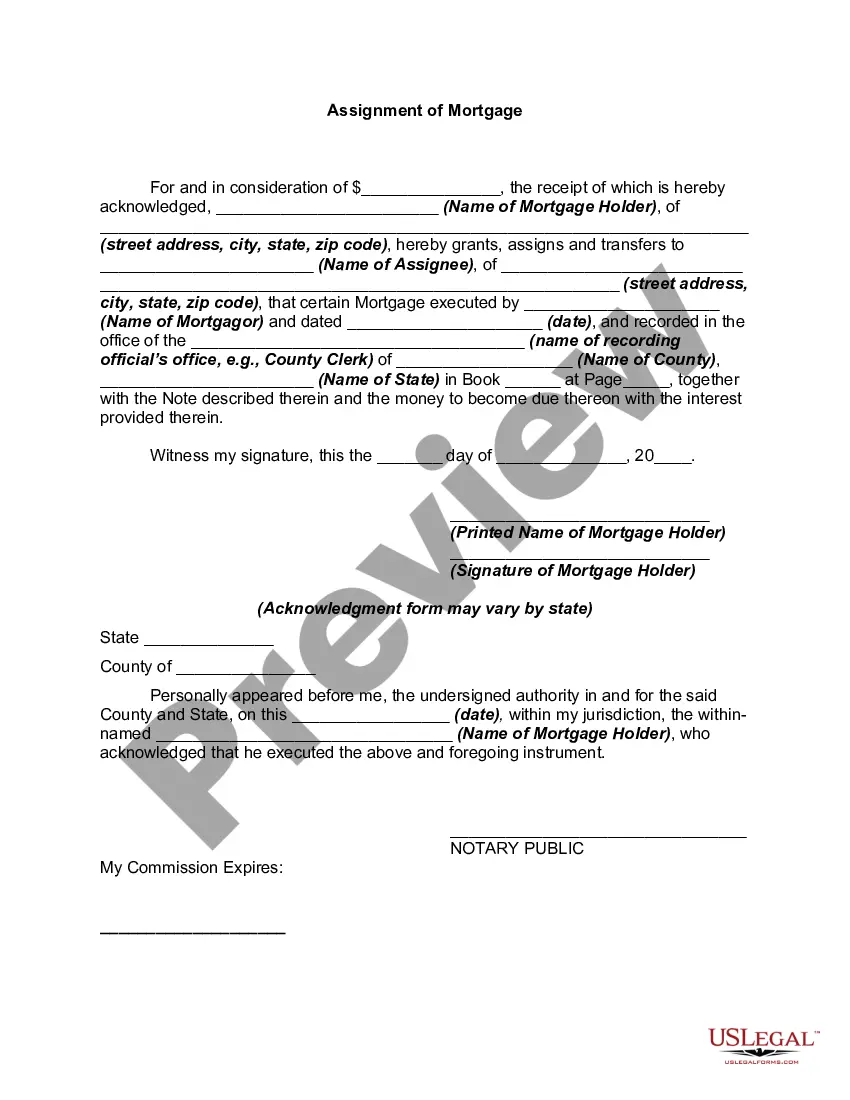
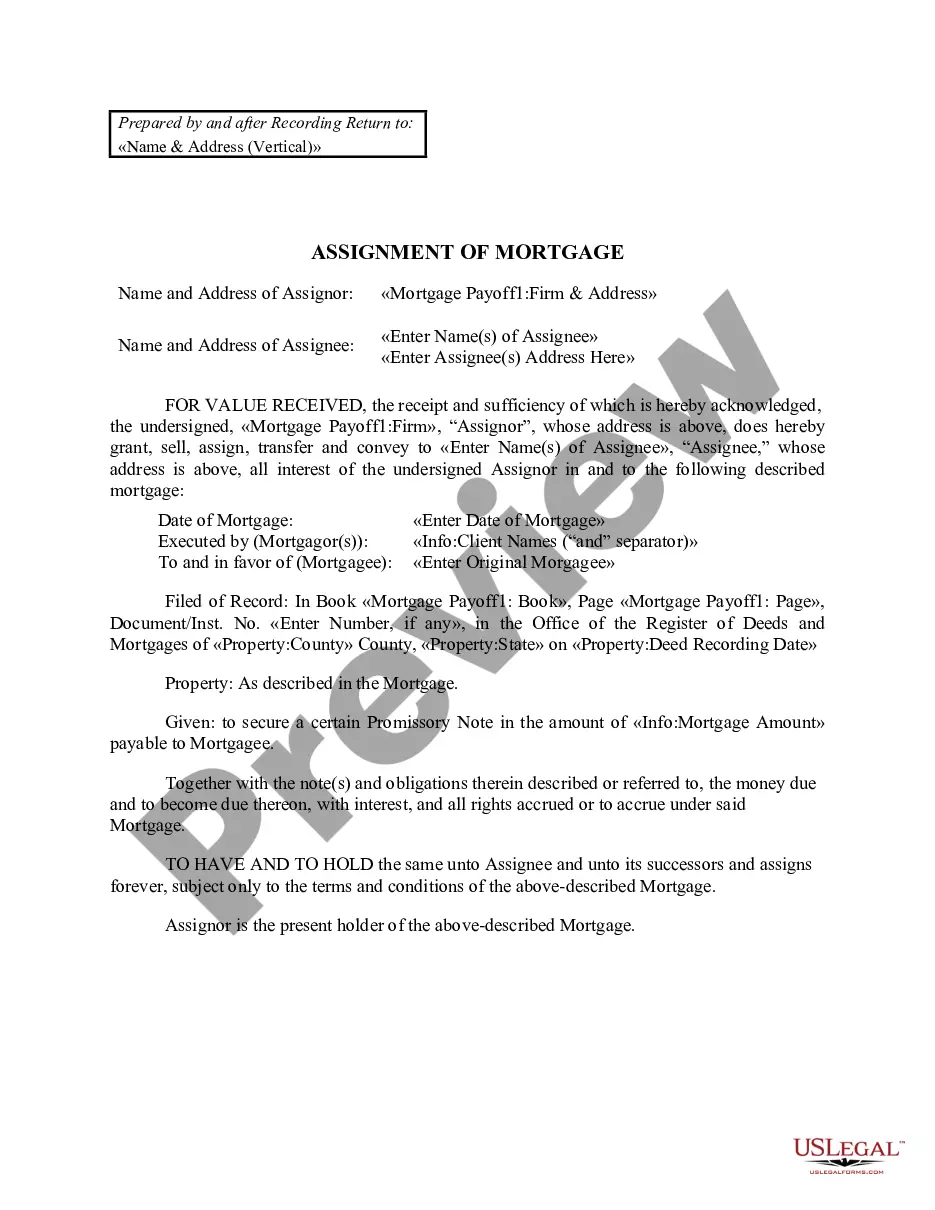
The Assignment of Mortgage is a legal document that allows the owner of a mortgage to transfer their interest in the mortgage to a third party. This form differs from other loan documents by specifically addressing the assignment and transfer of the mortgage obligation, ensuring that the third party assumes responsibility for the loan secured by the mortgage.
Key components of this form
- Names of the original mortgagor (borrower) and the mortgagee (lender).
- Details of the mortgage, including the loan amount and date of the mortgage.
- Legal description of the property securing the mortgage.
- Statement of the unpaid balance on the mortgage.
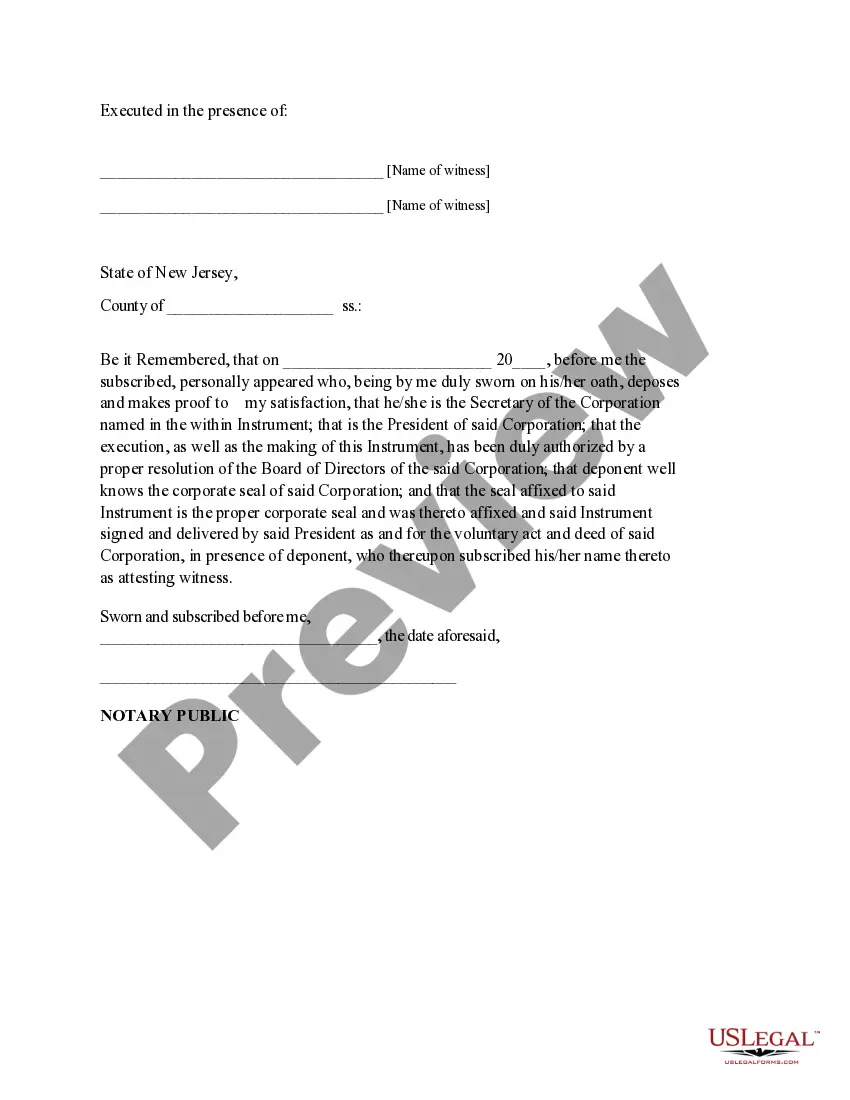
- Signatures of the mortgage owner and witnesses.
- Notary section to validate the assignment.

Common use cases
This form is typically used when the mortgage owner wishes to sell their interest in a mortgage to another party. Common scenarios include refinancing, transferring ownership to family members, or selling the mortgage as part of a financial settlement or investment strategy.
Who needs this form
- Mortgage holders looking to assign their mortgage to a third party.
- Real estate investors seeking to transfer mortgage assets.
- Individuals involved in estate planning or property succession.
- Companies or corporations needing to assign mortgage interests.
Steps to complete this form
- Identify the parties involved: the original mortgagor and the new assignee.
- Enter the details about the mortgage, including the loan amount and date.
- Specify the property that secures the mortgage in the designated fields.
- Provide the unpaid balance on the mortgage in the appropriate space.
- Sign the document in the presence of witnesses and a notary.
Notarization guidance
Yes, this form must be notarized to be legally valid. Notarization ensures that the signing parties are properly identified and that their signatures are authentic. US Legal Forms offers integrated online notarization services, providing a secure video call with a notary available 24/7, ensuring your document is legally compliant without the need for travel.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Typical mistakes to avoid
- Failing to fill in the complete property description.
- Not providing the correct unpaid balance on the mortgage.
- Omitting signatures from witnesses or the notary.
- Not capturing the date correctly when signing the form.
Why complete this form online
- Convenient access to a legally vetted template prepared by attorneys.
- Editable format allows for customization to fit specific needs.
- Quick download process saves time compared to other methods.
- Increased reliability by using standardized legal language.
Legal use & context
- This Assignment of Mortgage legally transfers the mortgage obligations from the original owner to the assignee.
- It is enforceable in a court of law when completed according to state regulations.
- Failure to assign the mortgage properly could lead to invalidation of the transfer.
Main things to remember
- The Assignment of Mortgage is essential for transferring mortgage rights to a third party.
- Proper completion and notarization are crucial for the document's validity.
- Consider using this form for estate planning or investment purposes.
Looking for another form?
Form popularity
FAQ
Once a loan has been assigned to MERS, it can be bought and sold any number of times later without recording assignments. Don't be surprised if you find out that your mortgage was assigned to MERS at some point. In most cases, the loan will have to be assigned out of MERS' name before a foreclosure can begin.
Assignment of Mortgage ? The Basics. When your original lender transfers your mortgage account and their interests in it to a new lender, that's called an assignment of mortgage. To do this, your lender must use an assignment of mortgage document. This document ensures the loan is legally transferred to the new owner.
A disadvantage of a mortgage assignment is the consequences of failing to record it. Under most state laws, an entity seeking to institute foreclosure proceedings must record the assignment before it can do so. If a mortgage is not recorded, the judge will dismiss the foreclosure proceeding.
An assignment of mortgage is a legal term that refers to the transfer of the security instrument that underlies your mortgage loan ? aka your home. When a lender sells the mortgage on, an investor effectively buys the note, and the mortgage is assigned to them at this time.
An assignment transfers all the original mortgagee's interest under the mortgage or deed of trust to the new bank. Generally, the mortgage or deed of trust is recorded shortly after the mortgagors sign it, and, if the mortgage is subsequently transferred, each assignment is recorded in the county land records.
An assignment of mortgage is a legal term that refers to the transfer of the security instrument that underlies your mortgage loan ? aka your home. When a lender sells the mortgage on, an investor effectively buys the note, and the mortgage is assigned to them at this time.
If the mortgagee fails to execute and record a Satisfaction of Mortgage within the 60-day period afforded by statute, the mortgagor (property owner) may file suit and seek a court order directing the mortgagee to execute a satisfaction of mortgage or an order extinguishing the lien against the property.