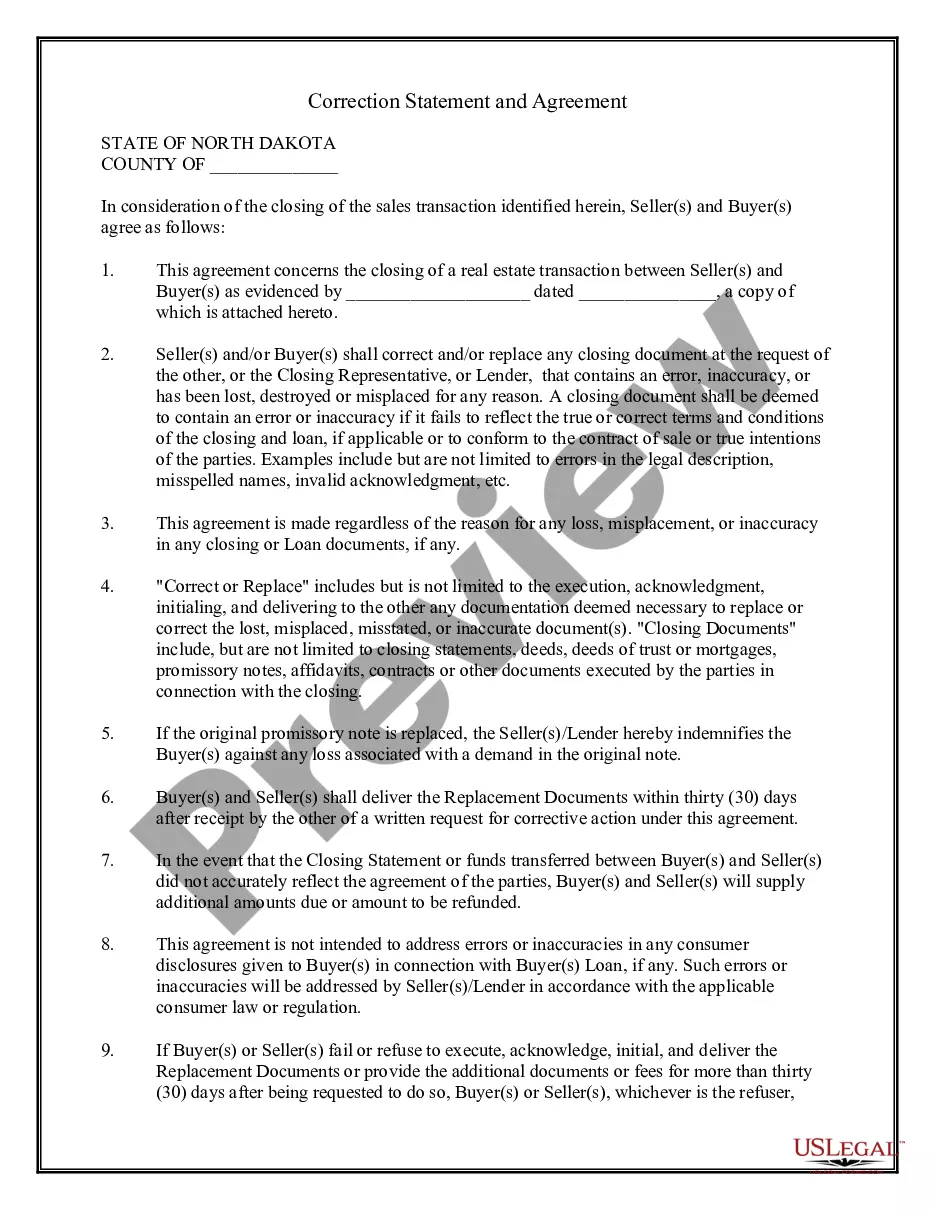
Nebraska Assumption of Land Use Restriction Agreement for Low Income Housing Tax Credits
About this form
The Assumption of Land Use Restriction Agreement for Low Income Housing Tax Credits is a legal document used when an individual buys a rental housing development that has a pre-existing land use restriction agreement related to low-income housing tax credits. This form outlines the new owner's agreement to assume the responsibilities and obligations of the previous owner under the original agreement, ensuring continued compliance with applicable laws and regulations regarding the property's use as low-income housing.
What’s included in this form
- Date of the agreement and identification of the parties involved.
- Details of the prior land use restriction agreement and its recording information.
- Assumption clause where the new owner agrees to take on the obligations of the prior owner.
- Amendment of notices including the address for the owner.
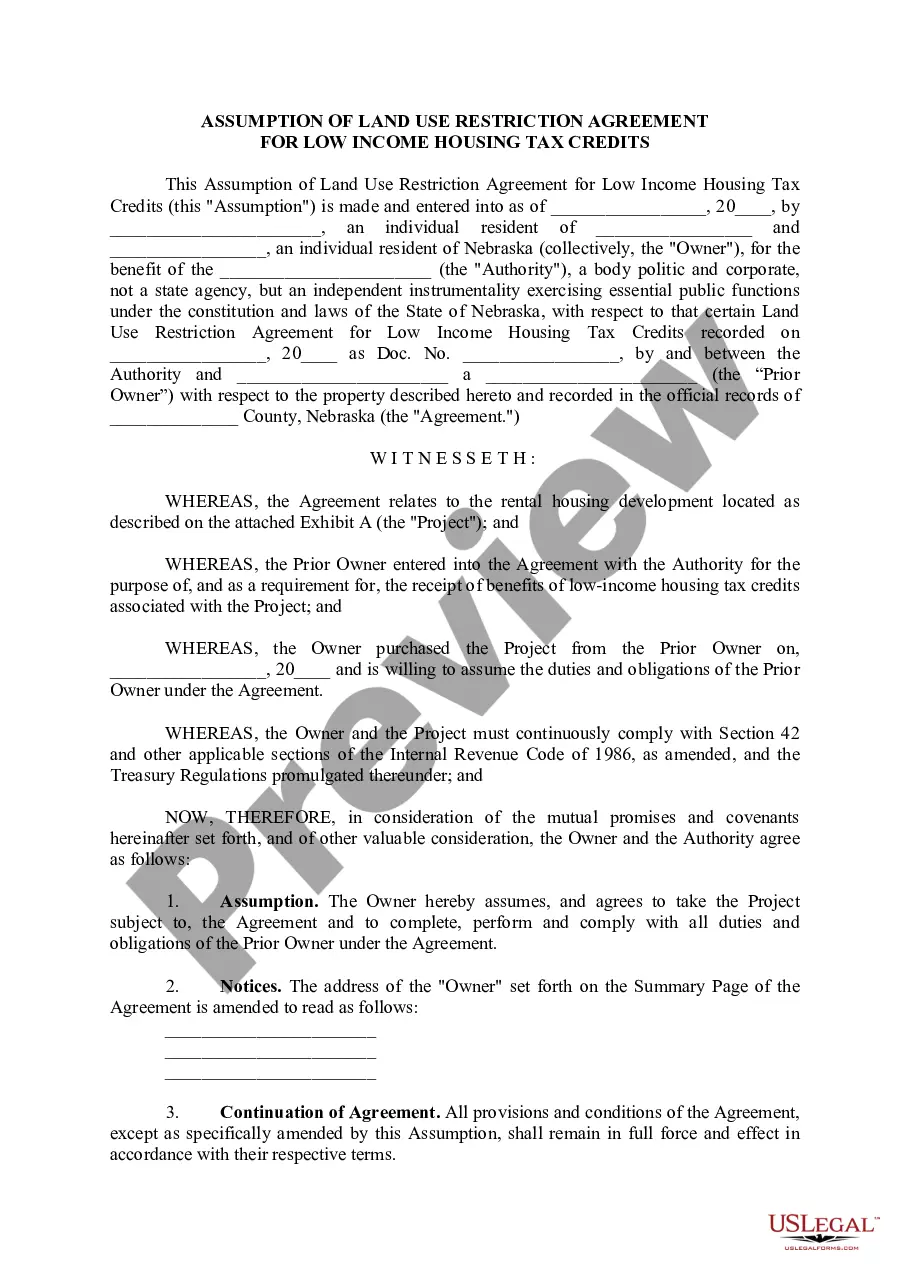
- Governing law provisions specifying the applicable jurisdiction.
- Requirements for recording the agreement with local public records.
When this form is needed
This form should be used when an individual purchases a rental housing project that is already under a land use restriction agreement associated with low-income housing tax credits. It is essential to ensure that the new owner officially accepts the duties of compliance related to affordable housing regulations as a condition for retaining the tax credits.
Who should use this form
- Individuals or entities purchasing rental housing developments eligible for low-income housing tax credits.
- Real estate professionals involved in the sale and purchase of such properties.
- Government entities engaged with affordable housing issues and financing.
- Previous owners transferring obligations as part of a sale agreement.
How to prepare this document
- Identify and fill in the date of the agreement and the names and addresses of the new owners.
- Reference the original land use restriction agreement, including its recording details.
- Complete the assumption clause, affirming the new owner's acceptance of obligations under the original agreement.
- Update the address of the new owner in the notices section.
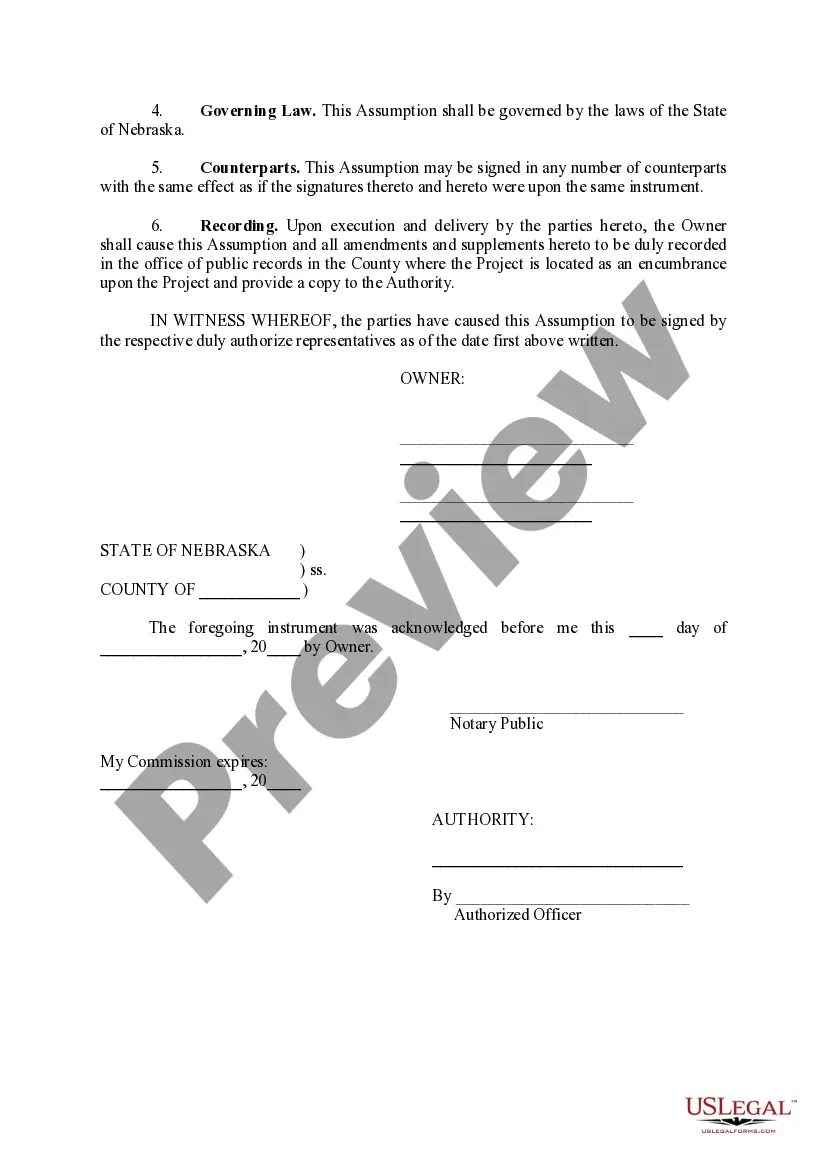
- Sign the document before a notary public and arrange for recording it with local public records.
Notarization requirements for this form
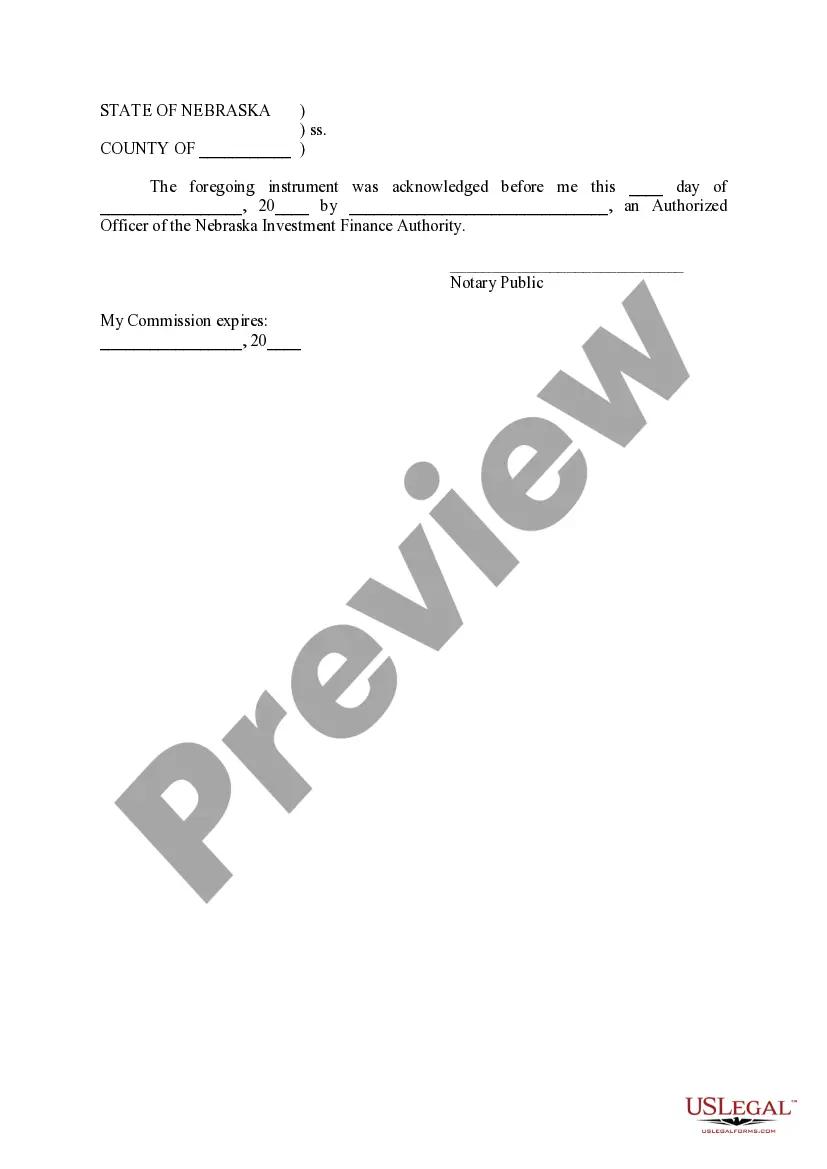
Yes, this form must be notarized to be legally valid. It requires signatures from the owners and an authorized officer from the Authority in the presence of a notary public. US Legal Forms provides integrated online notarization services, allowing you to easily notarize documents via secure video calls, available 24/7.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Common mistakes to avoid
- Failing to provide complete details of the prior land use restriction agreement.
- Not updating the ownerâs address information accurately.
- Omitting signatures or notary acknowledgments, which can invalidate the form.
Benefits of using this form online
- Instant access to downloadable and editable legal forms drafted by licensed attorneys.
- Convenience of completing forms at your own pace without the need for an in-person appointment.
- Reliable templates that ensure compliance with the latest legal standards.
Legal use & context
- This form ensures that the new owner is legally bound to fulfill the obligations necessary to maintain low-income housing tax credits.
- Proper completion and recording of this document help prevent potential legal disputes over compliance issues in the future.
What to keep in mind
- The Assumption of Land Use Restriction Agreement is crucial for transferring obligations related to low-income housing tax credits.
- Accurate completion and notarization of the form are vital for its legal standing.
- This form is specific to Nebraska, outlining unique state compliance requirements.
Looking for another form?

Form popularity
FAQ
You may also hear the program referred to as either the low-income housing tax credit program or the rental housing tax credit program. This is because Section 42 is an affordable housing program established by the federal tax code that allows developers of affordable housing to receive a federal tax credit.
The tenant rent equals unit's gross rent minus the utility allowance. A studio/efficiency is 30 percent of a project's one person income limit. A one-bedroom unit is 30 percent of a project's income limit for 1.5 persons, calculated by averaging the one and two person income limits.
LIHTC rents are calculated to include a utility allowance for tenant-paid utilities. LIHTC rents are set at 30% of the income of the AMI tied to the unit.To calculate the income of 1.5 people the owner will average the AMI of a one person household ($68,300) with the AMI of a two person household ($78,000).
Under the 20-50 test, at least 20% of the units in a LIHTC project must be both rent-restricted and occupied by tenants whose gross income is 50% or less of the area median gross income (AMGI). The percentages are 40% and 60%, respectively, if a taxpayer elects to use the 40-60 test.
Definition: A tax credit property is an apartment complex owned by a landlord who participates in the federal low-income housing tax credit program. These landlords get to claim tax credits for eligible buildings in return for renting some or all of the apartments to low-income tenants at a restricted rent.
Section 42 Tax Credit: This tax credit encourages developers to build affordable housing to meet the needs of the community. As a condition for receiving Housing Tax Credits, owners must keep the units affordable for a specified number of years.
HUD simultaneously released Multifamily Tax Subsidy Program income limits for 2020, which are used to determine eligibility for low-income housing tax credit and tax-exempt bond properties. The FY 2020 national median income is $78,500, an increase of nearly 4 percent over 2019.
An agreement between a property owner and the government whereby the property owner agrees to limit the use of its property in exchange for some pre-determined tax credits or bond financings.
The LIHTC is designed to subsidize either 30 percent or 70 percent of the low-income unit costs in a project. The 30 percent subsidy, which is known as the so-called automatic 4 percent tax credit, covers new construction that uses additional subsidies or the acquisition cost of existing buildings.