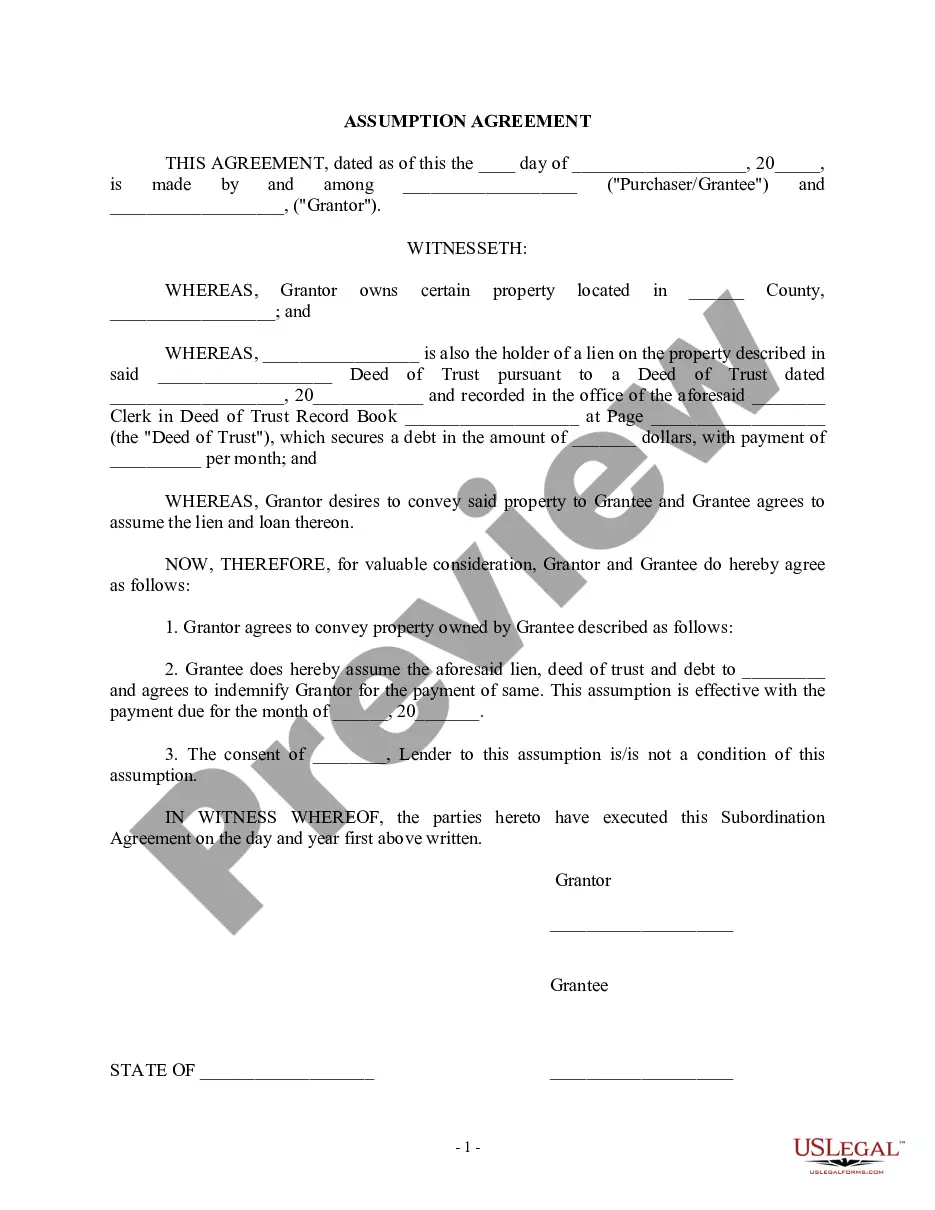
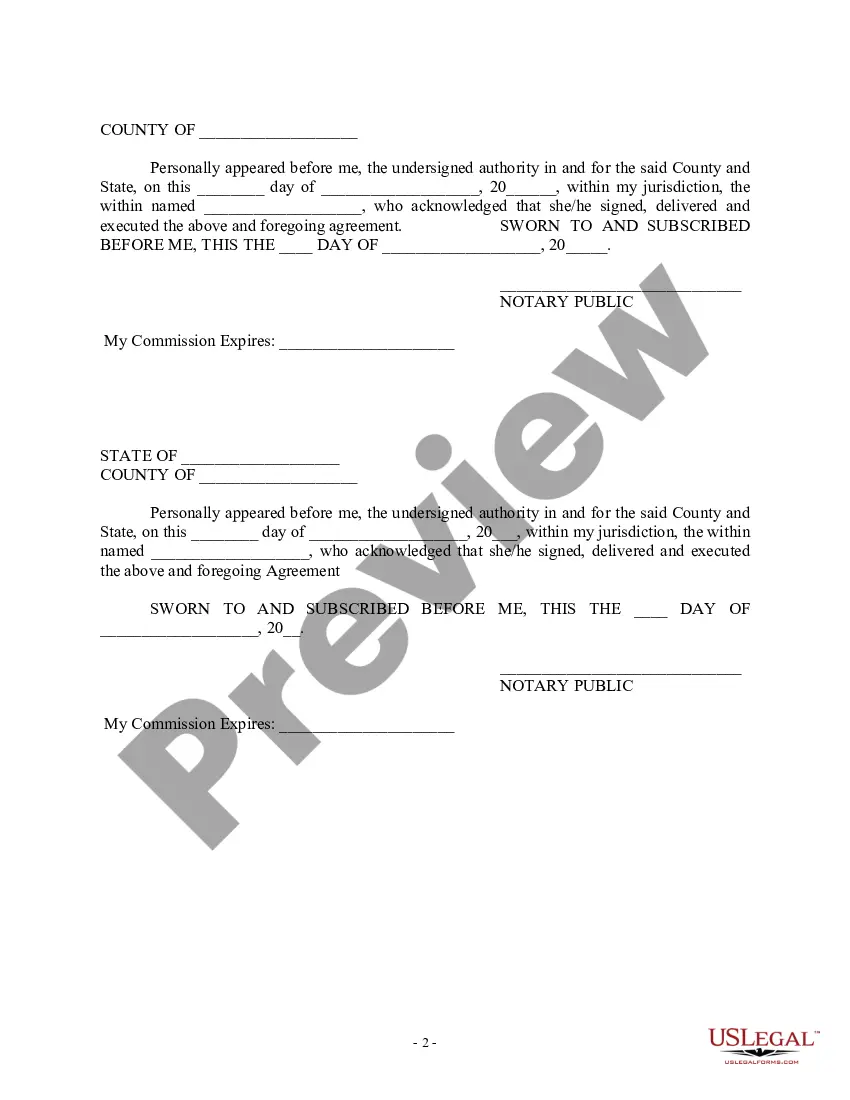
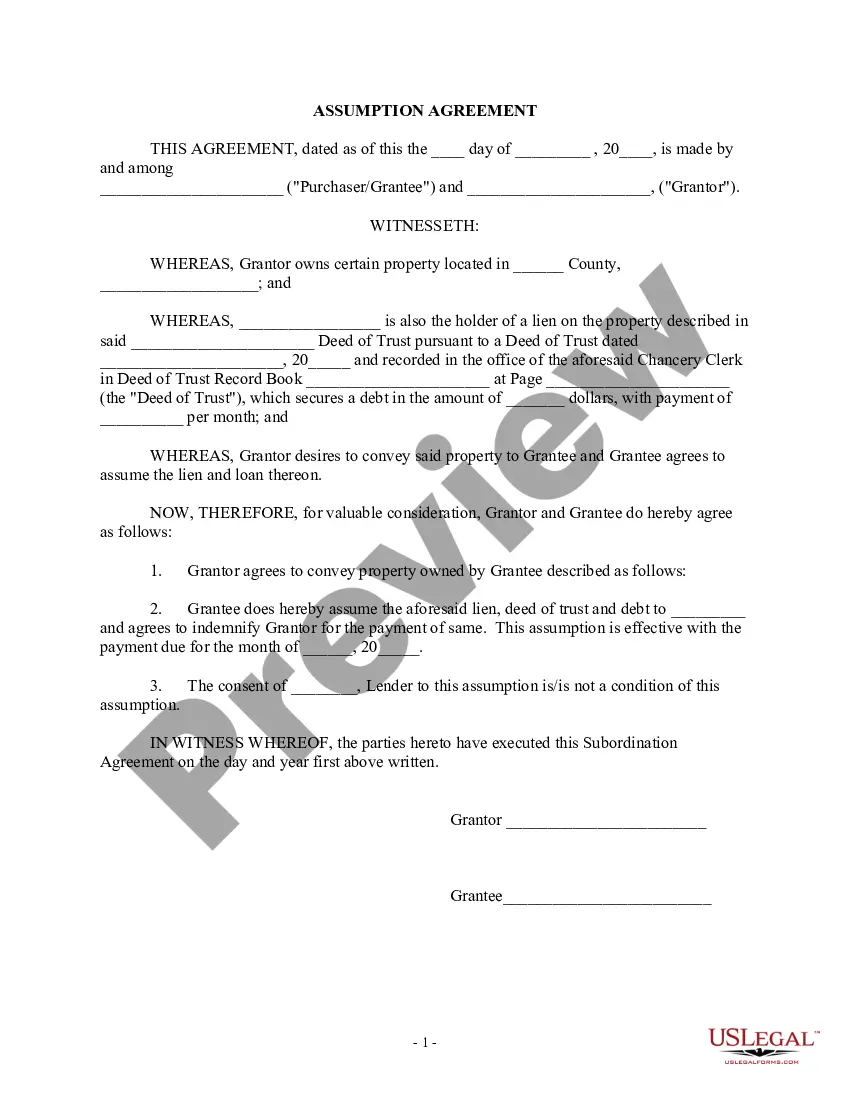
Loan Assumption Agreement Divorce With Bank
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
How to fill out Loan Assumption Agreement?
Managing legal documents can be exasperating, even for the most proficient professionals.
When you are looking for a Loan Assumption Agreement Divorce With Bank and do not have the opportunity to spend time on finding the correct and current version, the process may become strenuous.
Utilize a resource bank of articles, guides, handbooks, and materials relevant to your situation and requirements.
Save time and effort looking for the documents you need, and use US Legal Forms’ enhanced search and Review feature to locate the Loan Assumption Agreement Divorce With Bank and acquire it.
Ensure that the template is accepted in your state or county. Choose Buy Now when you are ready. Select a subscription option. Find the format you require, and Download, fill out, sign, print, and send your documents. Take advantage of the US Legal Forms web catalog, backed by 25 years of experience and reliability. Streamline your everyday document management into a straightforward and user-friendly process today.
- If you have a subscription, Log In to the US Legal Forms account, search for the form, and download it.
- Check your My documents tab to review the documents you have previously acquired and manage your folders as you wish.
- If it is your first time using US Legal Forms, create a complimentary account for full access to all platform benefits.
- Here are the steps to follow after you have downloaded the necessary form.
- Confirm that this is the correct form by previewing it and reviewing its details.
- Access state- or county-specific legal and business forms.
- US Legal Forms addresses any needs you may have, ranging from personal to business documents, all in one location.
- Use sophisticated tools to fill out and manage your Loan Assumption Agreement Divorce With Bank.
Form popularity
FAQ
Yes, Wells Fargo does allow mortgage assumptions under certain conditions. However, they may require the new borrower to meet specific credit and income criteria as part of the loan assumption agreement divorce with bank. It is advisable to contact your Wells Fargo representative for detailed guidelines and to ensure you follow the correct procedure. Understanding these conditions will help you make informed decisions during your divorce process.
When considering a loan assumption agreement divorce with bank, it is essential to evaluate potential drawbacks. One catch is that the original borrower remains liable for the mortgage if the new borrower defaults. Additionally, lenders may require a thorough credit check or approval process, which can delay the assumption. To ensure a smooth transition, consult with professionals who understand the intricacies of these agreements.
While mortgage assumption can be beneficial, there are drawbacks to consider. For example, the original loan terms may not be favorable to the new borrower, especially if interest rates have increased. Furthermore, during a loan assumption agreement divorce with bank, lingering financial obligations can complicate future buying decisions. Weighing these pros and cons is essential for making informed choices.
An assumable mortgage typically requires that the new borrower meets the lender's financial criteria. Additionally, the original loan must be designed for assumption, such as FHA or VA loans. If you're dealing with a loan assumption agreement divorce with bank, ensure all parties understand their responsibilities and the financial implications. Consulting with professionals can provide vital guidance through this process.
The rules for mortgage assumption generally require lenders to approve the new borrower. The original mortgage must be an assumable loan, which not all loans are. In cases of a loan assumption agreement divorce with bank, both parties should review these rules carefully to avoid complications during the transfer of the mortgage. Always seek clarity on any obligations that will continue after the assumption.
Yes, Freddie Mac does allow assumptions under certain conditions. Typically, this means that the buyer must meet specific credit and income qualifications. For individuals navigating a loan assumption agreement divorce with bank, understanding these guidelines can help streamline the process. Always consult with a loan officer to explore your specific options and requirements.
The terms of a mortgage assumption typically include keeping the original loan amount and payment schedule. Lenders often require the new borrower to qualify for the loan under their criteria. In the context of a loan assumption agreement divorce with bank, this means both parties must be aware of the legal and financial responsibilities attached to the mortgage. Clear communication helps ensure the transition is smooth.
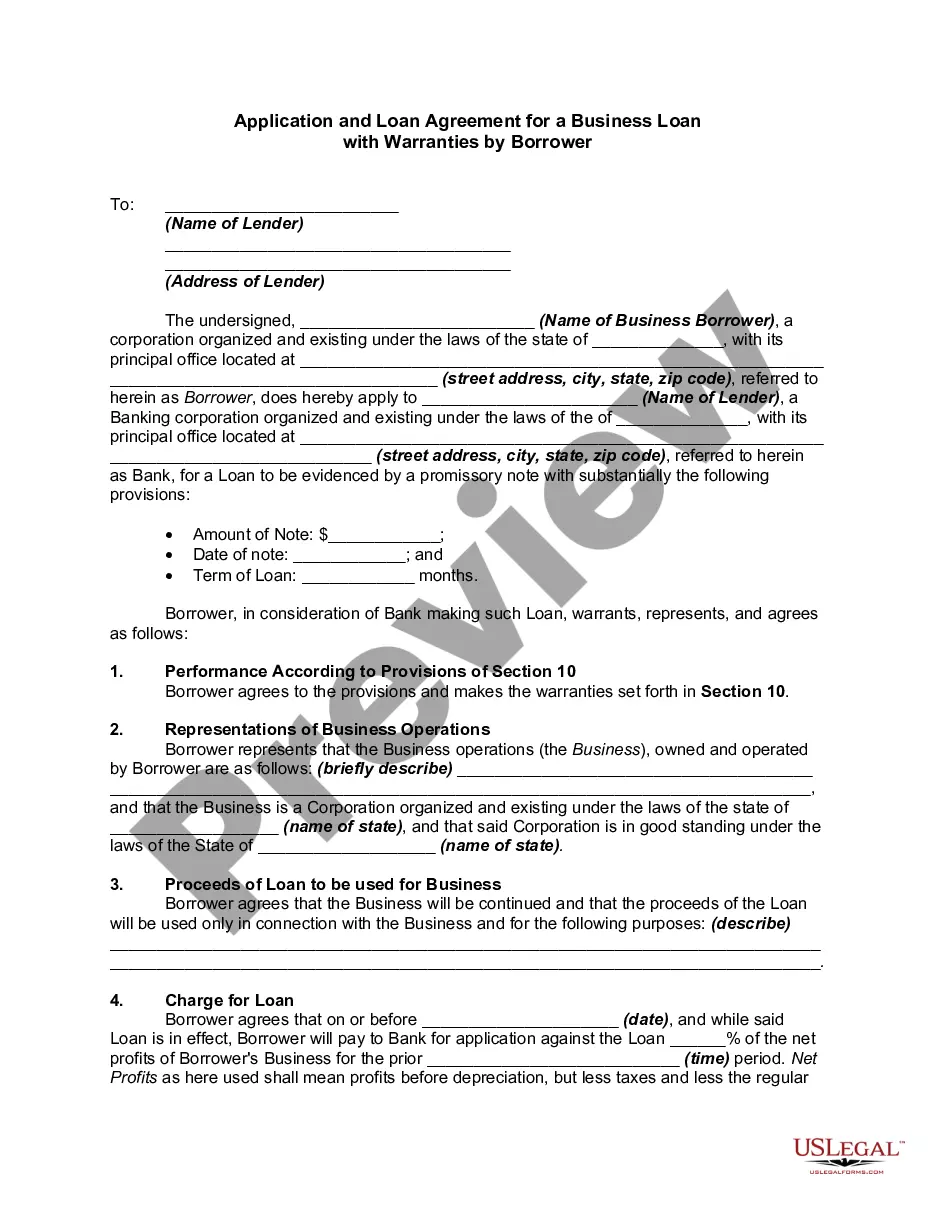
To complete a simple assumption, you must first review your loan agreement and contact your lender to discuss their policy on loan assumptions. In the context of a loan assumption agreement divorce with bank, you may need both parties to agree and provide necessary documentation. Once the lender approves it, you can finalize the agreement by signing the assumption document. This process highlights the importance of clear communication and proper legal documentation to ensure a smooth transition.
A simple assumption agreement is a legal document that allows one party to take over another party's loan obligations, typically found in divorce situations. When you are navigating a loan assumption agreement divorce with bank, this process can ease the financial burden by transferring responsibility to the assuming party. The document outlines the terms of the agreement, ensuring that all parties understand their rights and obligations. This clarity is crucial in any divorce, especially when financial decisions are at stake.
Yes, you can assume a mortgage after divorce, provided the lender allows it. A loan assumption agreement divorce with bank can facilitate this process, enabling one partner to take over the mortgage entirely. This can simplify financial arrangements and create clarity for both parties. Always check with your lender about their specific requirements for assuming a mortgage after a divorce.