Annual Meeting Corporate Withholding In Pennsylvania
Description
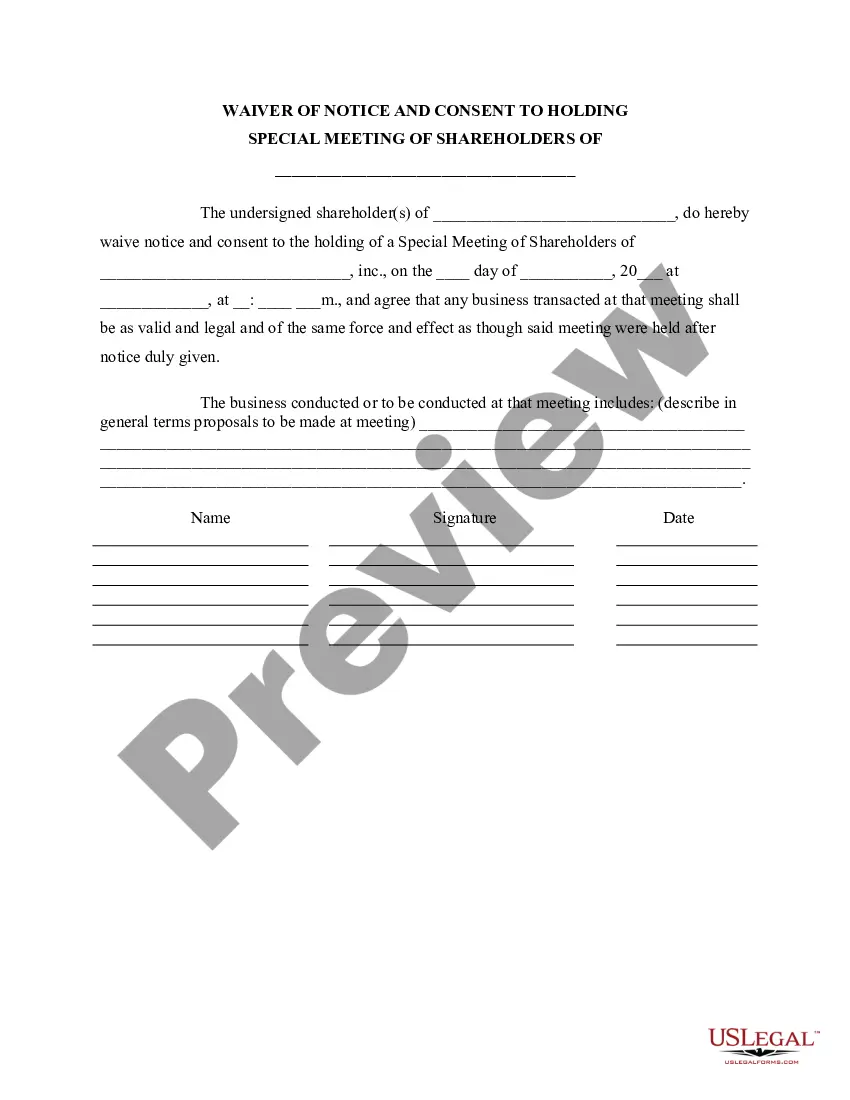
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
Form popularity
FAQ
Your Income Taxes Breakdown TaxMarginal Tax RateEffective Tax Rate Federal 12.00% 8.18% FICA 7.65% 7.65% State 3.07% 3.07% Local 1.20% 1.20%4 more rows
Pennsylvania law requires employers to withhold Pennsylvania personal income tax from employees' compensation in two common cases: When resident employees perform services within or outside Pennsylvania; and. When nonresident employees perform services within Pennsylvania.
Employers with worksites located in Pennsylvania, including residences of home-based employees, are required to withhold and remit the local EIT and LST for employees.
Pennsylvania law requires withholding at a rate of 3.07 percent on non-wage Pennsylvania source income payments made to nonresidents. Withholding of payments that are less than $5,000 during the calendar year are optional and at the discretion of the payor.
Pennsylvania's corporate net income tax rate remains on a downward trajectory, decreasing from 8.99 percent in 2023 to 8.49 percent in 2024.
Exemption from withholding To qualify for this exempt status, the employee must have had no tax liability for the previous year and must expect to have no tax liability for the current year. A Form W-4 claiming exemption from withholding is valid for only the calendar year in which it's furnished to the employer.
Pennsylvania Annual Report Service & Filing Instructions. Starting 2025, all Pennsylvania corporations, nonprofits, non-professional LLCs, and LPs will need to file an Annual Report with the Pennsylvania Department of State, Bureau of Corporations and Charitable Organizations.
Every resident, part-year resident or nonresident individual must file a Pennsylvania Income Tax Return (PA-40) when he or she realizes income generating $1 or more in tax, even if no tax is due (e.g., when an employee receives compensation where tax is withheld).
Corporations subject to the Corporate Net Income Tax (excluding PA S Corporations that have Built-In-Gains) must continue to file the RCT-101 annually.