USLF Multistate Elder and Retirement Law Handbook - Guide
Overview of this form
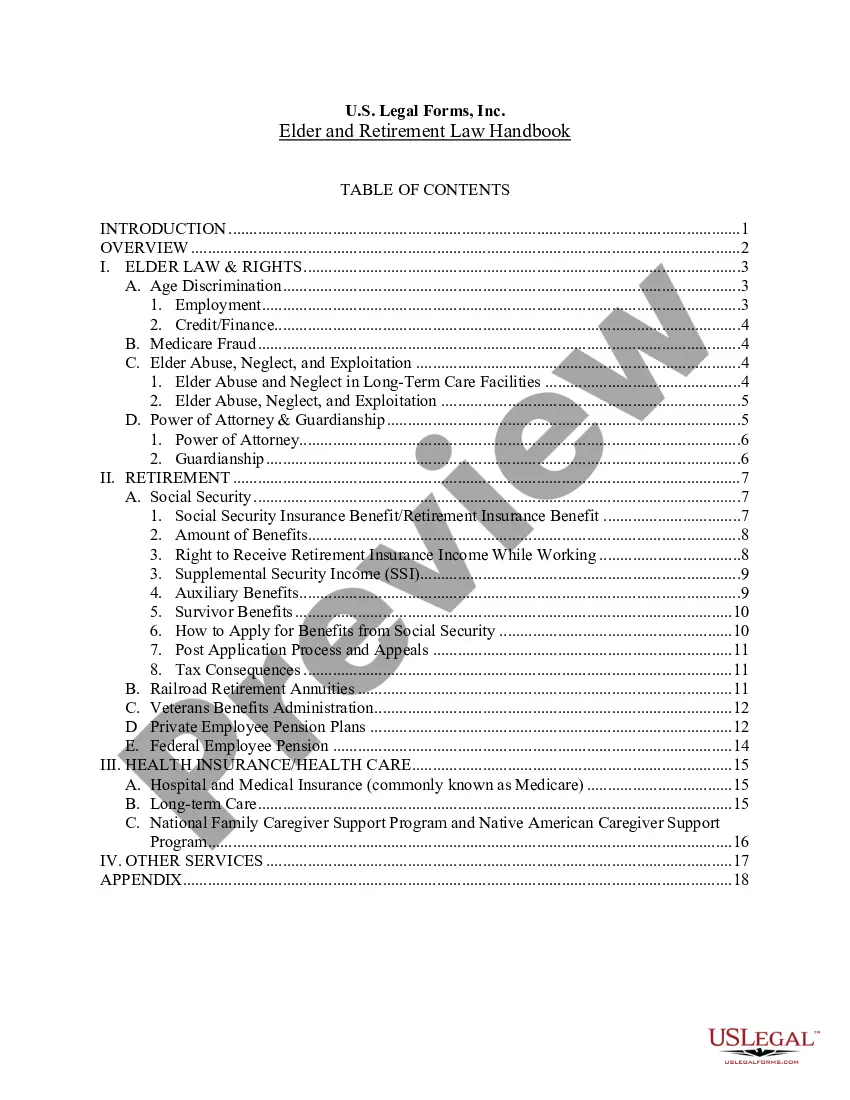
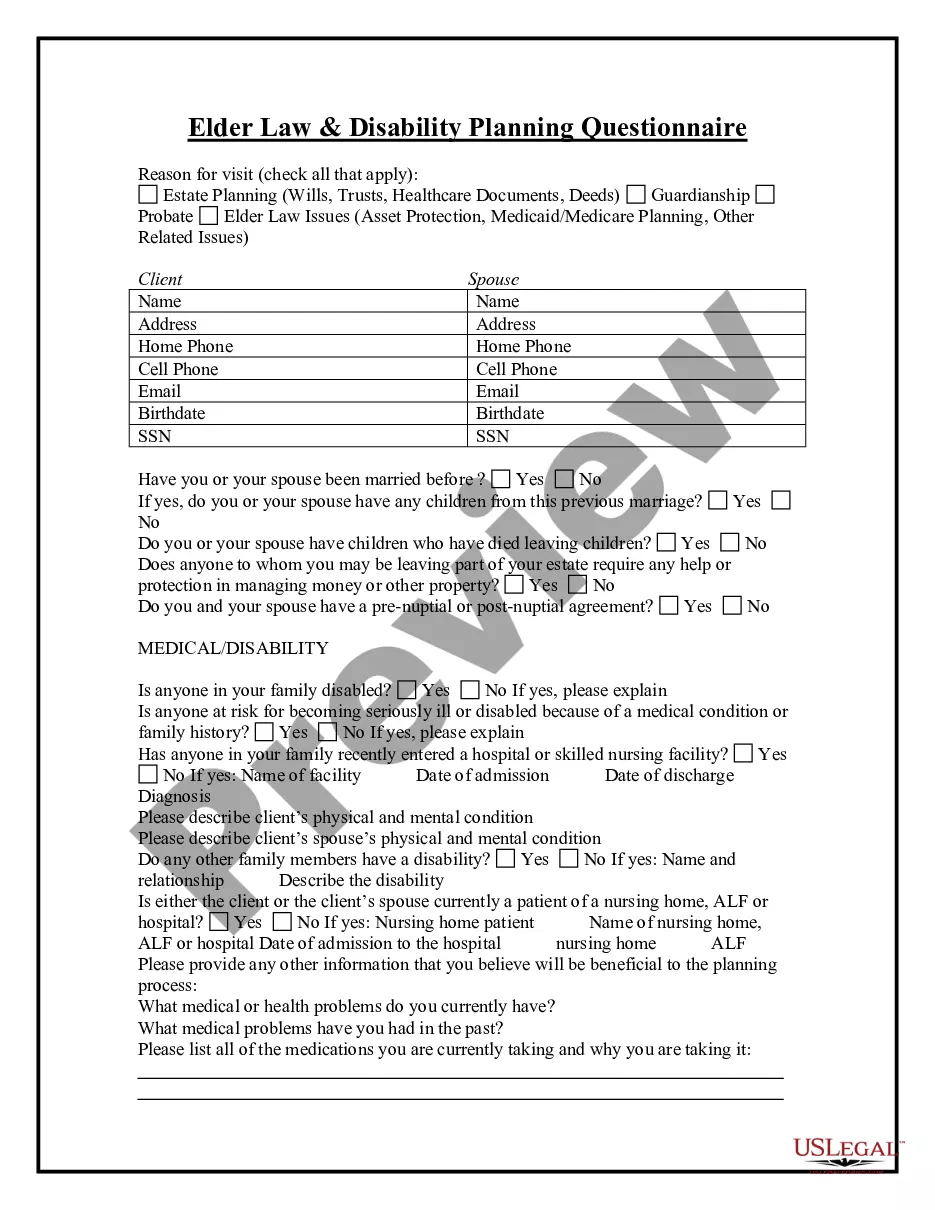
The USLF Multistate Elder and Retirement Law Handbook is a comprehensive guide designed to inform senior citizens about their rights and protections under federal laws concerning elder and retirement issues. Unlike other legal forms, this handbook serves as an educational resource, providing insights into topics like age discrimination, elder abuse, power of attorney, Social Security benefits, Medicare, and more.
Form components explained
- Comprehensive overview of elder law rights
- Information on Medicare and Social Security programs
- Guidelines for dealing with elder abuse and exploitation
- Details on power of attorney and guardianship
- Access to additional support services for seniors
When this form is needed
This handbook is essential for seniors who want to understand their rights and the resources available to them. It is particularly useful in situations where an elder may be facing discrimination, abuse, or confusion regarding their retirement benefits, healthcare options, or legal representation needs.
Who needs this form
- Senior citizens seeking information about their legal rights
- Family members or caregivers of elderly individuals
- Individuals preparing for retirement or navigating retirement benefits
- Those experiencing elder abuse or discrimination
- Legal professionals assisting clients with elder law issues
Instructions for completing this form
- Read through the entire handbook to understand elder law topics.
- Identify sections relevant to your personal situation or concerns.
- Make notes of any specific laws or rights mentioned that apply to you.
- Consult with a legal professional when necessary for specific advice.
- Contact appropriate agencies or organizations listed in the appendix for further assistance.
Does this document require notarization?
This form does not typically require notarization to be legally valid. However, some jurisdictions or document types may still require it. US Legal Forms provides secure online notarization powered by Notarize, available 24/7 for added convenience.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Mistakes to watch out for
- Overlooking important sections related to personal circumstances.
- Assuming handbook information replaces legal advice from an attorney.
- Ignoring local variations in laws that may affect your rights.
- Failing to seek help from agencies or legal services when needed.
Benefits of using this form online
- Immediate access to critical information without waiting for traditional mail.
- Ability to download and print the handbook for personal use.
- Easy navigation to relevant sections allows for targeted information retrieval.
- Convenient reference material for discussions with family or legal professionals.
Legal use & context
- The handbook serves educational purposes and does not constitute legal advice.
- Information complies with federal laws but may vary by state.
- Understanding the rights and protections detailed can empower individuals facing legal challenges.
- Consultation with a legal professional is advised for personal legal matters.
Main things to remember
- This handbook provides essential knowledge about elder law and retirement benefits.
- It's designed to empower seniors and their advocates in navigating legal rights.
- Legal consultations are recommended for personalized assistance.
Looking for another form?
Form popularity
FAQ
The SECURE Act gives extra time for employers to start 401(k) profit-sharing plans in 2021. It extends the deadline for starting a plan and allows an employer to backdate it to the prior year (starting with 2020), thereby increasing their tax-deductible contribution.
The Employee Retirement Income Security Act of 1974, or ERISA, protects the assets of millions of Americans so that funds placed in retirement plans during their working lives will be there when they retire.ERISA does not require any employer to establish a retirement plan.
401(k). Solo 401(k). 403(b). 457(b). IRA. Roth IRA. Self-directed IRA. SIMPLE IRA.
ERISA does not require any employer to establish a retirement plan. It only requires that those who establish plans must meet certain minimum standards. The law generally does not specify how much money a participant must be paid as a benefit.
Thanks to the Age Discrimination in Employment Act (ADEA), there is no mandatory age for retirement.In other words, your employer cannot force you to retire. Otherwise, you have the legal right to file an age discrimination lawsuit. However, there is a caveat in that companies have a standard retirement age.
Employers are not required to offer retirement plans to their employees. Having a retirement plan is purely voluntary on the employer's part. If your employer doesn't offer a retirement plan, all you can do is save for your own retirement or look for a different job where the company offers a retirement plan.
Your company can even refuse to give you your 401(k) before retirement if you need it. The IRS sets penalties for early withdrawals of money in a 401(k) account.A company can refuse to give you your 401(k) if it goes against their summary plan description.
The SECURE Act pushed back the age at which retirement plan participants need to take required minimum distributions (RMDs), from 70½ to 72, and allows traditional IRA owners to keep making contributions indefinitely.The SECURE Act allows 401(k) plans to offer annuities.
Your employer can remove money from your 401(k) after you leave the company, but only under certain circumstances. If your balance is less than $1,000, your employer can cut you a check.For balances of $5,000 or more, your employer must leave your money in a 401(k) unless you provide other instructions.