Virginia Warranty Deed from a Trust to an Individual
What is this form?
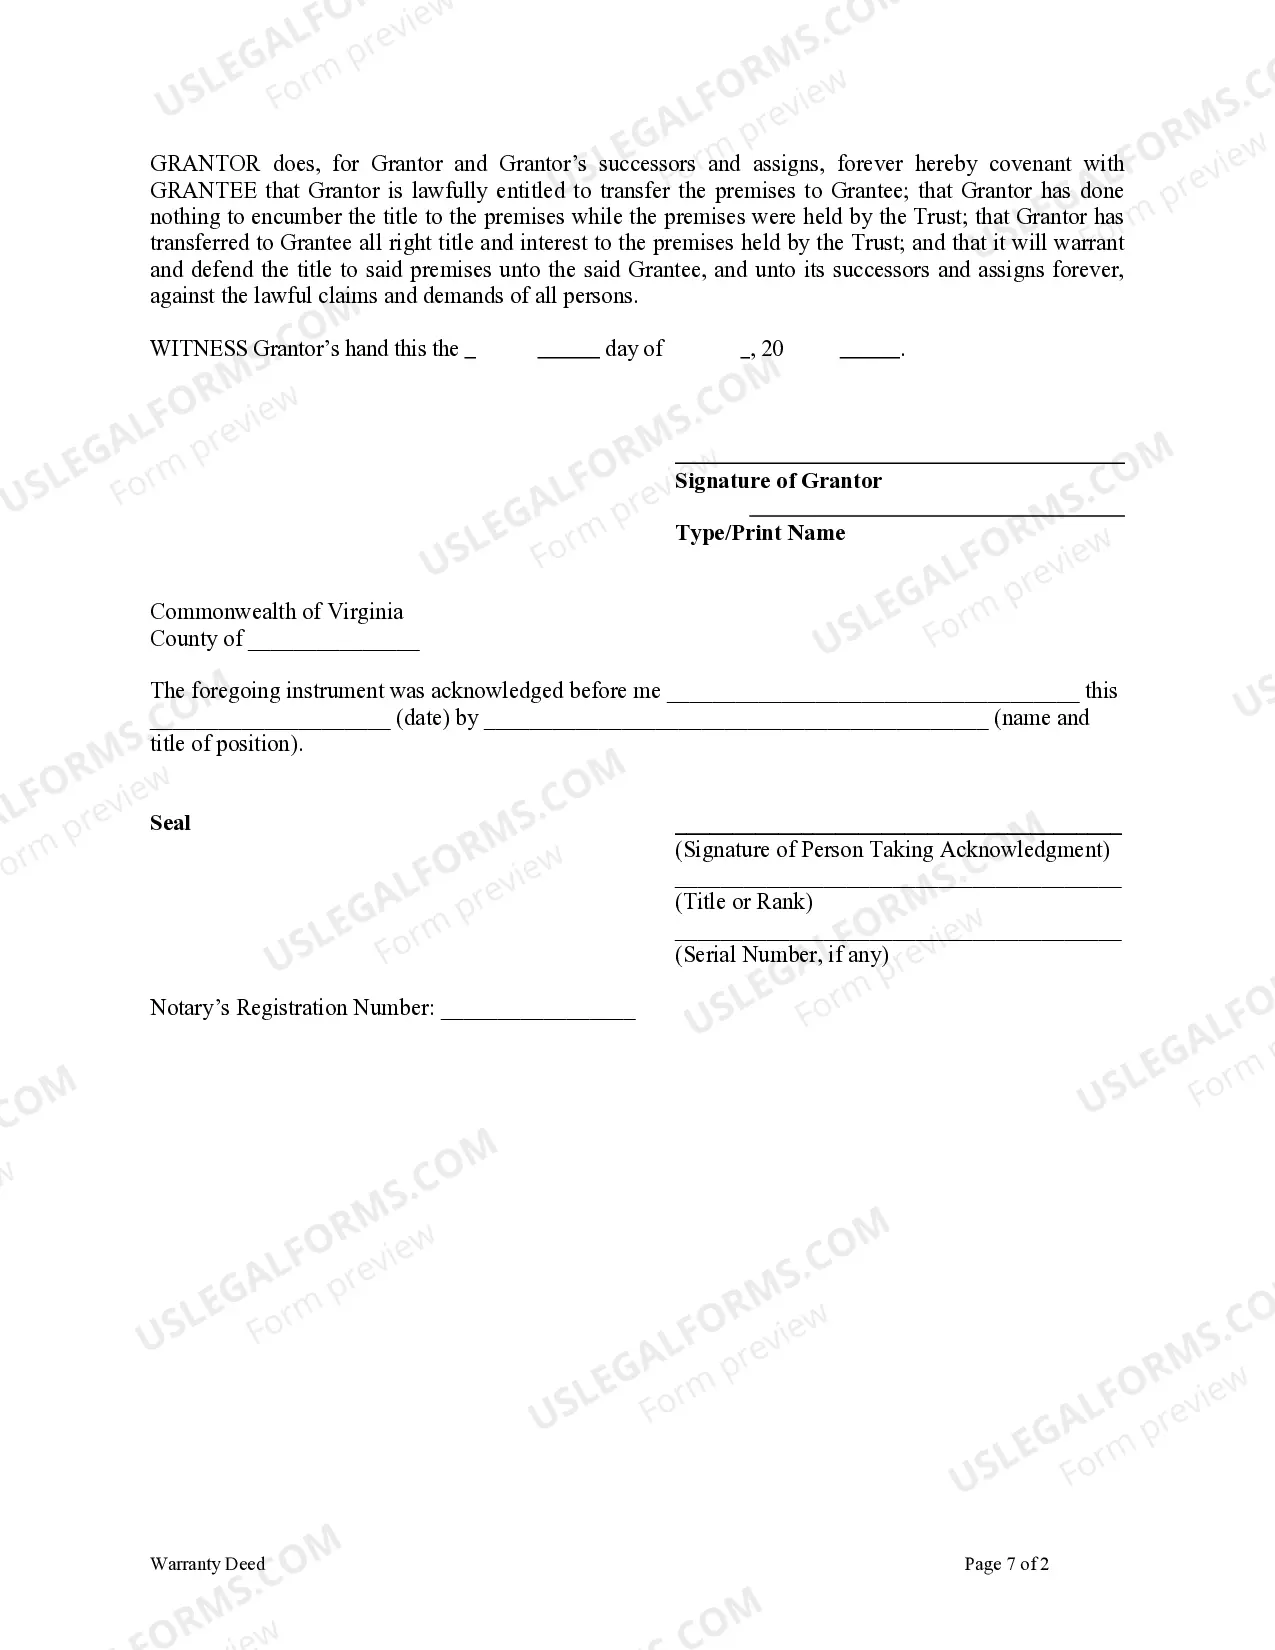
The Warranty Deed from a Trust to an Individual is a legal document that transfers property ownership from a trust to a specific individual. This type of warranty deed ensures that the grantor (the trust) guarantees clear title to the property being conveyed. Unlike other deeds, the warranty deed provides an added layer of protection, affirming that there are no undisclosed claims against the property. This makes it distinct from quitclaim deeds, which do not offer such guarantees.
Key parts of this document
- Identification of the parties involved: the Grantor (trust) and the Grantee (individual).
- Description of the property being transferred, including legal description and boundaries.
- Warranty clause affirming the Grantor's commitment to defend the title against any claims.
- Space for signatures and dates to validate the transaction.
- Notarization section to ensure compliance with legal formalities.



Situations where this form applies
This form is necessary when a property held in a trust is being transferred to an individual. Typical scenarios for its use include estate planning situations, where a trustee wishes to distribute assets to a beneficiary or when a trust is dissolving and property is being allocated to a specific party. Utilizing this form helps to ensure smooth property title transfer and maintain legal clarity.
Who should use this form
Eligibility for using this form includes:
- Trustees acting on behalf of a trust that holds property.
- Individuals who are beneficiaries of a trust and are receiving property.
- Real estate professionals assisting clients with property transfers from trusts.
How to complete this form
- Identify the Grantor as the trust and the Grantee as the individual receiving the property.
- Provide a detailed description of the property, including the legal description and boundaries.
- Include a warranty clause that asserts the Grantorâs guarantee of title.
- Have the Grantor (trustee) sign the document and enter the date of signing.
- Obtain notarization to validate the deed for recording purposes.
Is notarization required?
Yes, this form must be notarized to be legally valid. Notarization ensures that the identities of the signing parties are confirmed and that the document can be officially recorded. US Legal Forms offers integrated online notarization services, allowing you to complete this process quickly and securely.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Common mistakes
- Failing to include a complete and accurate description of the property.
- Not obtaining notarization, which may render the deed invalid for recording.
- Leaving out the warranty clause, which is essential for protecting the Granteeâs rights.
- Not entering the correct names of the Grantor or Grantee.
Advantages of online completion
- Easy access to the form allows for quick completion and downloading.
- Editable forms ensure you can tailor the document to your specific needs.
- Compliance with legal standards provides peace of mind regarding validity.
Quick recap
- The Warranty Deed from a Trust to an Individual is essential for transferring trust-held property.
- Proper completion and notarization are critical for the deed's legality.
- Always ensure to comply with state-specific laws and recording requirements.
Looking for another form?
Form popularity
FAQ
A trust is traditionally used for minimizing estate taxes and can offer other benefits as part of a well-crafted estate plan. A trust is a fiduciary arrangement that allows a third party, or trustee, to hold assets on behalf of a beneficiary or beneficiaries.
This is not possible, as a trust is not a person.This provision would give the trustees the power to appoint trust assets to another trust, usually of which at least one of the beneficiaries of the original trust is a beneficiary of the new trust.
Why do people set up trusts? The most frequent motive is to assure for loved ones financial protection, which is marked by a continuity of professional management and guidance. Trusts, depending on their nature may also provide important tax advantages. The individual arranging a trust is called the grantor.
The principal may generate an income in the form of interest paid on the principal. Simple trusts may not hold onto the income earned by the principal, so they must distribute that income to beneficiaries (you can't distribute the principal also called the trust corpus or pay money out of the trust to a charity).
A personal trust is a trust that an individual creates, formally naming themselves as the beneficiary. Personal trusts are separate legal entities that have the authority to buy, sell, hold, and manage property for the benefit of their trustors.
A single living trust involves just one individual, while a joint living trust usually involves a married couple. Joint living trusts are commonly used to transfer assets between spouses upon one spouse's death. However, like a single living trust, other beneficiaries can be designated as well.
What is a trust?It is important to note that the trust itself does not have any legal personality; rather, it is the trustee who is the principal actor and carries out the purposes of the trust in his own name.
A trust fund is a legal entity that holds property or assets on behalf of another person, group or organization. It is an estate planning tool that keeps your assets in a trust managed by a neutral third party, or trustee. A trust fund can include money, property, stock, a business or a combination of these.
When you create a trust, you set up a plan to take care of the people you love when you're no longer around or lack the capacity to assist them. Not only can a trust simplify the process of asset distribution, but it can also help you leave a lasting financial legacy.
Saves time and money in the probate process A living trust names a trustee who can immediately take care of your end-of-life affairslike paying for funeral costs and distributing property to heirswithout having to wait on the probate judge. Less waiting time means less probate costs and more savings.