Revolving Credit Loan and Security Agreement between Dixon Ticonderoga Co. and Dixon Ticonderoga, Inc.
Understanding this form
This form is a Revolving Credit Loan and Security Agreement between Dixon Ticonderoga Co. and Dixon Ticonderoga, Inc. It serves as an amendment to previously established loan documents, detailing financial arrangements and obligations related to a line of credit. This agreement allows borrowers to access up to $35 million in revolving credit, with provisions for both existing and new lenders. It is crucial for businesses needing flexible funding solutions.
Key parts of this document
- Defined terms that outline the agreement's context and key financial metrics.
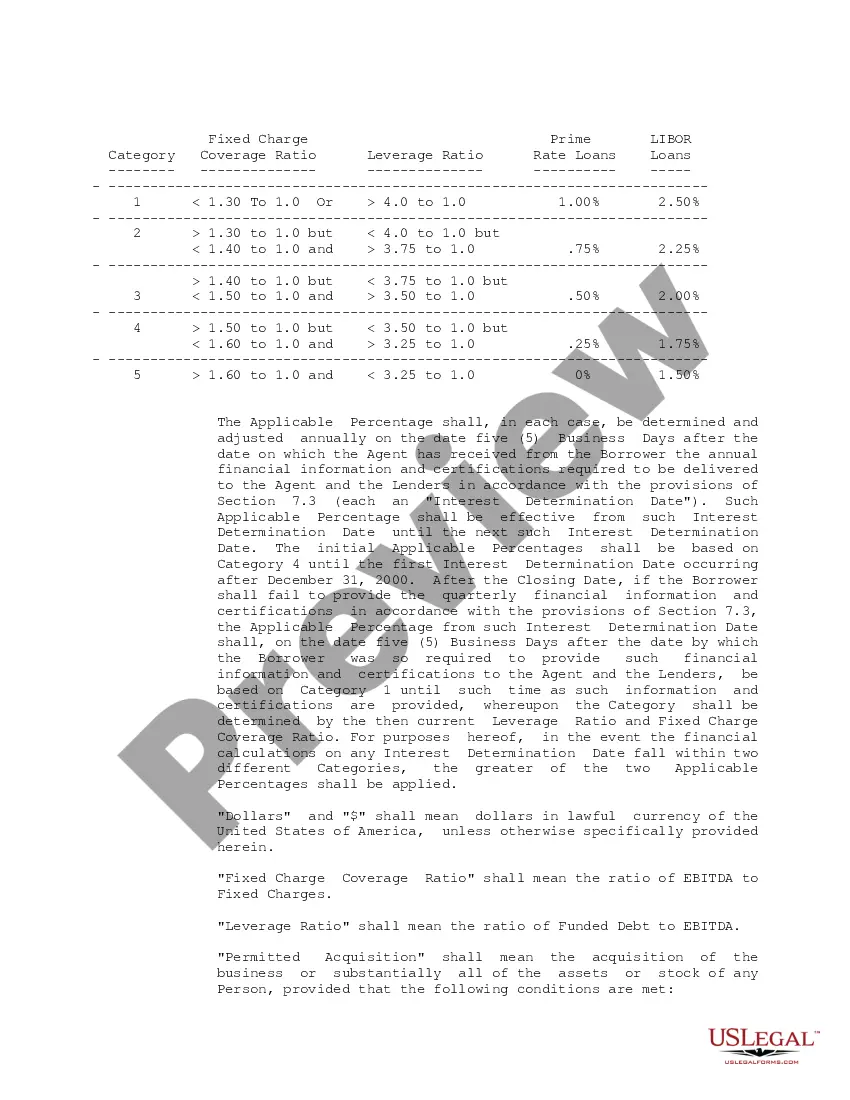
- Amendments to existing definitions and terms related to interest rates and loan conditions.
- Provisions detailing revisions to existing financial covenants and obligations.
- Conditions precedent for the effectiveness of the modification, such as executing necessary documents.
- Rights and obligations concerning borrower and lender relationships and responsibilities.
When this form is needed
This form is necessary when a business is seeking to modify an existing revolving credit agreement, especially when changes impact the amount of credit available, interest rates, or financial covenants. It is useful in scenarios where financial institutions or borrowers wish to reassess and adjust their lending terms without starting from scratch.
Intended users of this form
This form should be used by:
- Businesses needing to amend their revolving credit agreements for financial flexibility.
- Financial institutions involved as lenders in the agreement.
- Corporate executives or legal representatives managing loan agreements for their organizations.
How to complete this form
To correctly complete this form, follow these steps:
- Identify and list all parties involved, including existing and new lenders.
- Clearly state the modifications made to the original agreement, including any changes to the credit limit.
- Confirm and update all definitions affected by the modifications.
- Specify any conditions precedent or required documentation that must be fulfilled.
- Ensure all parties sign the agreement, along with appropriate acknowledgments by legal representatives.
Does this document require notarization?
This form does not typically require notarization unless specified by local law.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Mistakes to watch out for
- Failing to include all relevant parties in the agreement.
- Neglecting to update the credit limit or provisions related to interest rates.
- Not providing the necessary supporting documents required for the modifications.
- Omitting signatures or approvals from involved representatives.
Benefits of completing this form online
- Convenience of online access facilitates quicker agreement completion.
- Editable forms allow precision in tailoring to specific financial agreements.
- Reliability of attorney-drafted templates ensures compliance with legal standards.
- This agreement serves as a legally binding contract once executed by all parties.
- It outlines the terms under which businesses can access credit, ensuring lenders are protected.
- The agreement's enforceability is dependent on sufficient compliance with loan requirements.
Quick recap
- The Revolving Credit Loan and Security Agreement provides necessary flexibility for borrowers.
- Key amendments ensure clarity in terms and obligations among lenders.
- Proper execution of this form is essential for maintaining valid credit terms.
Looking for another form?
Form popularity
FAQ
State the purpose for the loan. #Set forth the amount and terms of the loan. Your agreement should clearly state the amount of money you're lending your friend, the interest rate, and the total amount your friend will pay you back.
A loan agreement is a contract between you, the borrower and the lender.There are situations where you may no longer want the loan, or the item it financed. If there are valid reasons such as fraud or a breech of contract, you should be able to get out of the loan.
Identity of the Parties. The names of the lender and borrower need to be stated. Date of the Agreement. Interest Rate. Repayment Terms. Default provisions. Signatures. Choice of Law. Severability.
Starting the Document. Write the date at the top of the page. Write the Terms of the Loan. State the purpose of the personal payment agreement and the terms for returning the money. Date the Document. Statement of Agreement. Sign the Document. Record the Document.
Starting the Document. Write the date at the top of the page. Write the Terms of the Loan. State the purpose of the personal payment agreement and the terms for returning the money. Date the Document. Statement of Agreement. Sign the Document. Record the Document.
Ask for a plan. Review the borrower's finances and help them set up a budget that includes your monthly repayment. Make sure they understand this is a loan, not a gift. Set terms that both sides agree can be enforced 2026 and enforce them! Keep your distance. Get it down on paper.
Come up with a schedule for repayment. Use a family contract template that includes a repayment schedule. Set and interest rate. Put your agreement in writing. Keep payment records.
For a personal loan agreement to be enforceable, it must be documented in writing and signed by both parties. You may choose to keep a copy in your county recorder's office if you wish, though it's not legally necessary. It's sufficient for both parties to keep their own copy, ideally in a safe place.
Step 1 Loan Amount, Borrower and Lender. Step 2 Payment. Step 3 Interest. Step 4 Expenses. Step 5 Governing Law. Step 6 Signing.
A loan agreement is a contract between a borrower and a lender which regulates the mutual promises made by each party.Loan agreements are usually in written form, but there is no legal reason why a loan agreement cannot be a purely oral contract (although oral agreements are more difficult to enforce).