Cross-Purchase Buy-Sell Agreement with Life Insurance to Fund Purchase of Deceased Partner's Interest -- Partners to Increase Life Insurance if Value of Partnership Interest Increases
About this form
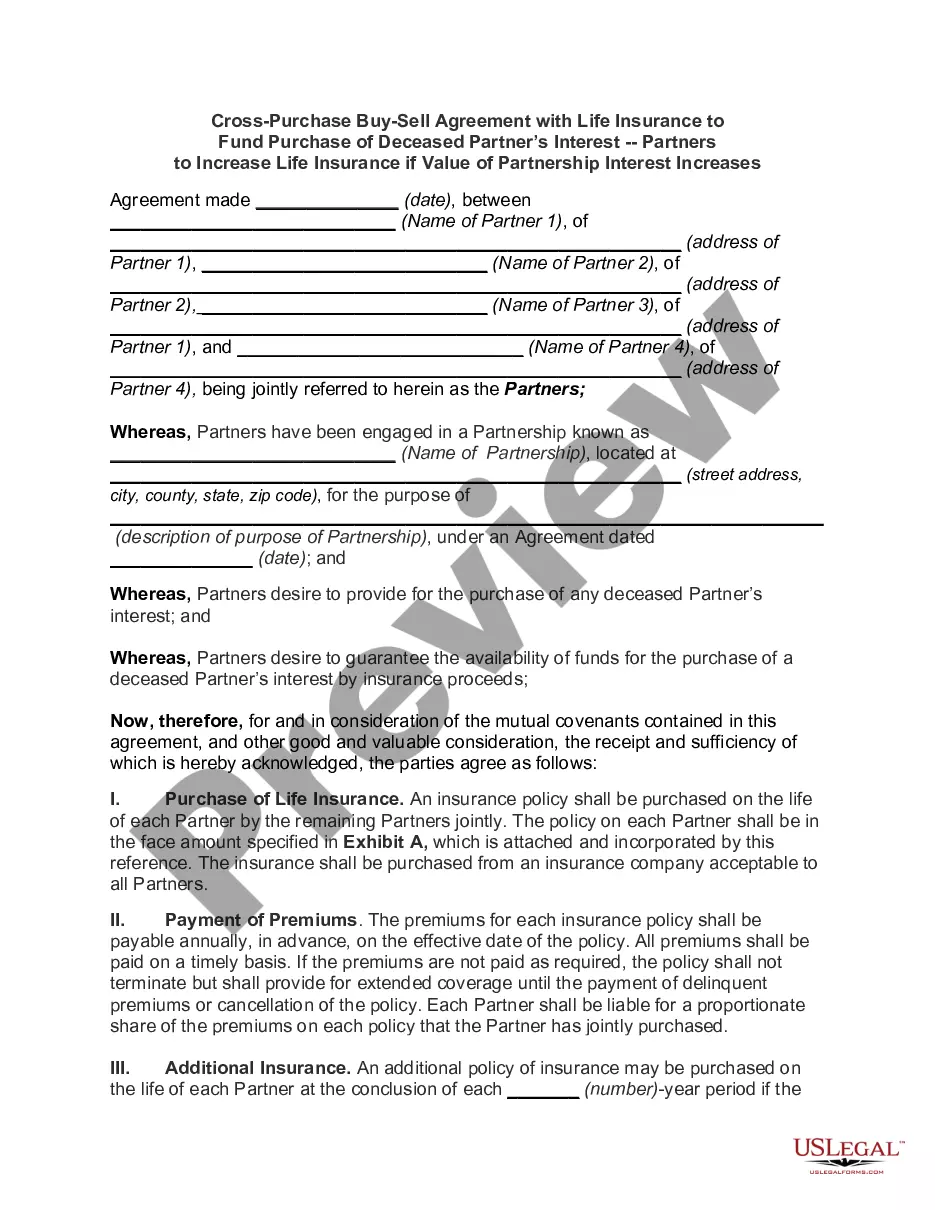
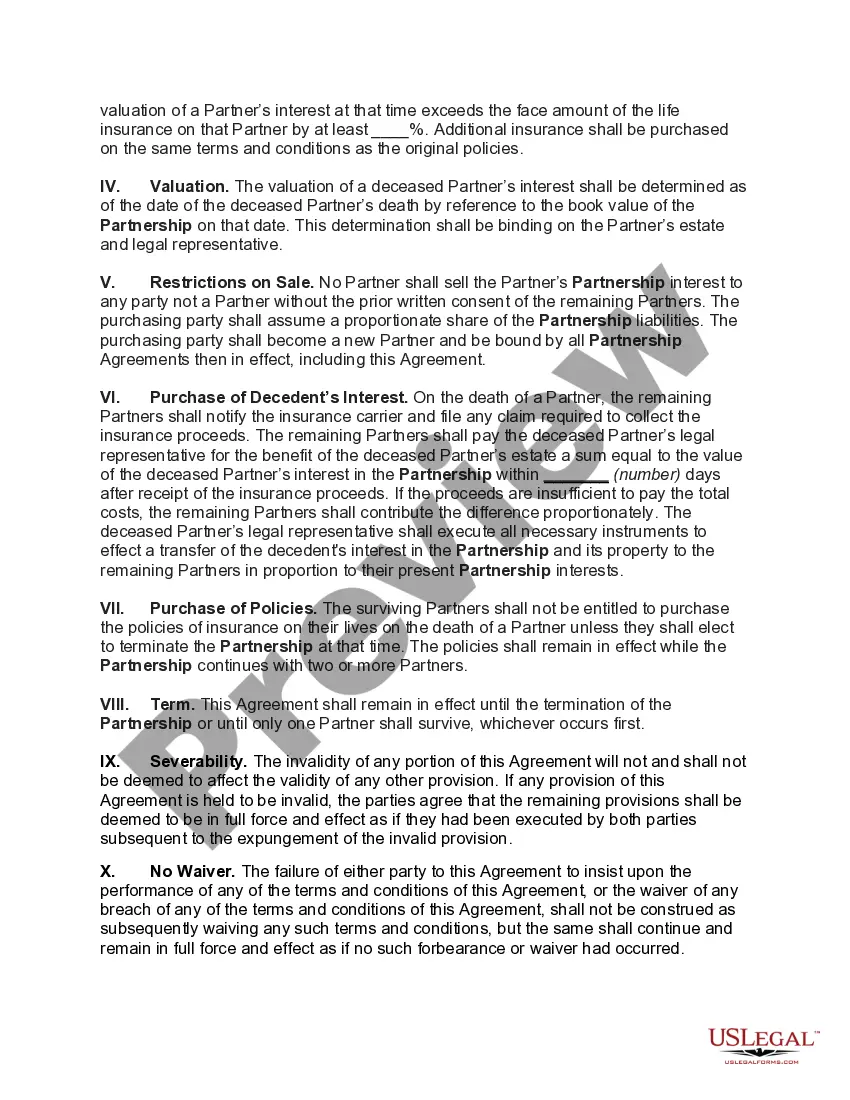
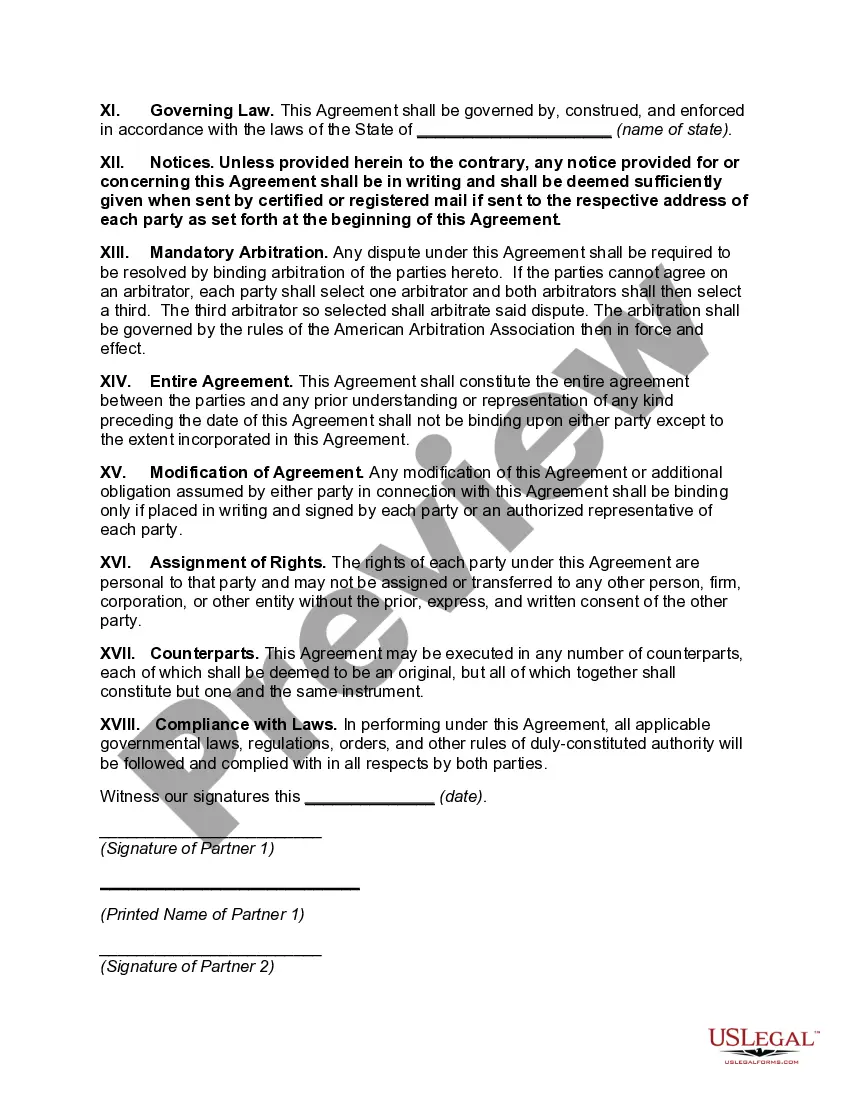
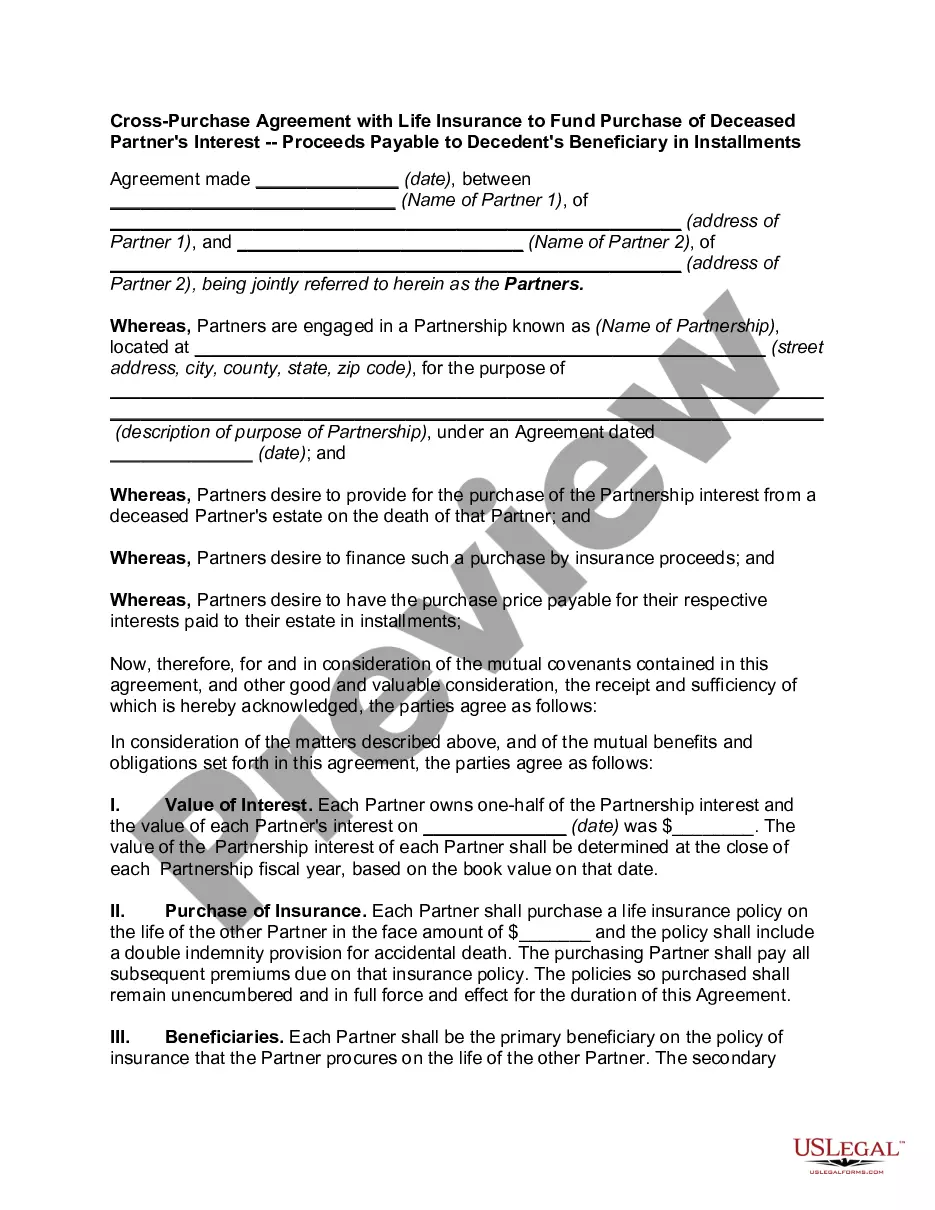
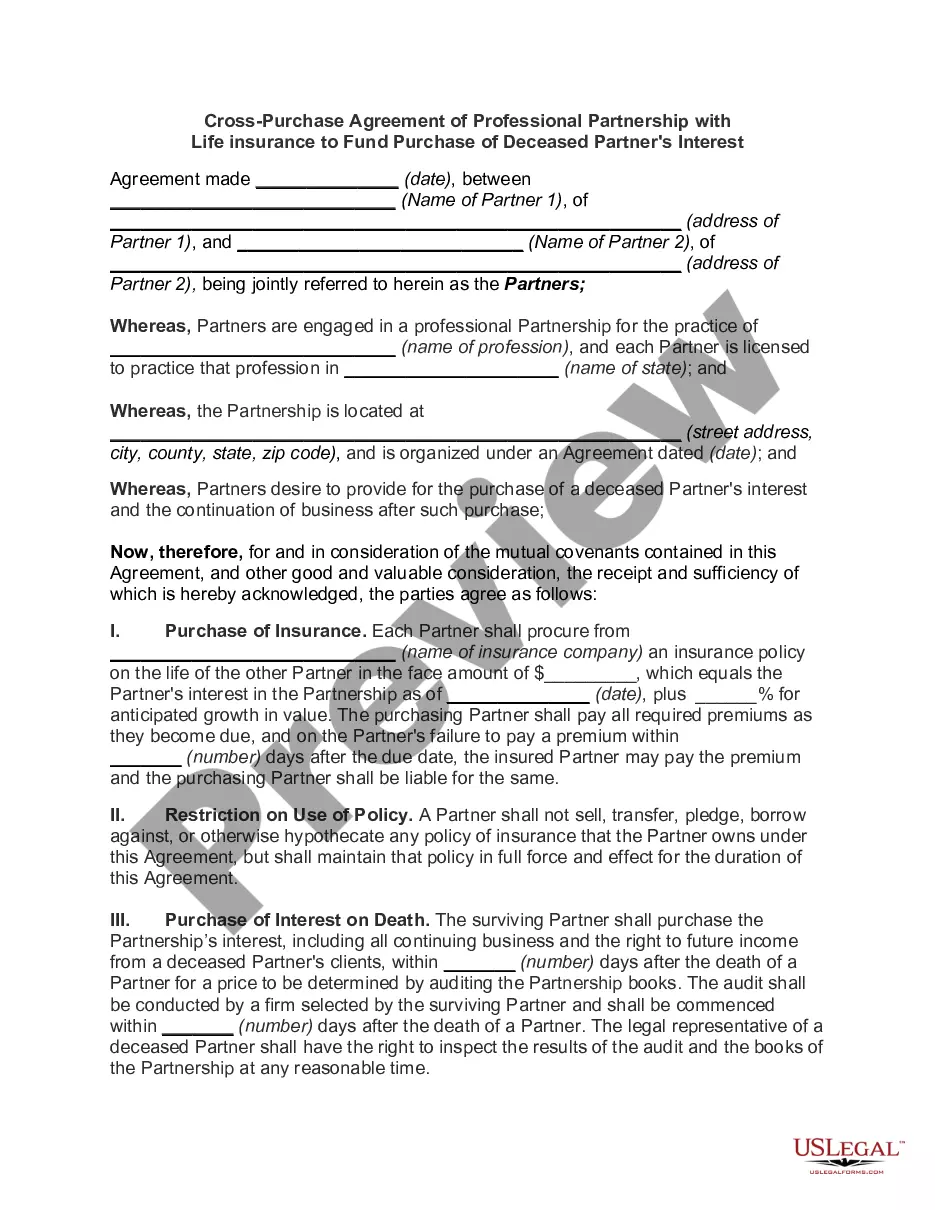
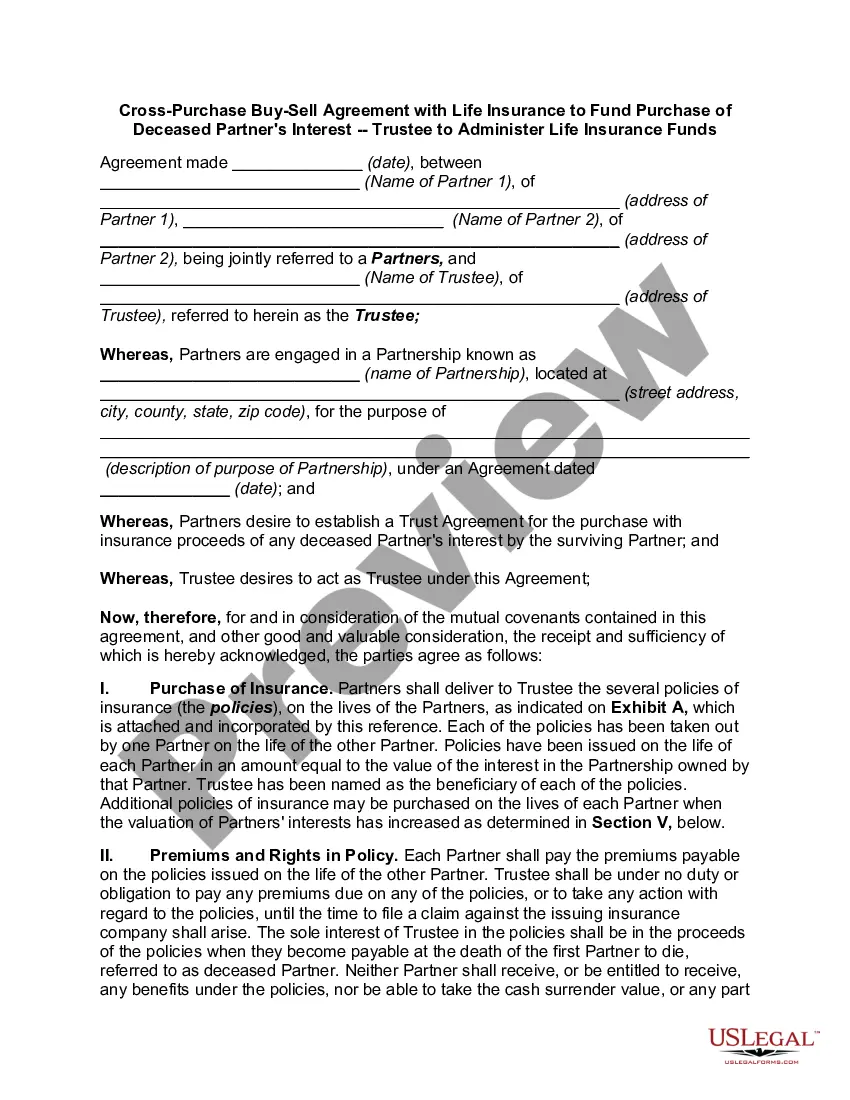
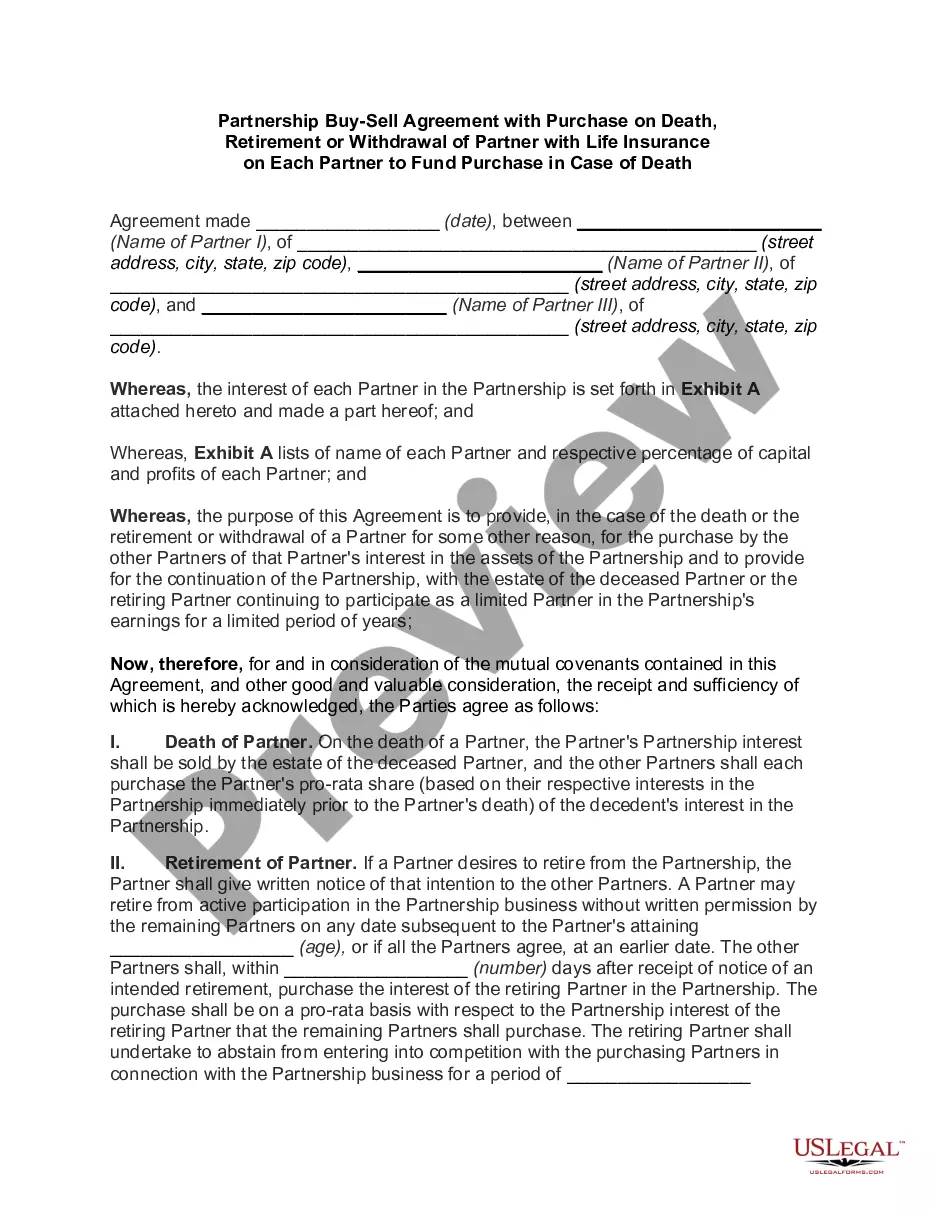
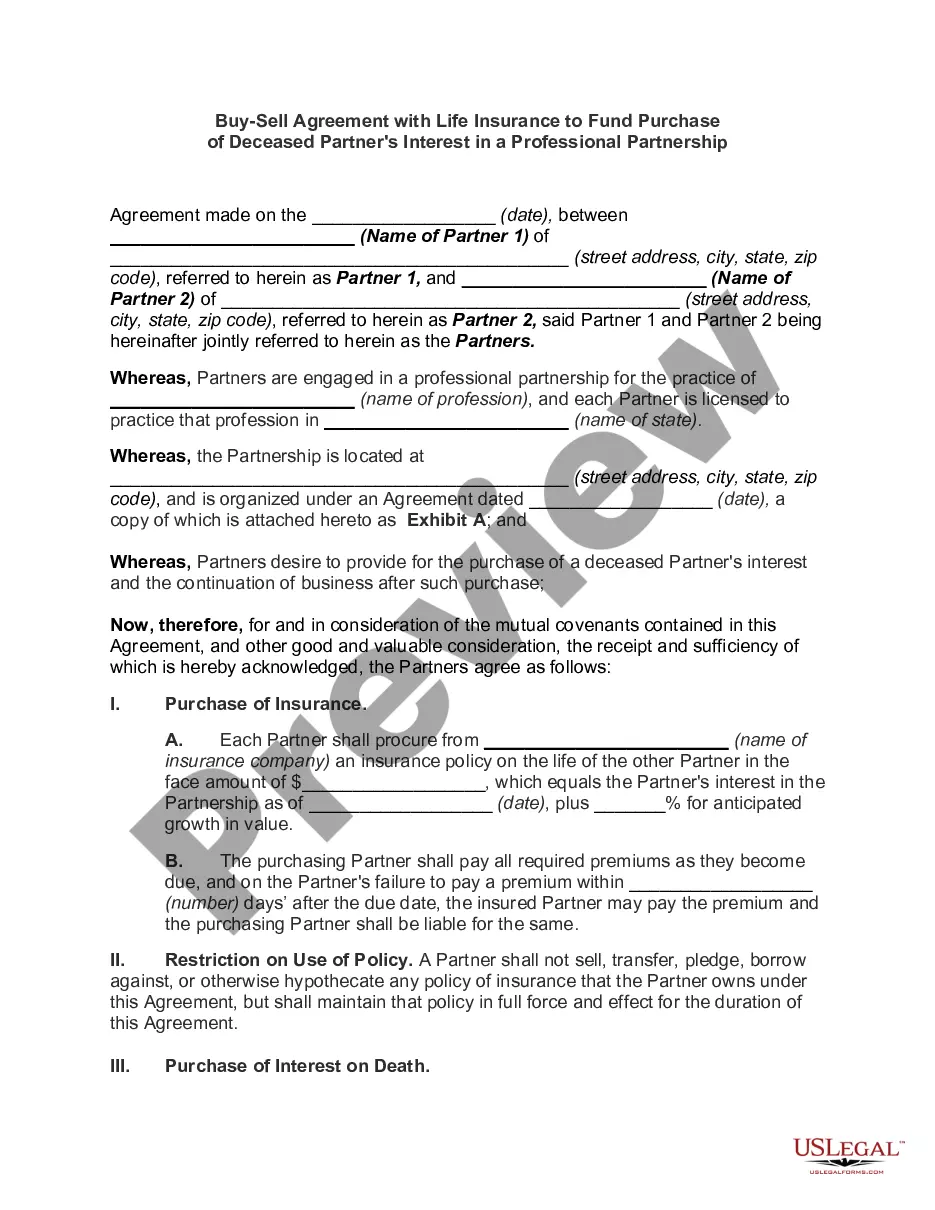
The Cross-Purchase Buy-Sell Agreement with Life Insurance serves as a legal document that outlines how ownership interests in a partnership will be transferred in the event of a partner's death, retirement, or disability. This agreement ensures that the remaining partners can purchase the deceased partner's share, funded by a life insurance policy, safeguarding the business's ongoing operation and financial stability. Unlike other agreements, this form specifically includes provisions for periodically adjusting life insurance coverage based on the partnership's valuation, ensuring that funds are readily available to complete the buyout.
Form components explained
- Purchase of life insurance policies on each partner's life, held jointly by the remaining partners.
- Details on premium payment responsibilities and coverage amounts.
- Procedure for additional insurance purchases based on increased partnership valuations.
- Valuation methods for the deceased partner's interest to determine buyout price upon death.
- Restrictions on selling partnership interests without consent from remaining partners.
- Procedures for notifying the insurance carrier and processing claims after a partner's death.
When this form is needed
This agreement should be utilized when forming partnerships to ensure clear terms for ownership transfer if a partner dies, retires, or becomes disabled. It is particularly beneficial for small businesses where the loss of a partner could jeopardize operations and financial stability. Implementing this agreement during the initial partnership setup or when significant changes occur in the business's valuation can help all parties involved prepare for unforeseen circumstances.
Who needs this form
- Small business partners looking to secure ownership interests.
- Partners who wish to establish a clear framework for the transfer of interests due to life events.
- Business owners who have significant fluctuating partnership valuations.
- Partners interested in ensuring financial resources are available to cover buyouts upon a partner's death.
Completing this form step by step
- Identify and list the names and addresses of all partners in the agreement.
- Specify the name and purpose of the partnership.
- Determine the amount of life insurance to be purchased for each partner and include it in Exhibit A.
- Fill in the terms for premium payments and additional insurance coverage based on partnership valuation.
- Include provisions for valuation at the time of a partner's death and how payments will be made to the deceased partner's estate.
- Ensure all partners sign and date the agreement to validate it.
Notarization guidance
Notarization is not commonly needed for this form. However, certain documents or local rules may make it necessary. Our notarization service, powered by Notarize, allows you to finalize it securely online anytime, day or night.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Common mistakes to avoid
- Failing to periodically review and adjust life insurance amounts based on partnership valuations.
- Not clearly defining how valuations will be determined in the event of a partner's death.
- Neglecting to include procedures for finding replacement partners or transferring interests without proper consent.
- Overlooking the need for all partners to sign and date the agreement.
Why use this form online
- Convenience of downloading and completing the form at your own pace.
- Editability allows for customized information that accurately reflects the partnership's needs.
- Reliability brought by templates drafted by licensed attorneys, ensuring legal accuracy.
Looking for another form?


Form popularity
FAQ
In a cross purchase buy-sell agreement, each business owner buys a life insurance policy on the other owner(s). With multiple owners, this can get very complex and complicated. Instead, try a trusteed cross purchase buy-sell, in which a third-party (acting as trustee) takes care of the buy-sell arrangement.
purchase agreement allows a company's partners or other stakeholders to coordinate continuance of a business. The agreement involves the purchase of life and/or disability insurance policy in case a stakeholder dies or becomes incapacitated.
Cross purchase buy sell agreements have a variety of purposes. One of the main benefits of this document is that it allows the remaining partners in a business to purchase the shares of a partner who is leaving the company. In addition, this document will decide how these shares can be purchased or distributed.
Example: Alma owns 60%, Betty 20% and Catherine 20% of their company. The cross-purchase agreement states that if one owner dies, her interest is divided equally between the survivors. Therefore, if Betty dies, Alma's ownership interest grows from 60% to 70%, while Catherine's interest grows from 20% to 30%.
sell agreement provides a plan for the orderly transfer of any owner's business interest. Consider a buysell agreement for your business if: You have two or more owners. You want to provide protection in the event of any owner's termination of employment, retirement, divorce, disability, or death.
The surviving owners have a better tax consequence from the cross purchase plan than the entity purchase plan in their own future exit. When the owner(s) purchase the business interest of their departed or deceased owner, their basis increases by what they pay to the exiting owner or estate of the deceased owner.
The correct answer is Option D. In a cross-purchase buy-sell agreement that is insured, the surviving owners or partners can purchase the share of the deceased partner or owner.
The disadvantages of cross-purchase buy-sell agreements include: Life insurance policies are not owned by the business so any cash values cannot be considered company assets. Depending on the varying ages of the business owner's actual premium payments may vary greatly.