Termination of Grantor Retained Annuity Trust in Favor of Existing Life Insurance Trust
About this form
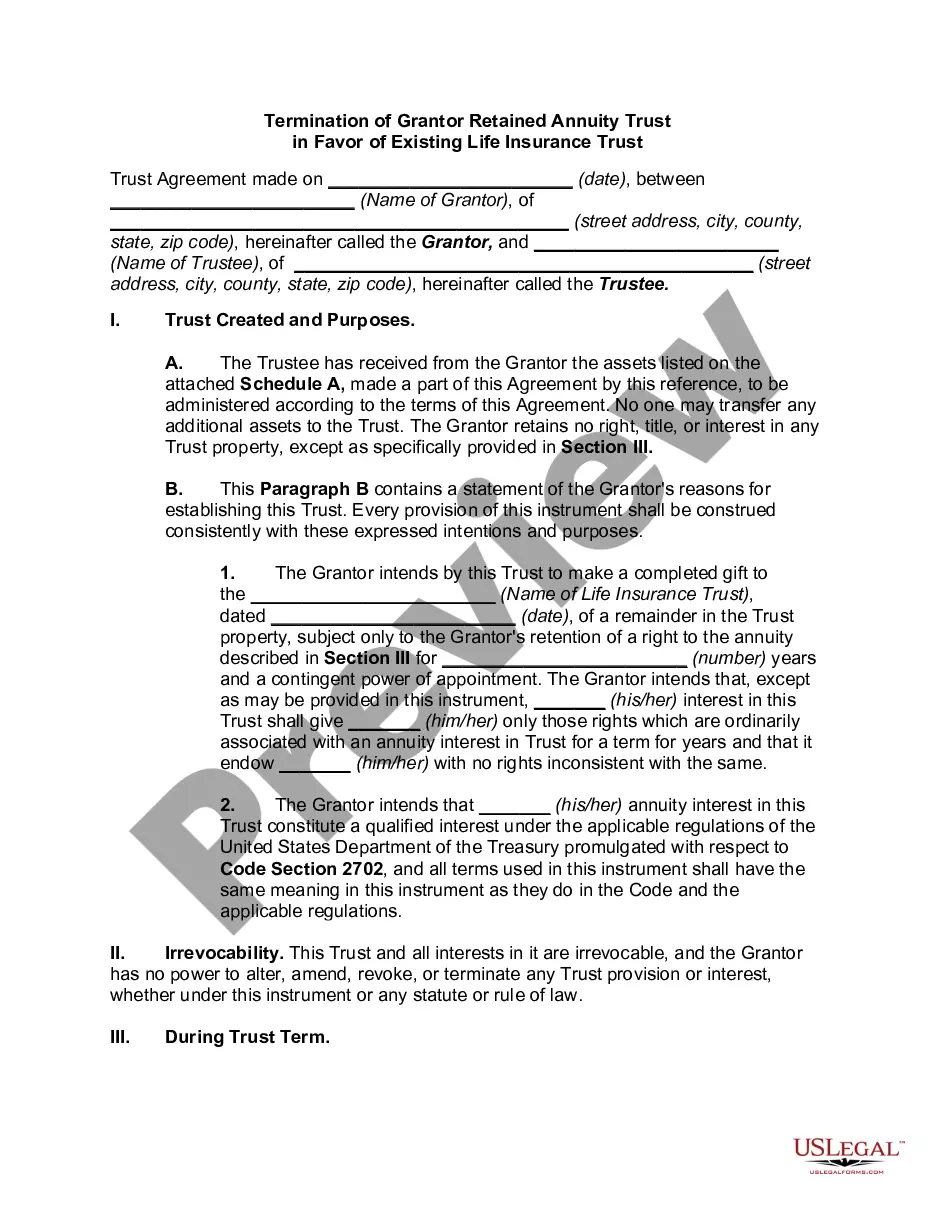
The termination of grantor retained annuity trust (GRAT) in favor of an existing life insurance trust is a legal document used to formally end a GRAT, allowing the remaining assets to be transferred to a designated life insurance trust. This form is crucial for individuals looking to manage their estate planning and ensure that their assets are allocated according to their wishes after their death. Unlike simple trust termination forms, this one specifies the transfer to a life insurance trust, which can offer tax advantages and greater control over how assets are distributed to beneficiaries.
Form components explained
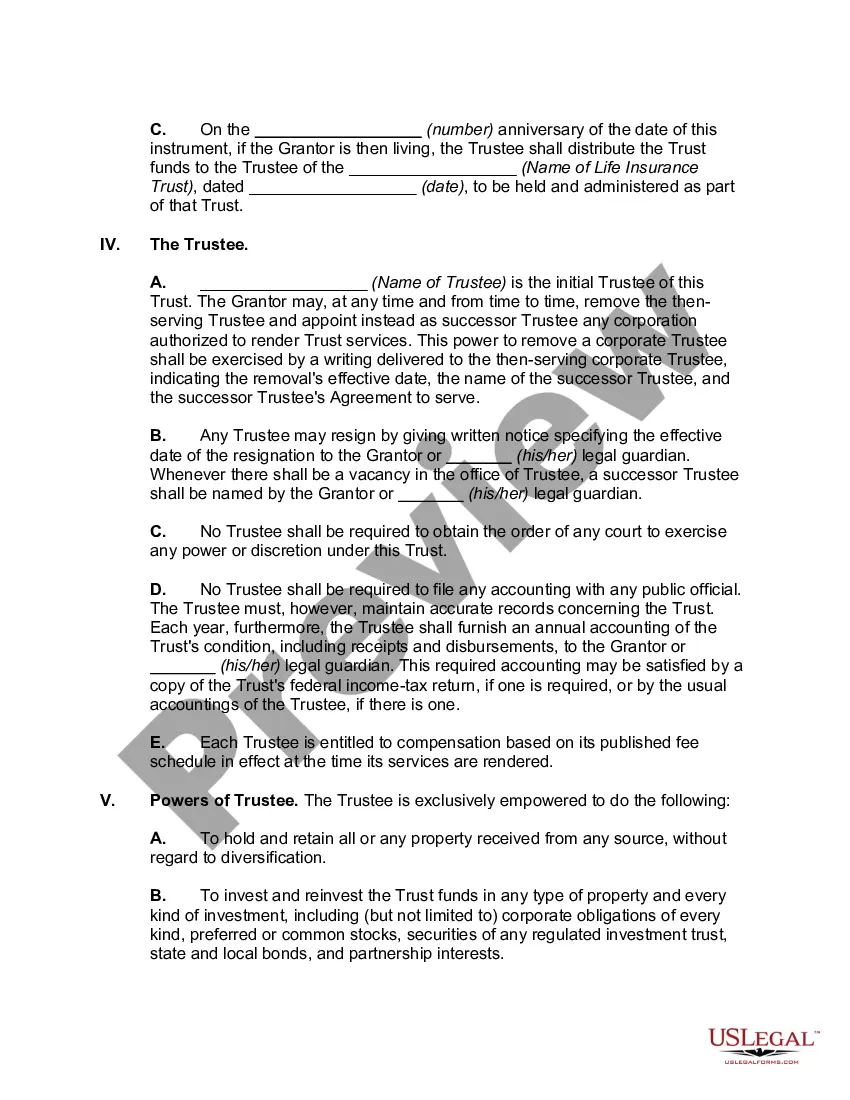
- Identification of the grantor and trustee, including their names and addresses.
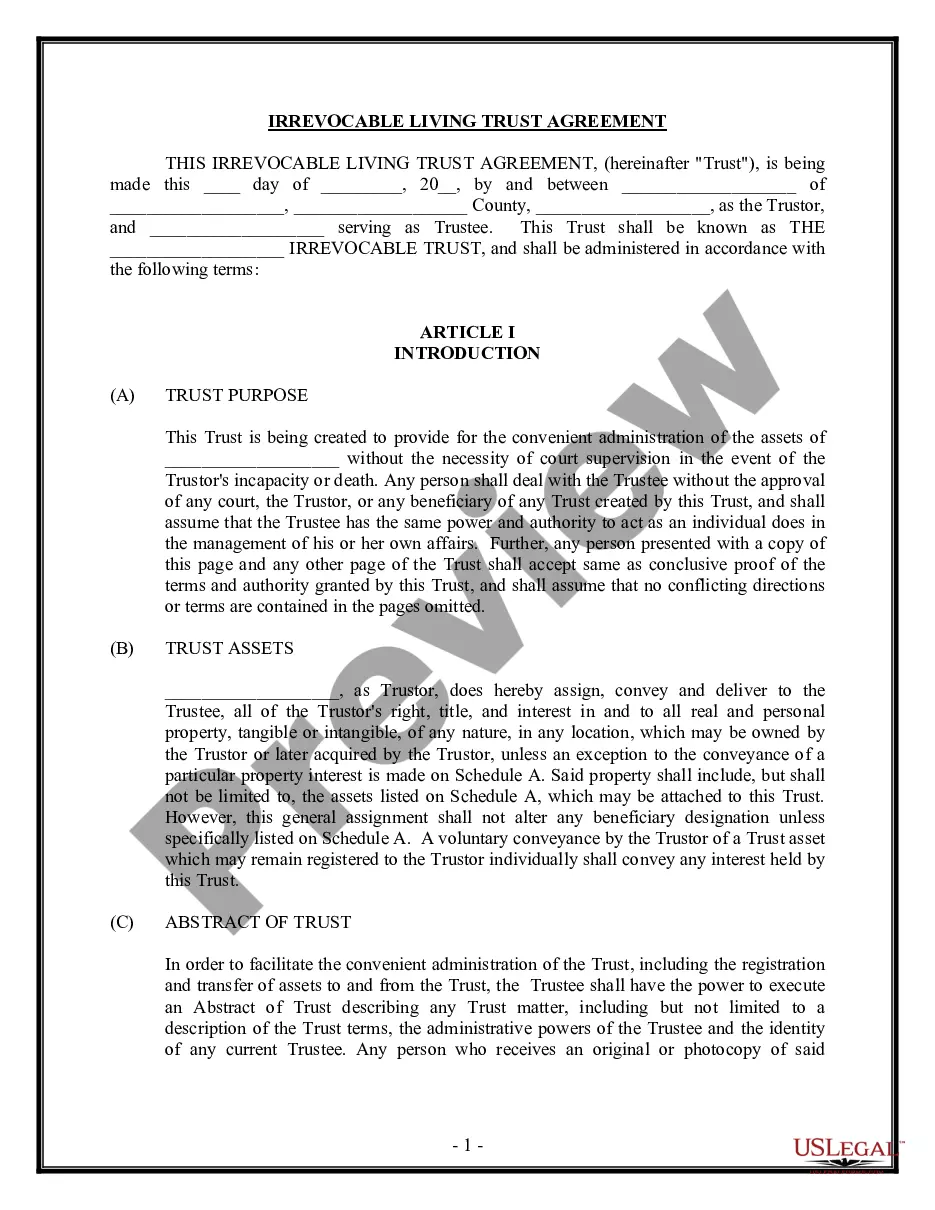
- Explanation of the trust purpose and the irrevocable nature of the trust.
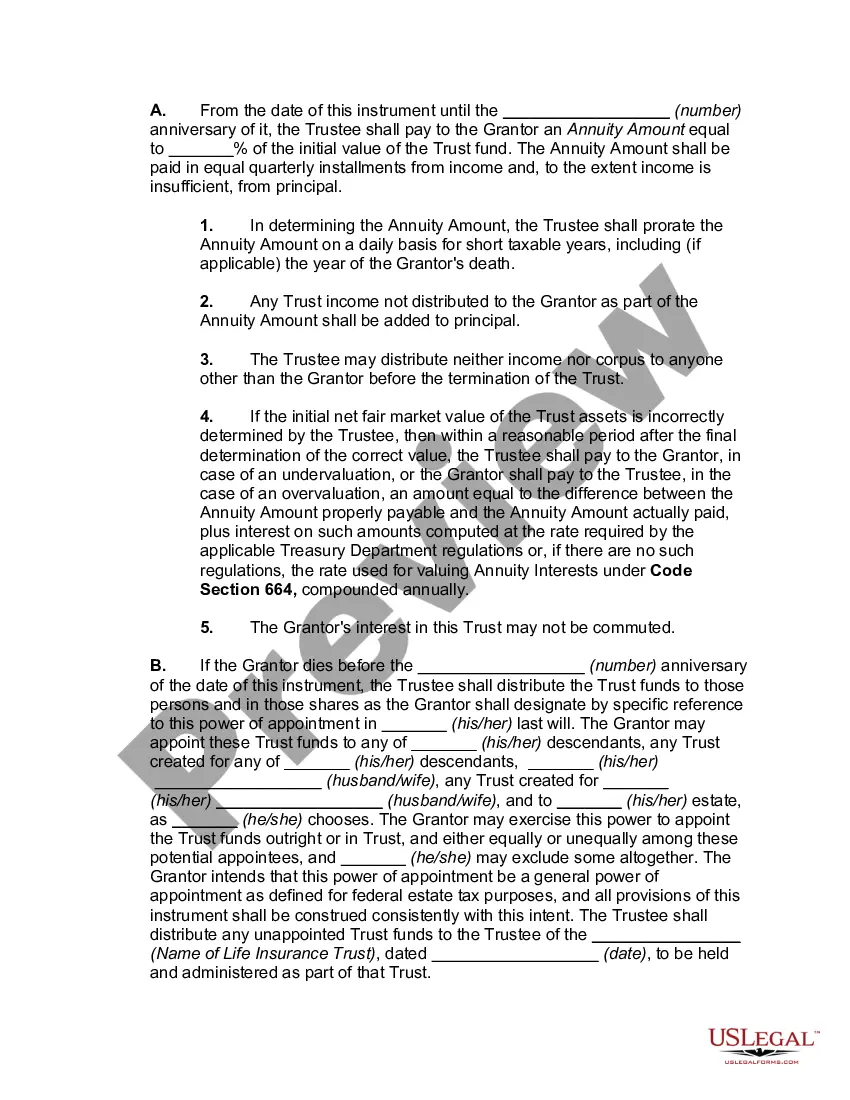
- Details regarding the annuity payments and their duration.
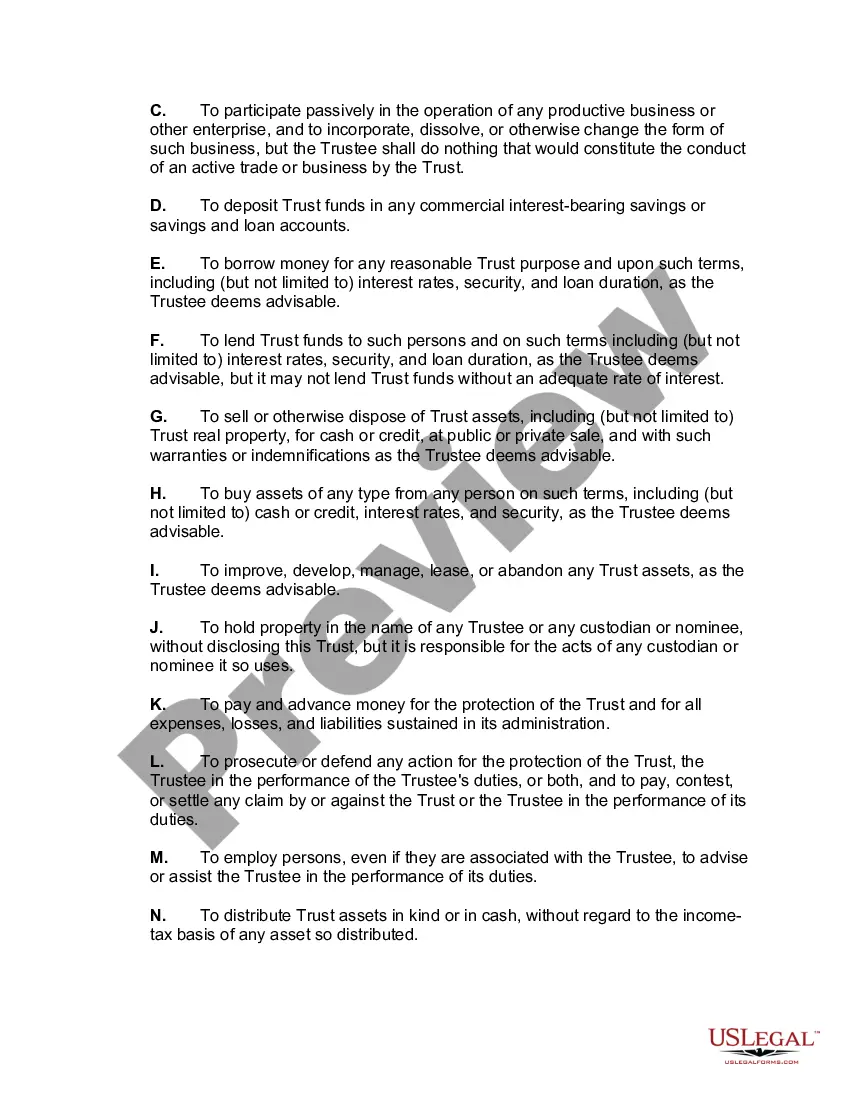
- Distribution clauses outlining what happens upon the death of the grantor.
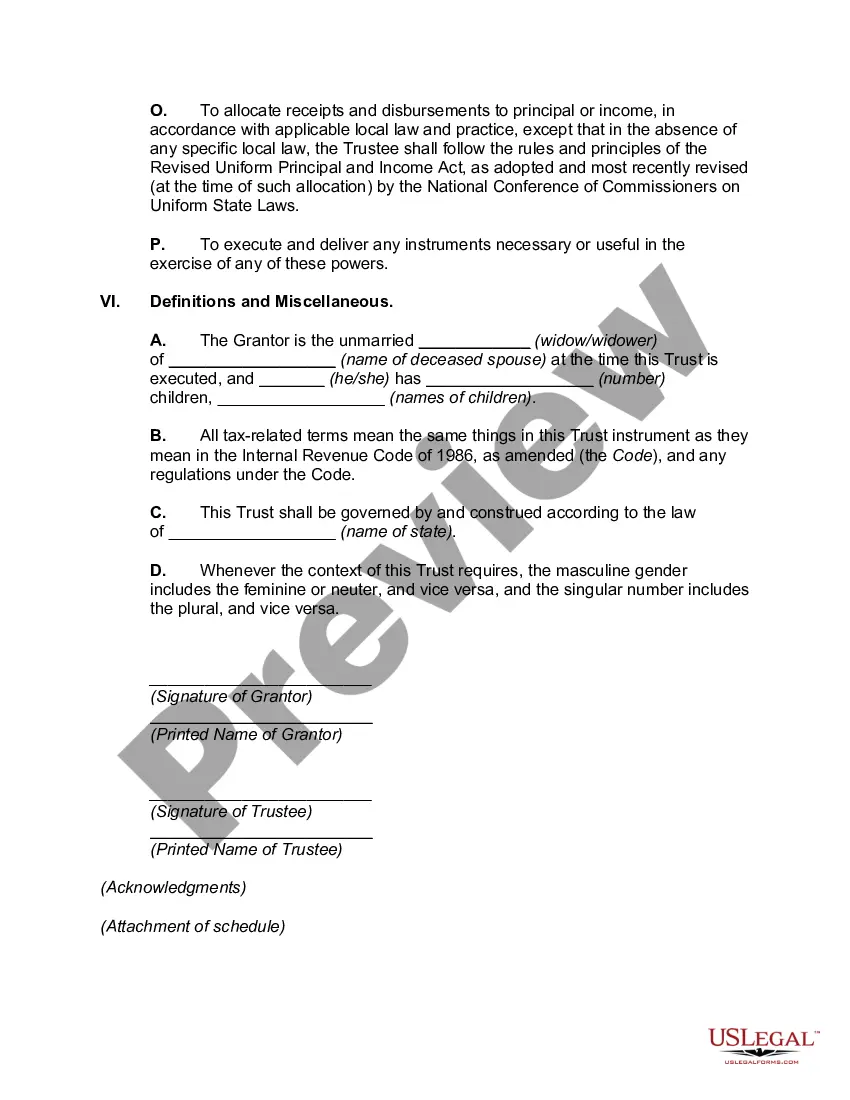
- Powers granted to the trustee regarding asset management.
- Definitions and miscellaneous provisions related to the trust.
When to use this form
This form is typically used in estate planning situations where a grantor wants to terminate a GRAT and transfer the residual assets to an existing life insurance trust. It is appropriate when the grantor needs to adjust their estate plan, particularly after changes in financial circumstances, family dynamics, or tax laws. Utilizing this form ensures that the asset transfer is executed legally and in accordance with the grantor's wishes.
Who can use this document
- Individuals who have established a grantor retained annuity trust (GRAT) and wish to terminate it.
- Grantors looking to transfer remaining assets to a life insurance trust.
- Estate planners and attorneys assisting clients in managing their estate plans.
- Beneficiaries of a grantor looking to ensure a smooth transition of trust assets.
How to prepare this document
- Identify the parties involved by filling in the names and addresses of the grantor and trustee.
- Clearly state the date of the trust agreement and the date of termination.
- Complete the sections detailing the purpose of the trust and the remaining assets to be transferred.
- Include the terms regarding annuity payments and their duration.
- Obtain necessary signatures from both the grantor and trustee, ensuring all required fields are filled out accurately.
Is notarization required?
This form does not typically require notarization unless specified by local law. However, it is often recommended to have such documents notarized for added verification of the identities of the parties involved.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Avoid these common issues
- Failing to specify the correct names and addresses of the grantor and trustee.
- Not including the date of the trust agreement and date of termination.
- Overlooking necessary signatures from all parties involved, which can invalidate the form.
Benefits of using this form online
- Convenient access to a professionally drafted legal template that is easy to complete and download.
- Editability allows users to customize the form to suit their individual needs.
- Reliable guidance helps ensure compliance with legal standards for estate planning.
Looking for another form?
Form popularity
FAQ
Understanding Grantor Retained Annuity Trusts (GRAT) A grantor retained annuity trust is a type of irrevocable gifting trust that allows a grantor or trustmaker to potentially pass a significant amount of wealth to the next generation with little or no gift tax cost.
What is a GRAT and why is it advantageous now? A grantor retained annuity trust, better known as a GRAT, is an irrevocable trust that pays an annuity amount to the grantor for a set period of years, after which the remainder passes to or for the benefit of children or others.
Trust Basics The trustee may be the grantor. The grantor designates the beneficiaries who are to benefit from the trust and receive its income and principal. Certain trusts allow the grantor to be both the trustee and the beneficiary.
The annuity amount is paid to the grantor during the term of the GRAT, and any property remaining in the trust at the end of the GRAT term passes to the beneficiaries with no further gift tax consequences.If the grantor lives out the term, the remainder passes to the beneficiaries without any additional transfer tax.
Interest in a closely or family-held business, including S corporation stock, may be placed in a GRAT. The Settlor may be the Trustee of the GRAT during the annuity term unless cer- tain voting stock is used to fund the GRAT.
There should be no gift tax consequences upon the termination of the GRAT.If the grantor dies during the term of the GRAT and has the right to receive further annuity payments, a portion of the GRAT will be included in the grantor's gross estate for federal estate tax purposes.
A grantor retained income trust (GRIT) is a specific type of trust that allows you to transfer assets while still benefiting from the income they generate. This is a little more advanced than a typical revocable living trust, but establishing a GRIT could yield some advantages.
At the end of the initial term retained by the Grantor, if the Grantor is still living, the remainder beneficiaries (or a trust to be administered for the benefit of the remainder beneficiaries) receive $100,0000 plus all capital growth (which is the amount over and above the net income that was paid to the Grantor).