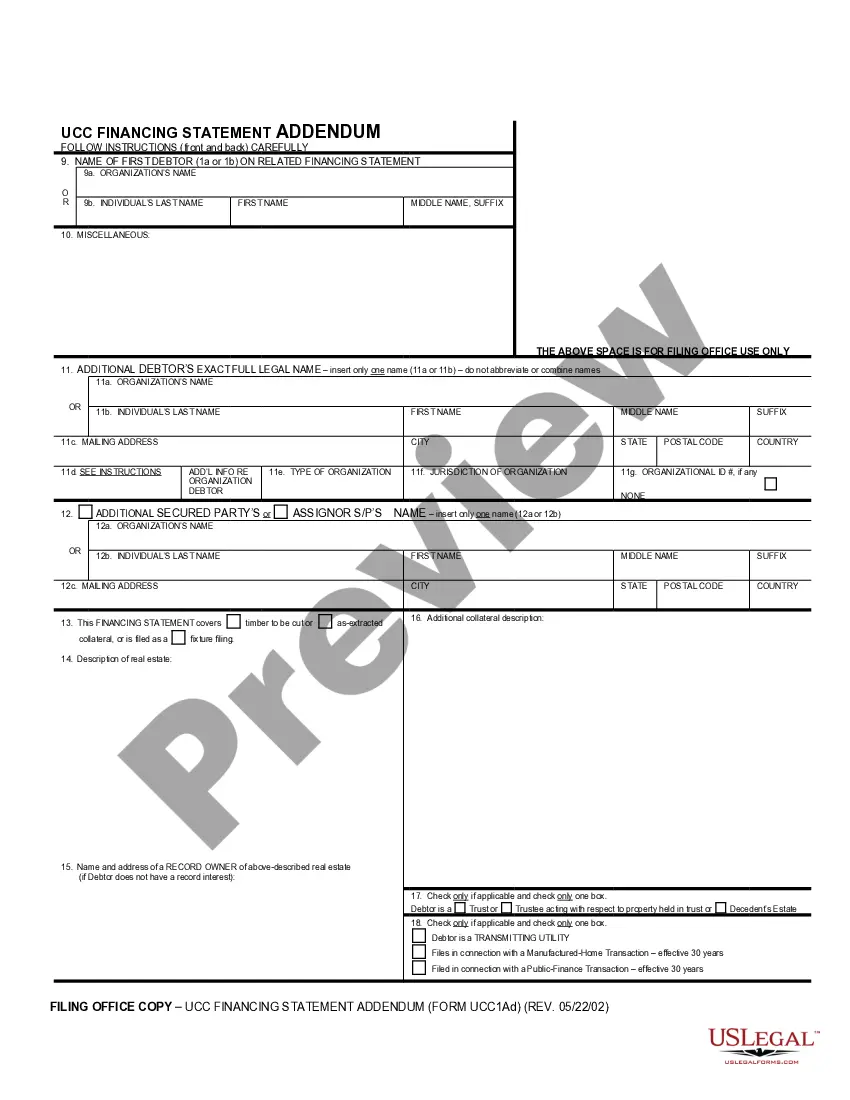
Nebraska UCC1 Financing Statement Addendum
What is this form?
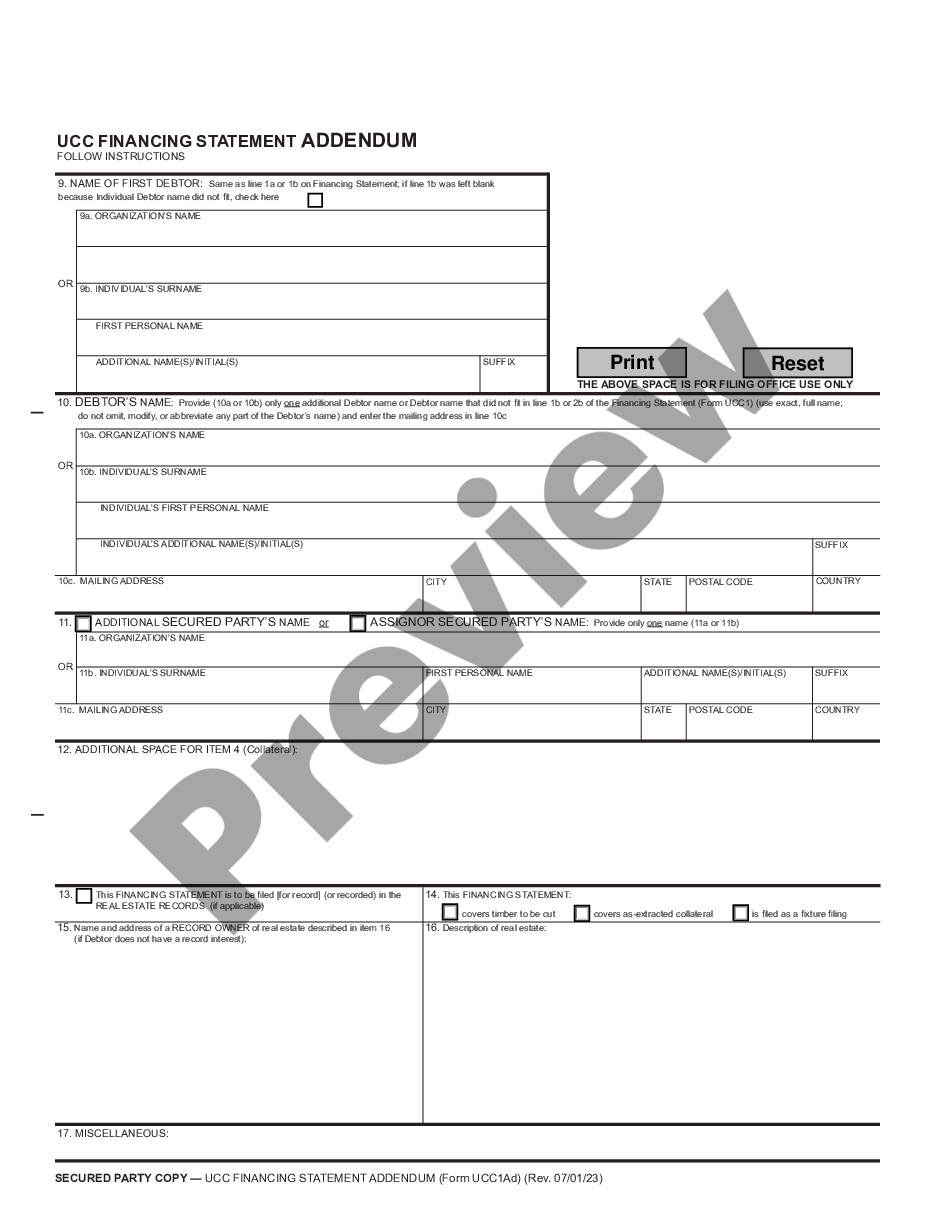
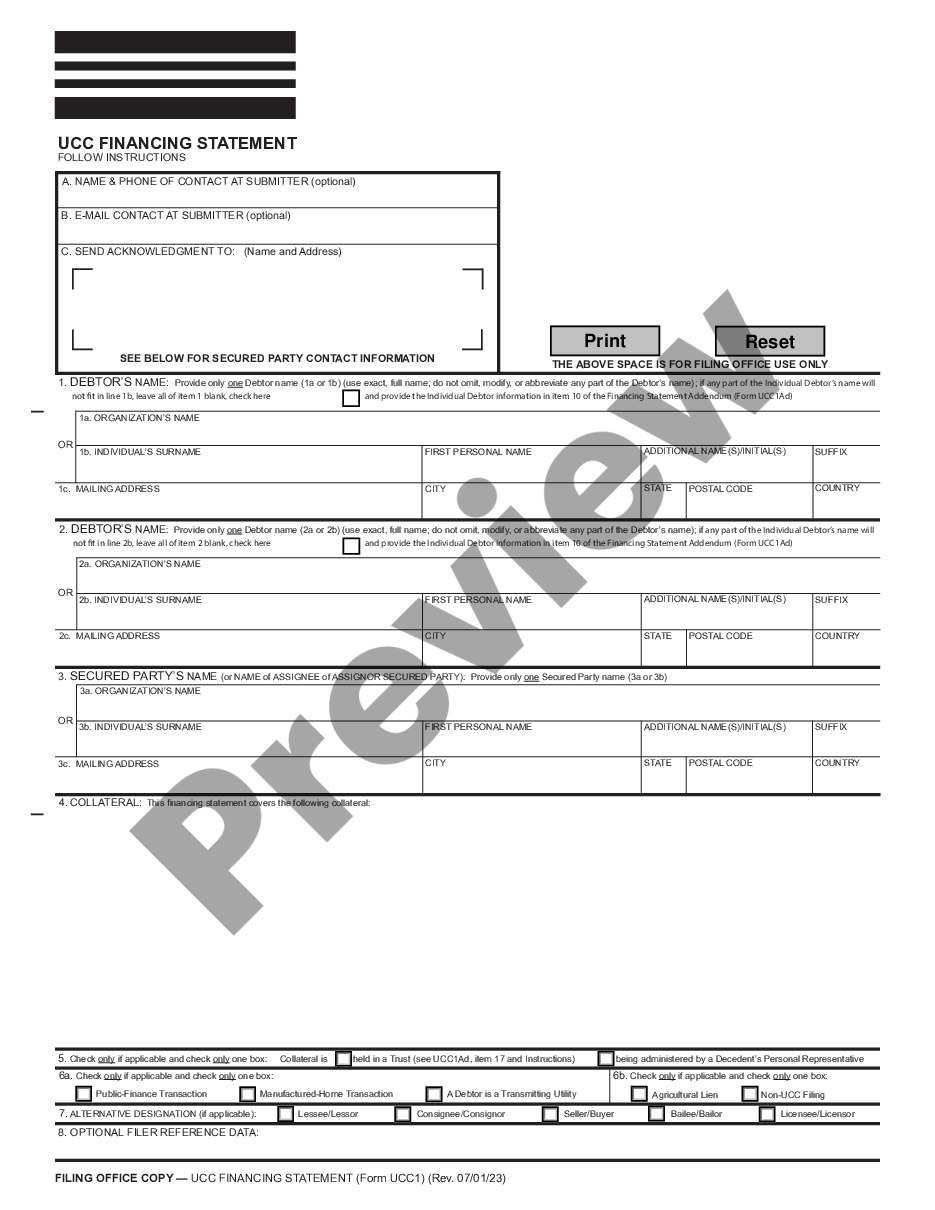
The Nebraska UCC1 Financing Statement Addendum is a legal document used to supplement a UCC1 Financing Statement. Its primary purpose is to add an additional debtor or secured party in relation to collateral specified in the statement. This addendum is particularly important for ensuring that all relevant parties are properly documented, thereby providing a clearer picture of who is responsible for obligations concerning the collateral.
Main sections of this form
- Debtor's name and address: Include the legal names of all parties involved.
- Additional secured party's name: If there is more than one secured party, this section allows you to add their details.
- Description of collateral: Provide a clear and specific description of the collateral associated with the financing statement.
- Real estate information: Necessary if the collateral involves real estate, including details on the record owner.
- Additional notes: A section for any extra information that may be required for clarity.
Situations where this form applies
This form should be used in situations where there is a need to add an additional debtor or secured party after the original UCC1 Financing Statement has been filed. It is commonly employed in lending scenarios, especially when new collateral is introduced, or when existing collateral needs to be redefined or expanded within the financing statement.
Who needs this form
This addendum is intended for:
- Lenders or creditors looking to secure their interest in collateral.
- Businesses expanding their credit agreements.
- Individuals who need to include or update debtors in a financing arrangement.
- Filing officers or legal professionals conducting UCC filings.
Instructions for completing this form
- Identify the existing UCC1 Financing Statement and its debtor(s).
- Provide the additional debtor's complete name and mailing address in the specified fields.
- Complete the description of any new collateral if required.
- Fill in the section for additional secured partyâs name if applicable.
- Review the form for accuracy and completeness before filing.
Does this document require notarization?
This form does not typically require notarization unless specified by local law. It is advisable to check for specific regulations pertaining to UCC filings in Nebraska to ensure compliance.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Mistakes to watch out for
- Entering incomplete names or incorrect addresses for debtors.
- Failing to specify the collateral adequately.
- Not following the filing instructions properly, leading to legal issues later.
- Omitting the additional secured partyâs name when applicable.
Why use this form online
- Convenient access allows for quick completion and filing.
- Editability ensures that the form can be adjusted as necessary before final submission.
- Reliable templates drafted by licensed attorneys help ensure legal compliance.
Quick recap
- The Nebraska UCC1 Financing Statement Addendum is crucial for modifying existing UCC financing statements.
- Accurate completion of this form protects your interests in a secured transaction.
- It is important to follow Nebraska-specific guidelines when using this form.
- Common mistakes can be avoided with careful attention to detail.
Looking for another form?
Form popularity
FAQ
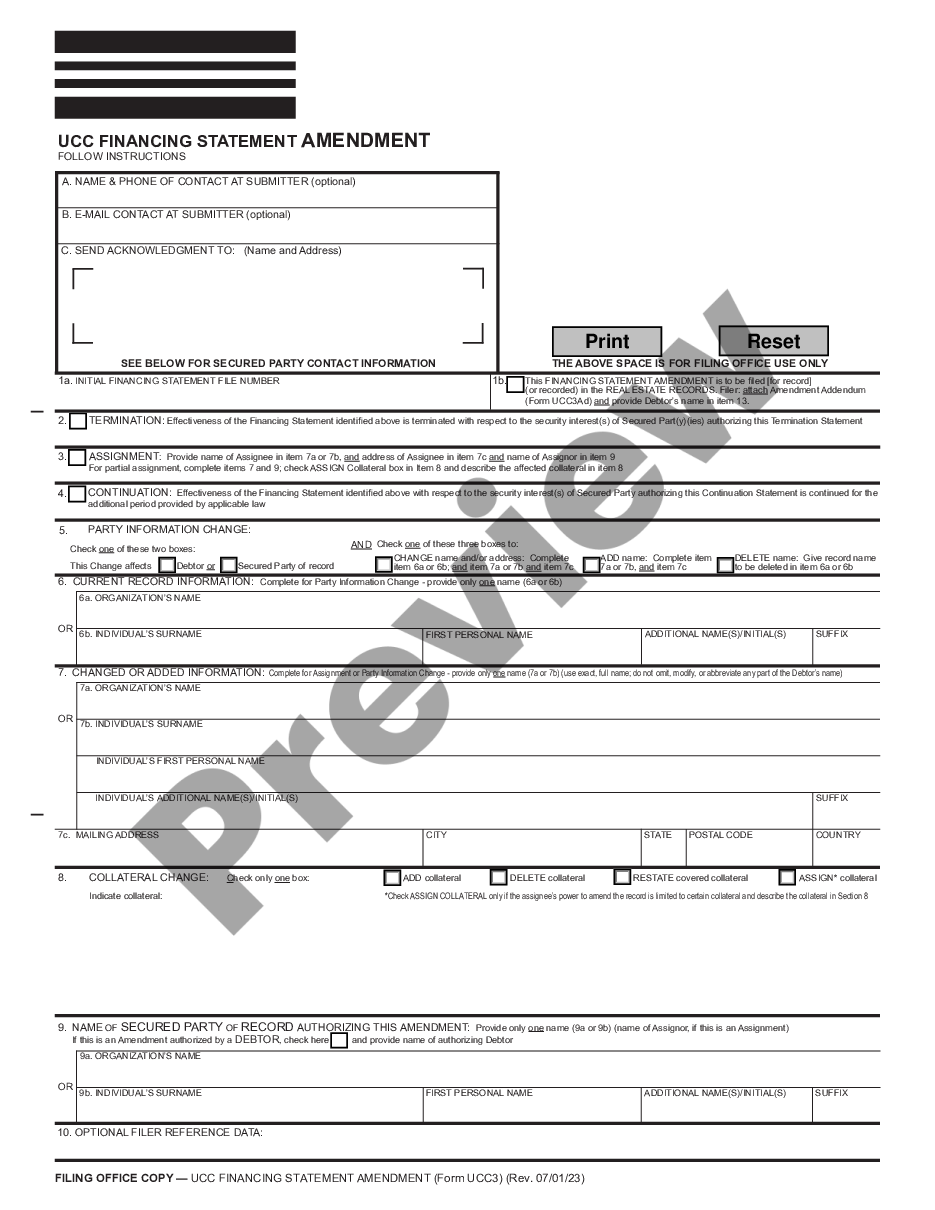
Form UCC3 is used to amend (make changes to) a UCC1 filing.However, it is important to note that for a UCC1 filing a termination is only an amendment and that the UCC1 filing may be amended further, even after a termination has been filed. Box 3 Continuation A UCC1 filing is good for five years.
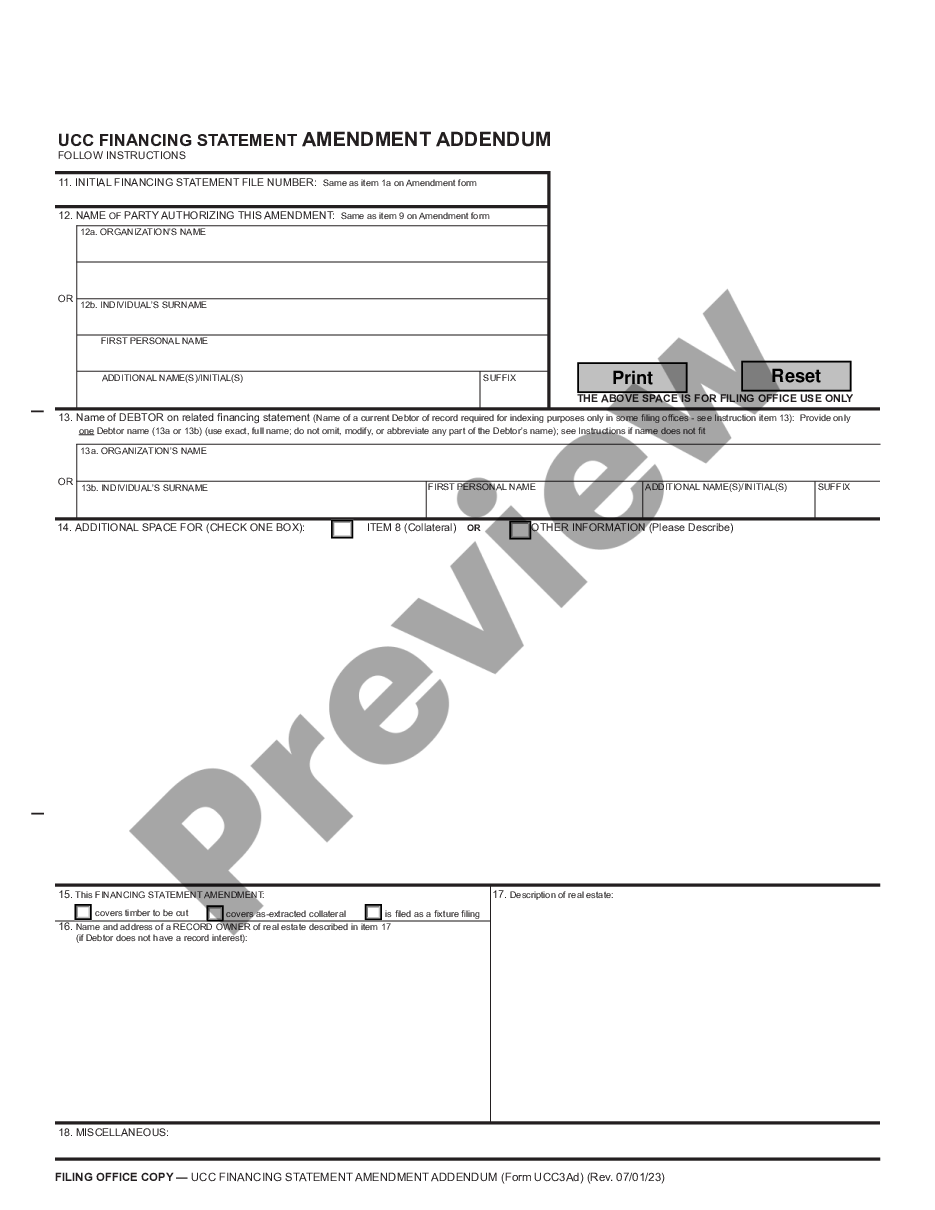
Also known as a UCC-3, and, depending on the context, a UCC-3 financing statement amendment, a UCC-3 termination statement, and a UCC-3 continuation statement. Under the Uniform Commercial Code, a UCC-3 is used to continue, assign, terminate, or amend an existing UCC-1 financing statement (UCC-1).
Rules vary by State around releasing a UCC lien after a borrower satisfied the debt. Primarily there are two main ways to remove them. One way is by having the lender file a UCC-3 Financing Statement Amendment. Another way to remove a UCC filing is by swearing an oath of full payment at the secretary of state office.
How long does a UCC filing last? A UCC-1 filing is good for five years. After five years, it is considered lapsed and no longer valid.
A UCC-1 financing statement (an abbreviation for Uniform Commercial Code-1) is a legal form that a creditor files to give notice that it has or may have an interest in the personal property of a debtor (a person who owes a debt to the creditor as typically specified in the agreement creating the debt).
If you're approved for a small-business loan, a lender might file a UCC financing statement or a UCC-1 filing. This is just a legal form that allows for the lender to announce lien on a secured loan. This allows for the lender to seize, foreclose or even sell the underlying collateral if you fail to repay your loan.
Section 9-503 of the UCC provides various, more specific rules regarding the sufficiency of a debtor's name on a financing statement.However, unlike with a security agreement, on a financing statement it is acceptable to use a supergeneric description of collateral.
The secured party has 20 days to either terminate the filing or send a termination statement to the debtor that the debtor can then file. If this does not happen within the 20-day time frame, the debtor may file a UCC-3 termination statement.