Kansas Second Mortgage Promissory Note
About this form
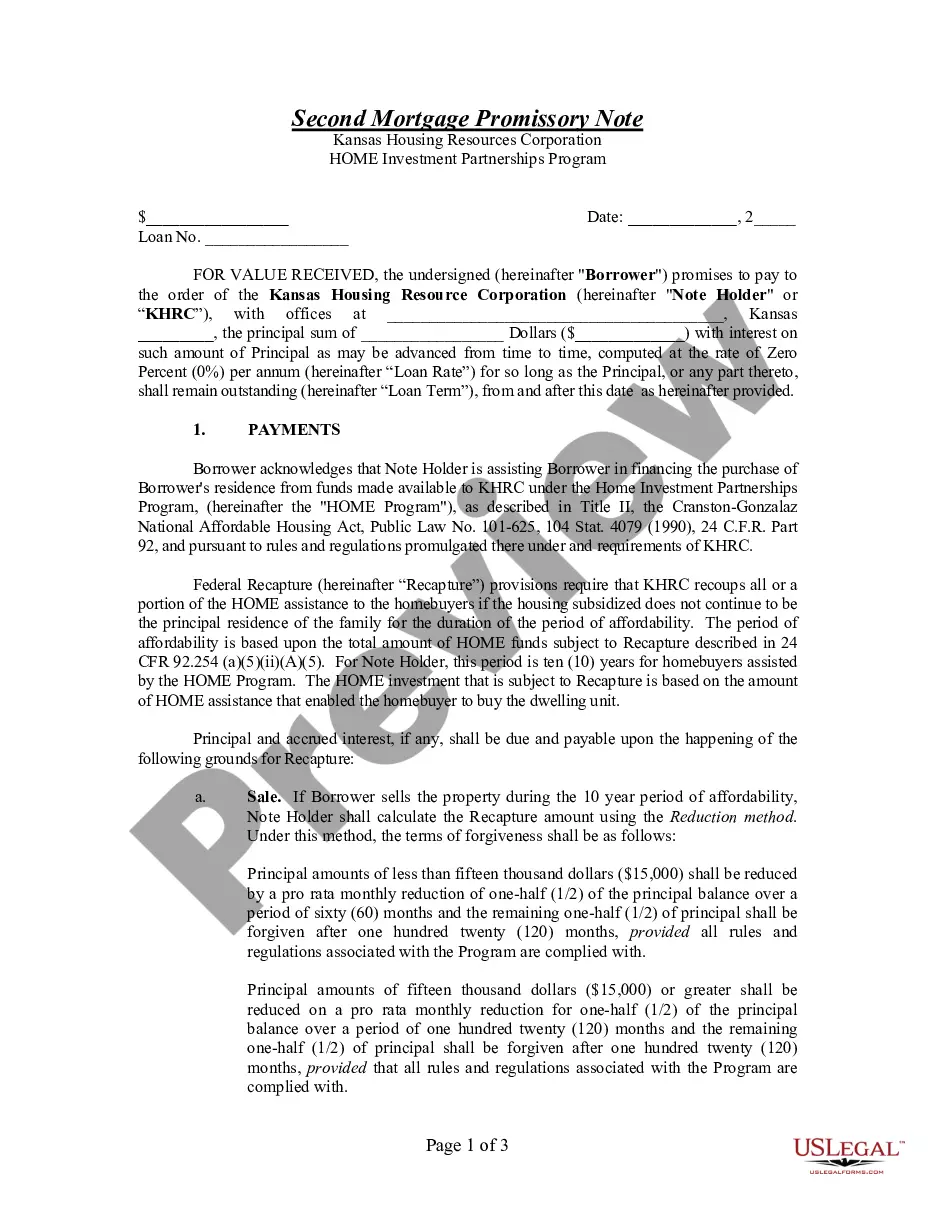
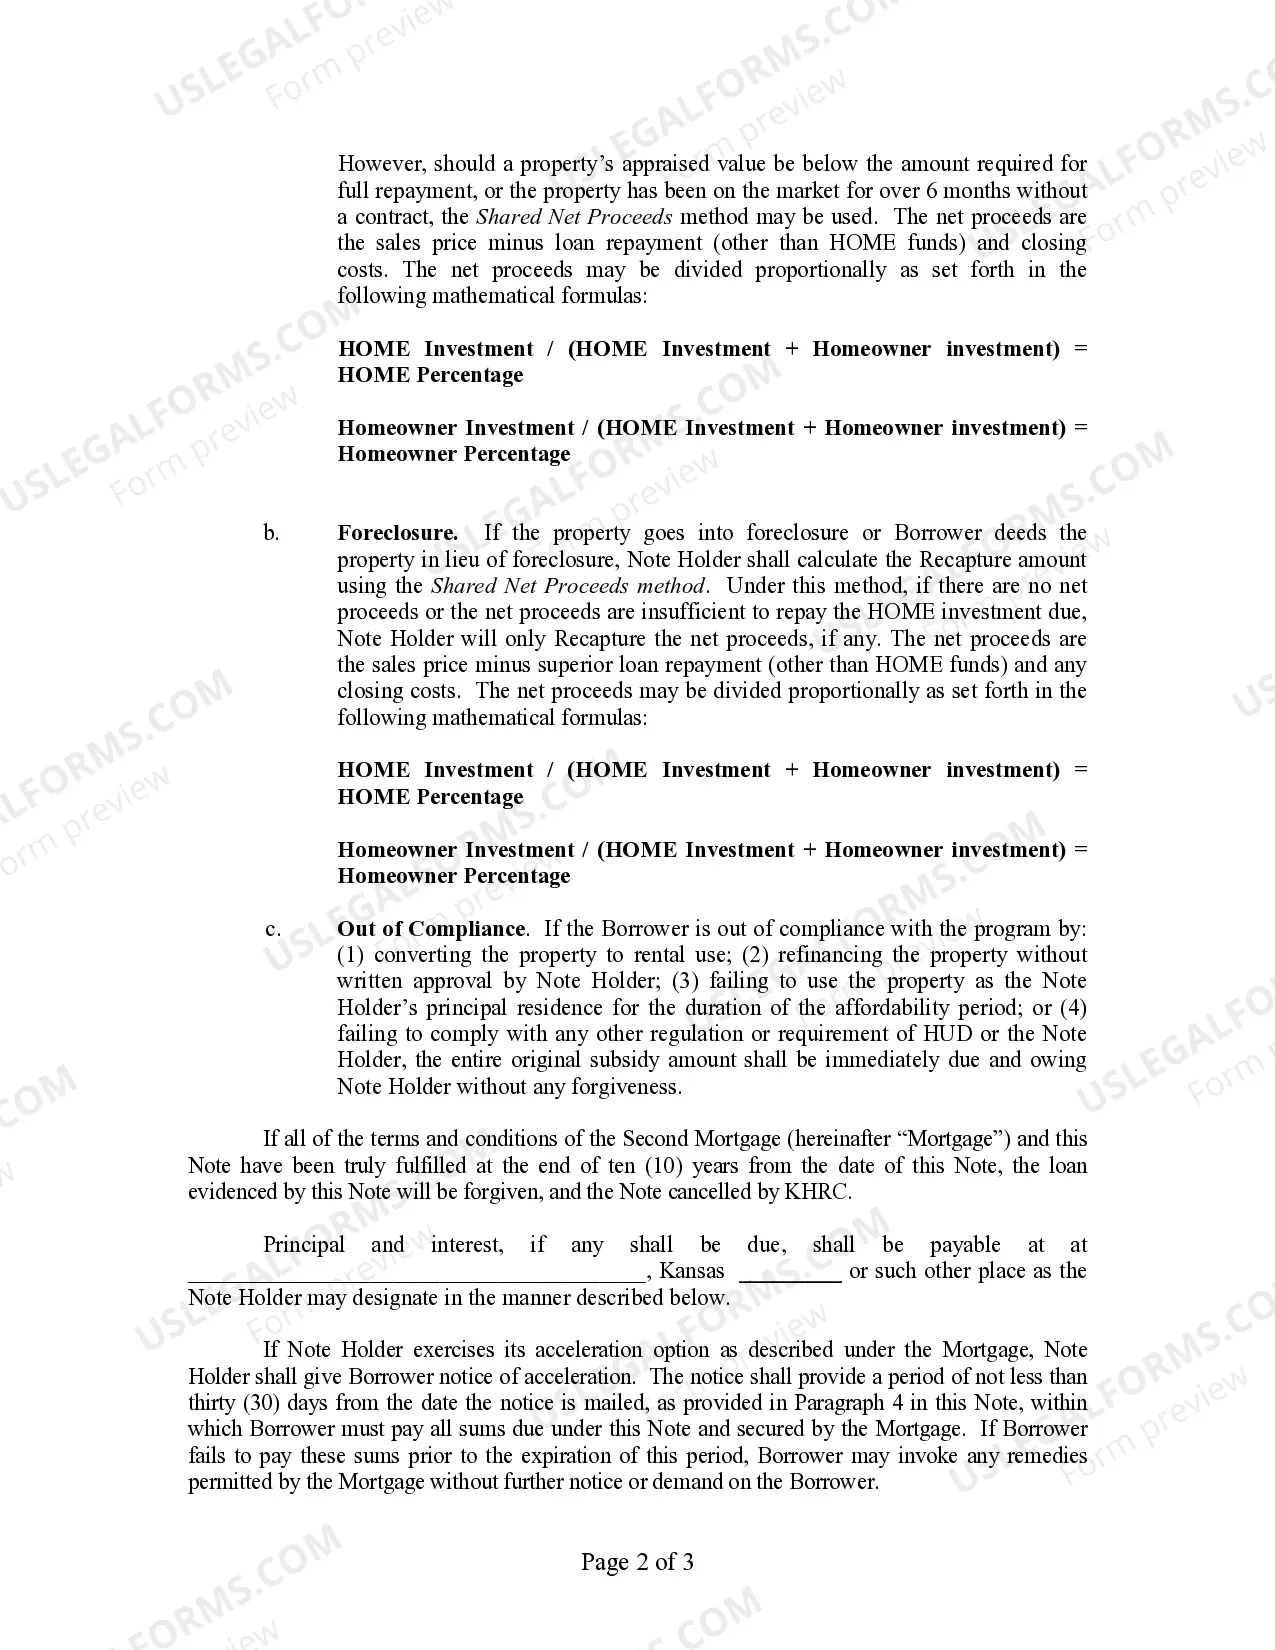
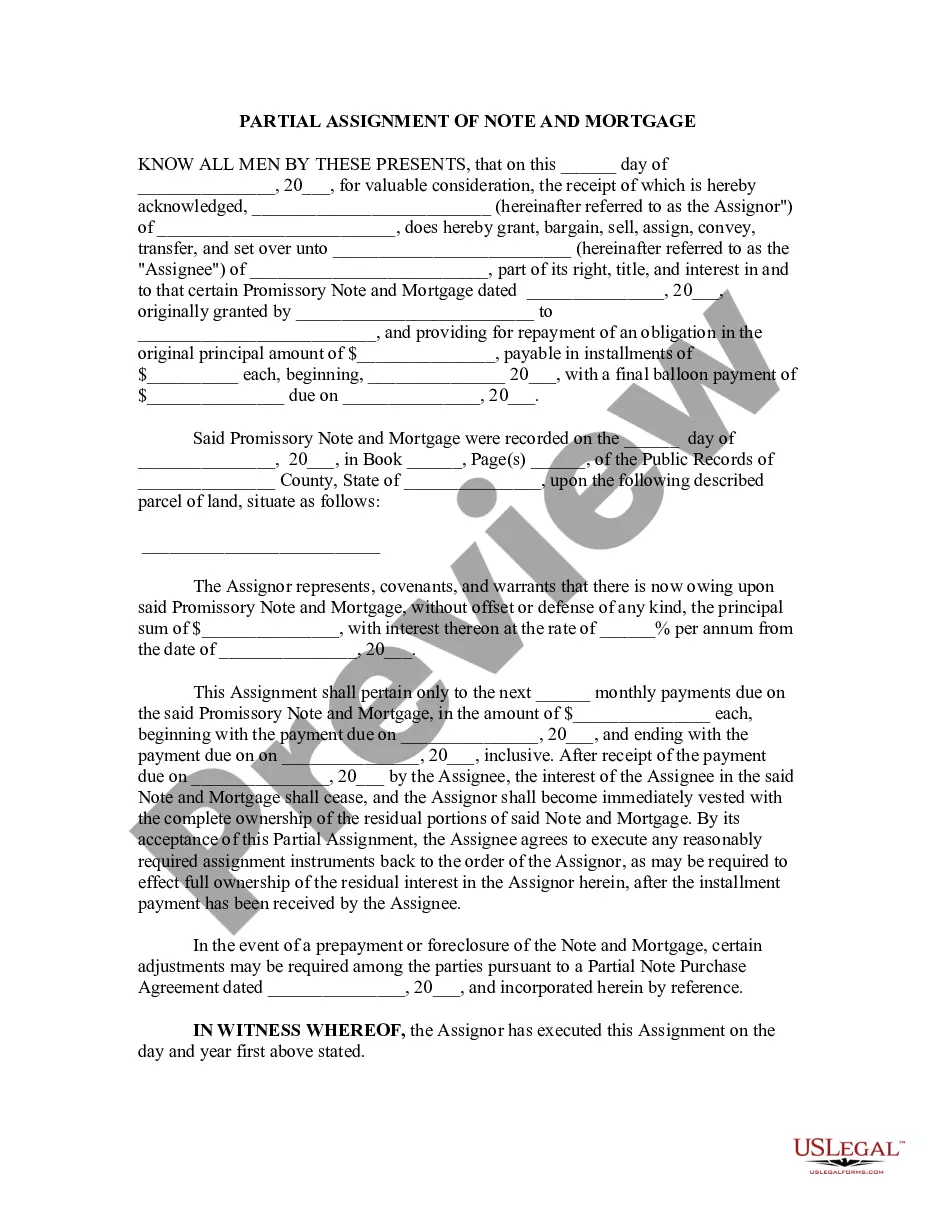
The Second Mortgage Promissory Note is a legal document that outlines the borrower's promise to repay a loan provided by the Kansas Housing Resource Corporation. This loan typically assists with the purchase of a residential property and is part of a federal program designed to promote homeownership. Unlike traditional mortgage notes, this form includes specific recapture provisions that may require repayment of the assistance under certain conditions, such as selling the property within ten years or failing to comply with program regulations.
Key parts of this document
- Parties involved: Borrower and Note Holder details.
- Loan terms: Principal amount, interest rate, and repayment schedule.
- Recapture provisions: Conditions under which funds may need to be repaid.
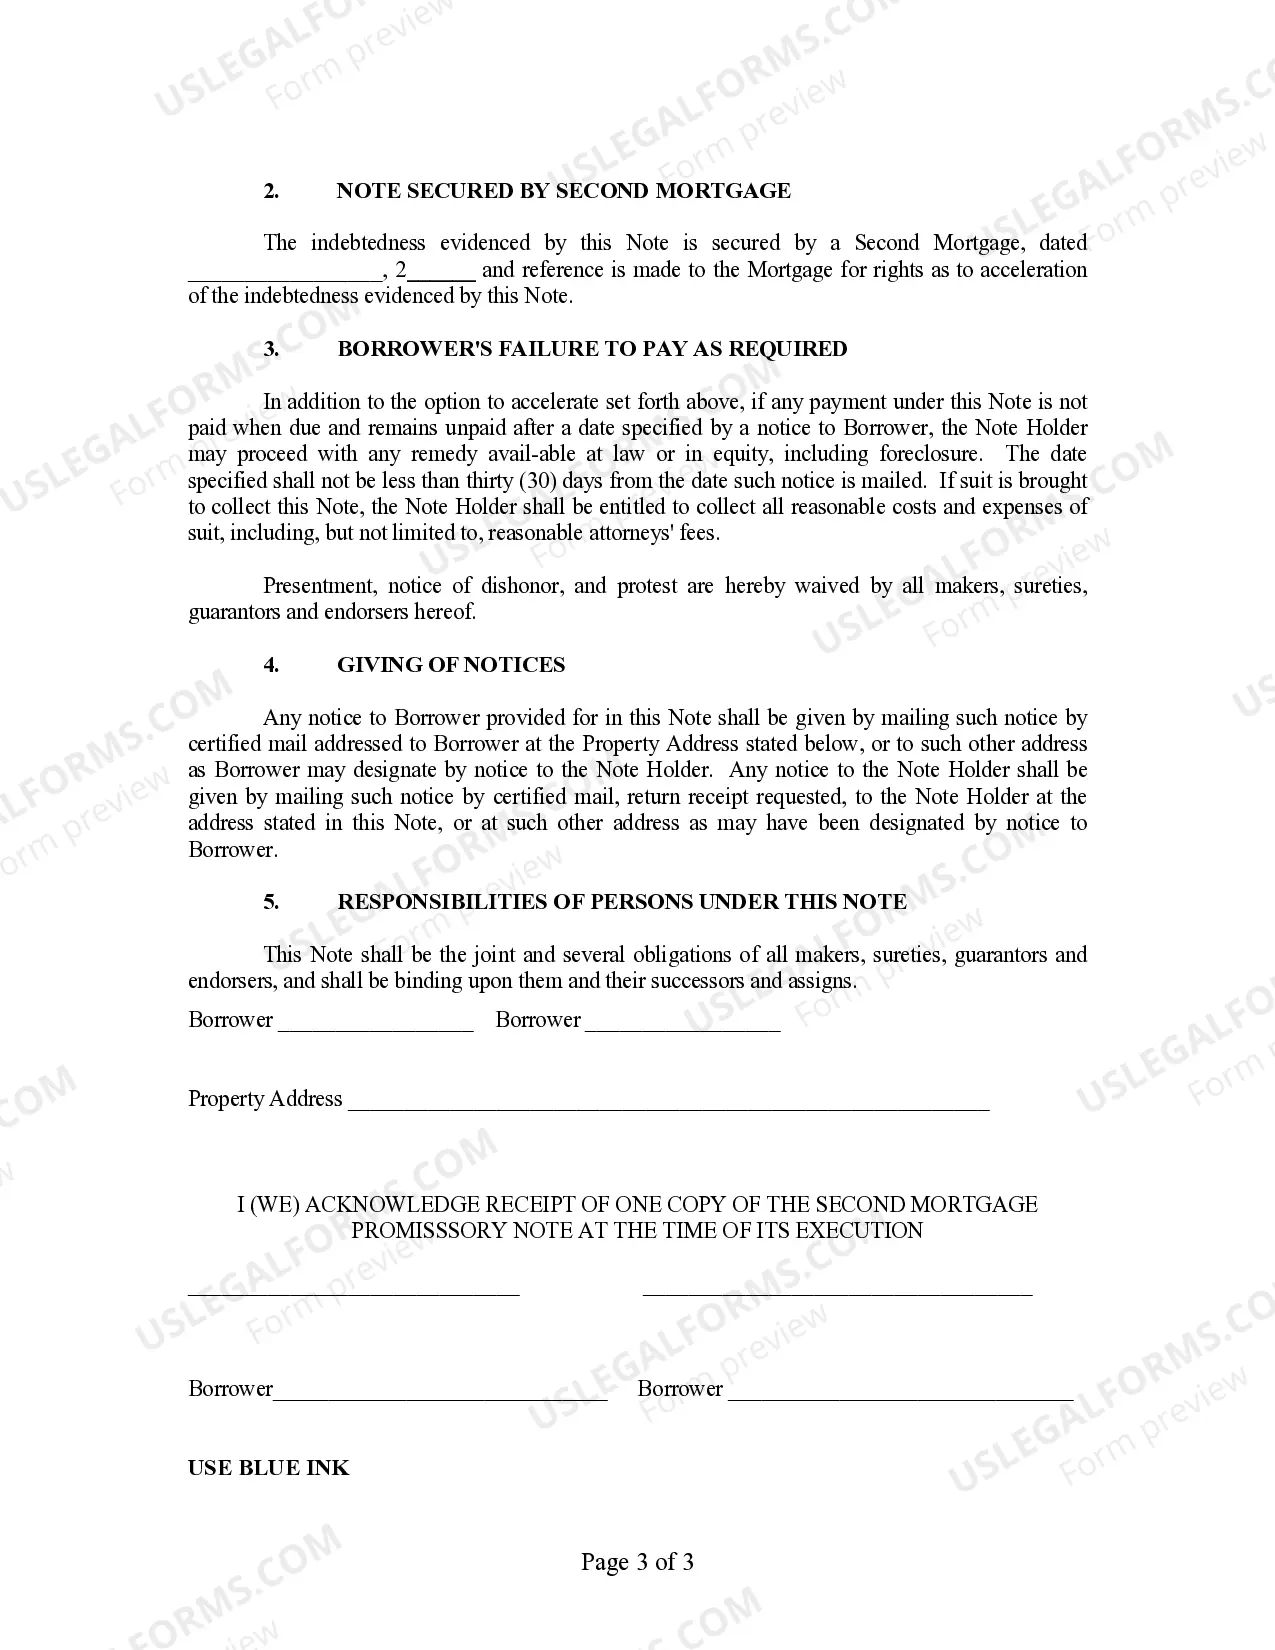
- Grounds for default: Triggers for loan acceleration and remedies for non-payment.
- Signature requirements: Spaces for borrower signatures and acknowledgment.
When this form is needed
This form is used when a borrower seeks financial assistance from the Kansas Housing Resource Corporation to purchase a home under the HOME Investment Partnerships Program. It is essential in cases where federal funds are involved, especially when the borrower intends to reside in the purchased property and needs to understand the obligations associated with the loan.
Who needs this form
- Homebuyers seeking financial assistance from the Kansas Housing Resource Corporation.
- Individuals eligible for the HOME Investment Partnerships Program.
- Borrowers needing to document obligations for a second mortgage explicitly linked to federal funding.
Instructions for completing this form
- Identify the parties involved: Complete the names and addresses of the borrower and Note Holder.
- Specify the loan details: Fill in the loan amount, interest rate, and expected repayment date.
- Review and understand the recapture provisions: Ensure you are aware of circumstances that may trigger repayment obligations.
- Sign the document: Both borrowers must sign the note to validate the agreement.
- Keep a copy: Retain a signed copy for your records after execution.
Is notarization required?
This form does not typically require notarization unless specified by local law. It is advisable to verify any specific requirements that may apply.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Avoid these common issues
- Failing to accurately fill in the loan amount or personal details.
- Not understanding the recapture provisions and their implications.
- Neglecting to get both borrowersâ signatures where required.
Why use this form online
- Easy access: Download and fill out the form at your convenience.
- Editability: Make adjustments as needed before finalizing the document.
- Reliability: Ensures compliance with legal standards and requirements specific to Kansas.
Quick recap
- The Second Mortgage Promissory Note is essential for borrowers receiving assistance under the HOME Program.
- Understanding the loan's recapture provisions is critical to maintaining compliance and avoiding repayment under certain conditions.
- Ensure all necessary information is accurately completed and signed to validate the agreement.
Looking for another form?
Form popularity
FAQ
Borrower's promise to pay is secured by a mortgage, deed of trust or similar security instrument that is dated the same date as this Note and called the ?Security Instrument.? The Security Instrument protects the Lender from losses, which might result if Borrower defaults under this Note.
While all mortgage notes are promissory notes, not all promissory notes are mortgage notes. A promissory note is a legally binding promise from a borrower to repay a loan to their lender. A mortgage note is a document that outlines the terms of a mortgage.
Promissory notes may also be referred to as an IOU, a loan agreement, or just a note. It's a legal lending document that says the borrower promises to repay to the lender a certain amount of money in a certain time frame. This kind of document is legally enforceable and creates a legal obligation to repay the loan.
In fact, a promissory note may be a way for someone who is unable to obtain traditional financing to still buy a home through what is called a take-back mortgage. The financing vehicle effectively allows the home seller to loan a buyer money to purchase the home.
A promissory note is not essential for a mortgage loan. The terms of the loan can be effectively written through other legal documents standard to a loan. Whether your mortgage lender uses a promissory note will depend on their preferred forms.
A promissory note is a document between the lender and the borrower in which the borrower promises to pay back the lender, it is a separate contract from the mortgage. The mortgage is a legal document that ties or "secures" a piece of real estate to an obligation to repay money.
Only the borrower signs a promissory note, whereas both the lender and the borrower sign a loan agreement. Once the document is signed, it means that the borrower agrees to pay back the loan.