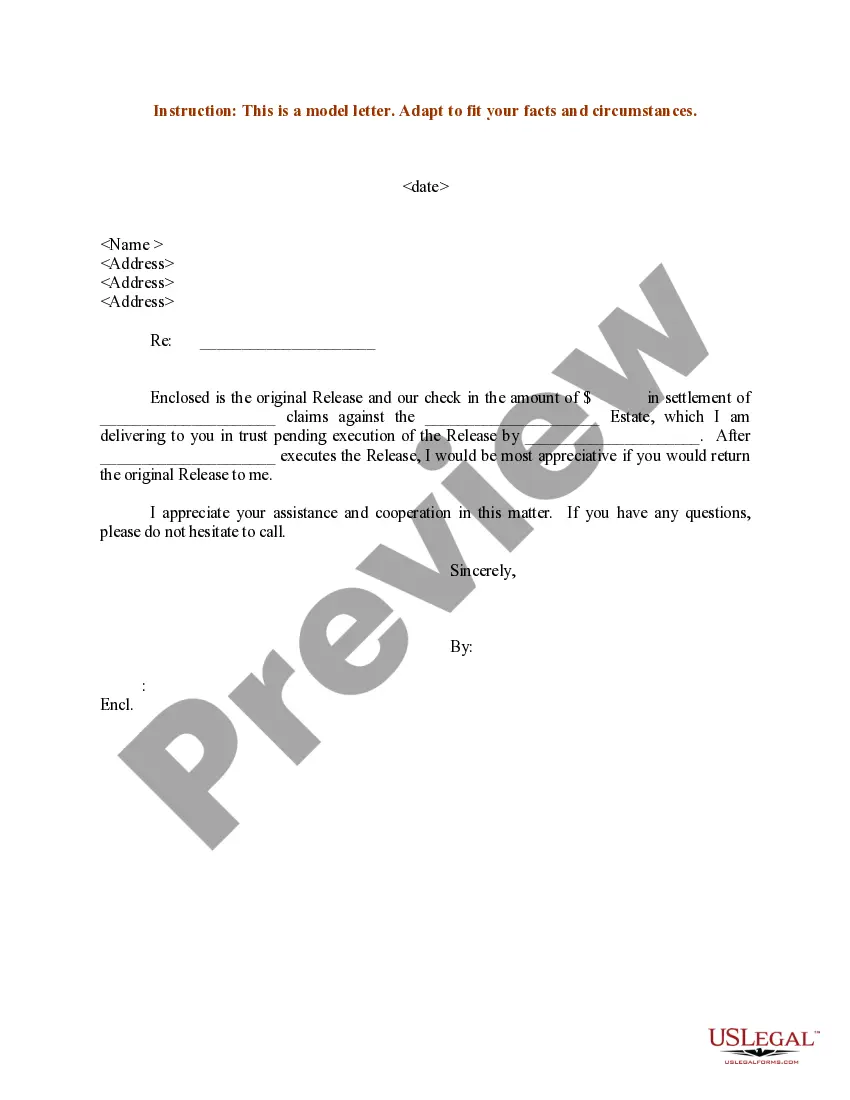
Estate Claim Form With Irs In Pennsylvania
Description
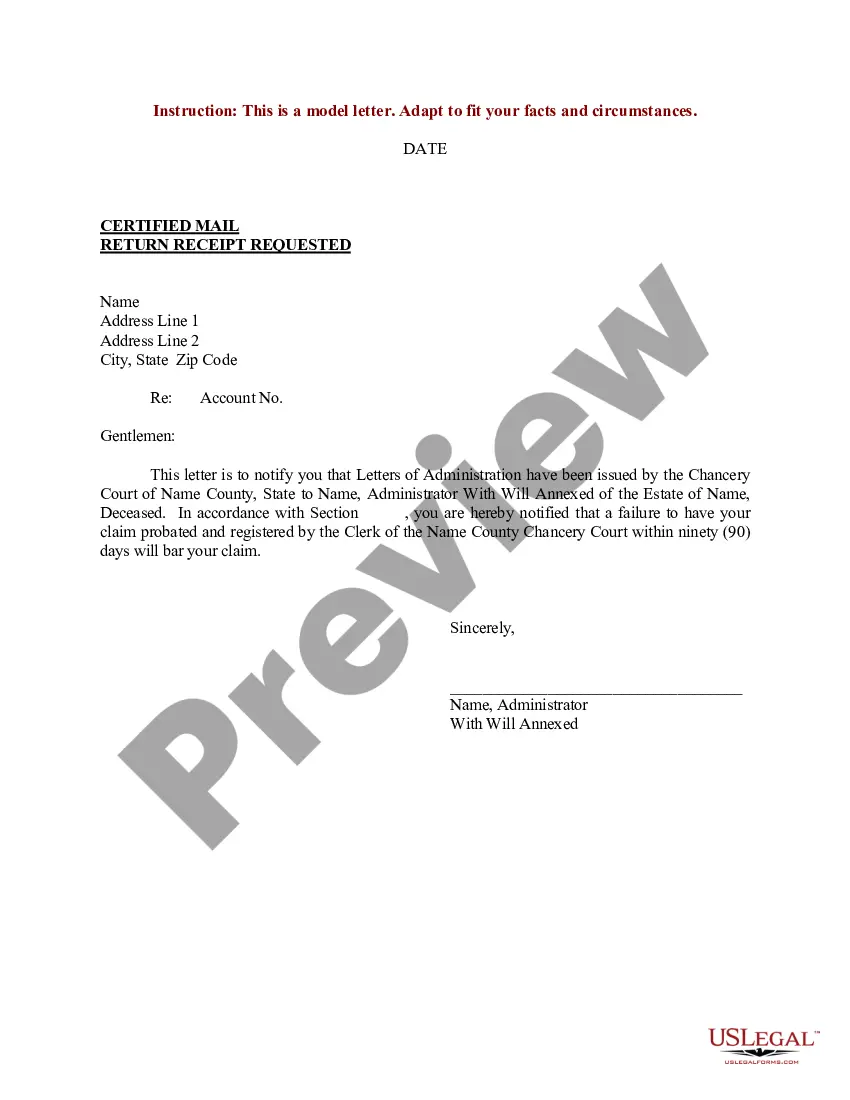
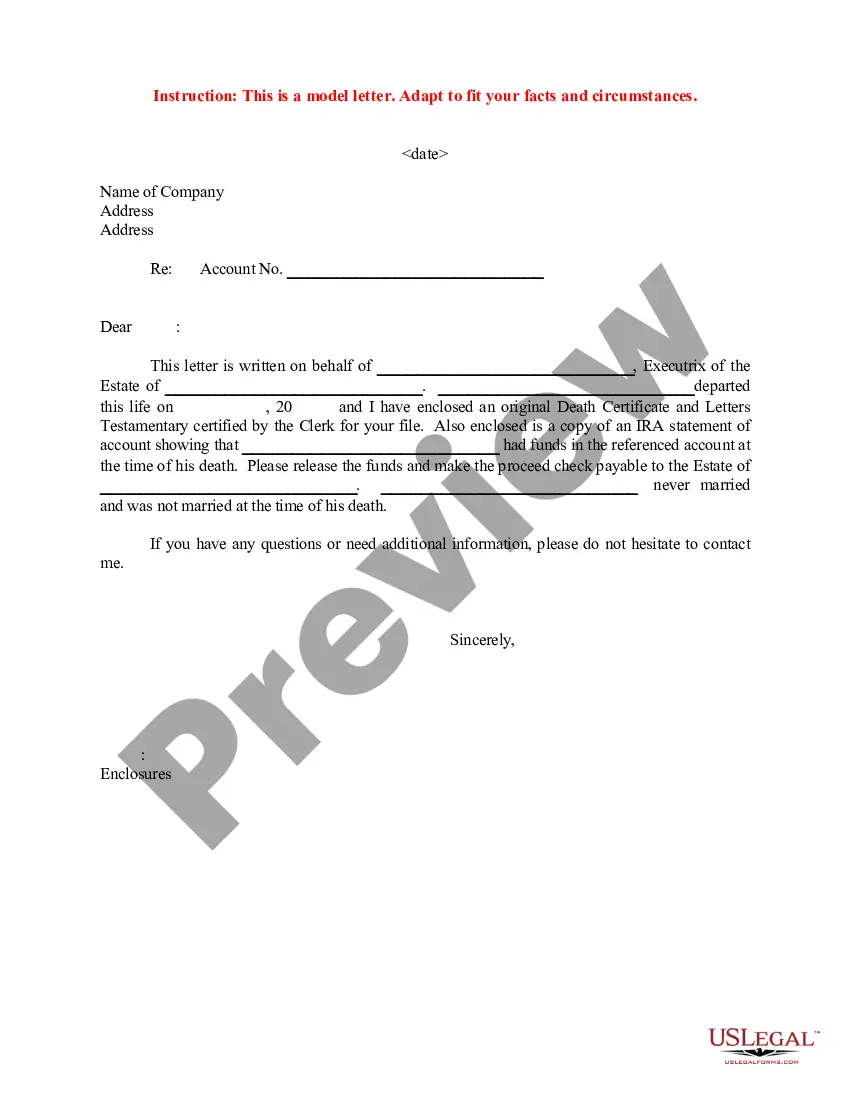
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
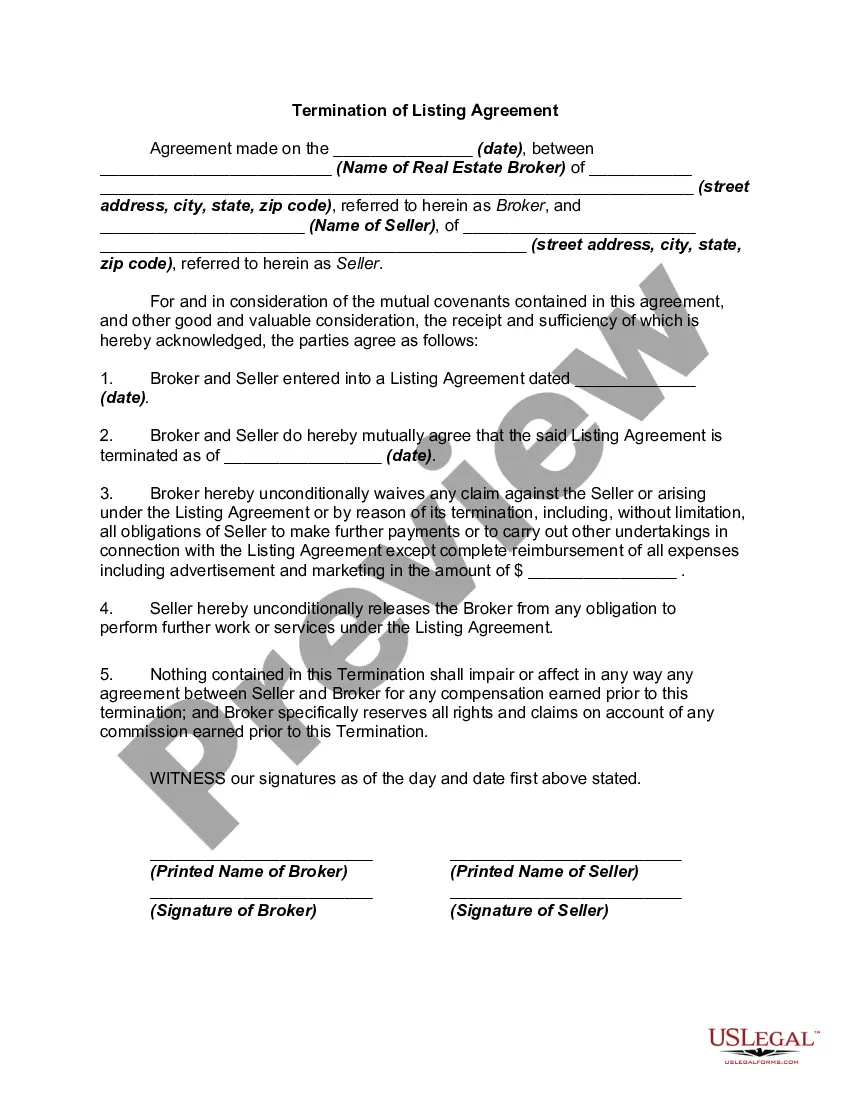


Form popularity
FAQ
While state laws differ for inheritance taxes, an inheritance must exceed a certain threshold to be considered taxable. For federal estate taxes as of 2024, if the total estate is under $13.61 million for an individual or $27.22 million for a married couple, there's no need to worry about estate taxes.
Every resident, part-year resident or nonresident individual must file a Pennsylvania Income Tax Return (PA-40) when he or she realizes income generating $1 or more in tax, even if no tax is due (e.g., when an employee receives compensation where tax is withheld).
For non-residents, the inheritance tax is imposed on all real property and tangible personal property located in Pennsylvania at the date of the decedent's death.
The Gift Tax Return (Form 709) and the Estate Tax Return (Form 706) document your estate planning and provide the “Paper Trail” for the IRS and state departments of revenue. Most of the estate planning techniques must be reported on these tax returns.
An inheritance tax return must be filed for every decedent who has property which is or may be subject to tax. You must file a return if you are: The personal representative.
Jointly Owned Property: Property owned jointly with the right of survivorship is not subject to Pennsylvania inheritance tax. Charitable, government, and similar exemptions: Assets that pass to charitable organizations, government bodies, or non-profit institutions are exempt from Pennsylvania inheritance tax.
The Register of Wills accepts inheritance tax returns and payments on behalf of the Pennsylvania (PA) Department of Revenue. An inheritance tax return must be filed for every decedent (or person who died) with property that may be subject to PA inheritance tax.
The return is to be filed in duplicate with the Register of Wills of the county in which the decedent was a resident at the time of death. Forms and schedules are available on the department's website at revenue.pa or by calling 1-800-362-2050.