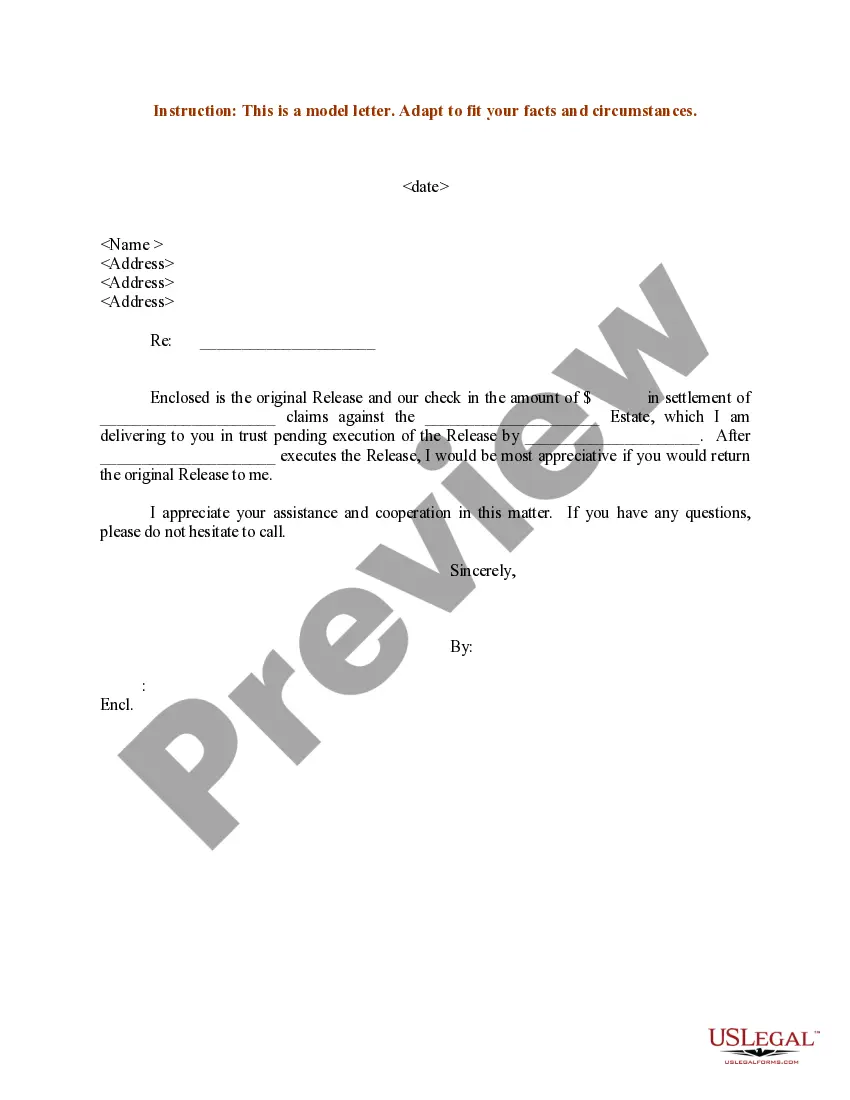
Estate Claim Form With Irs In Maryland
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?


Form popularity
FAQ
Ing to the Internal Revenue Code, the Collection Statute Expiration Date (CSED) for taxes owed is 10 years after the date that a tax liability was assessed. In addition to collecting taxes, the IRS may also audit the tax returns filed by a deceased person in the years prior to his or her death.
Use Form 709 only to report those transfers where the ETIP closed due to something other than the donor's death. (If the ETIP closed as the result of the donor's death, report the transfer on Form 706, United States Estate (and Generation-Skipping Transfer) Tax Return.)
Understanding the Deceased Estate 3-Year Rule The core premise of the 3-year rule is that if the deceased's estate is not claimed or administered within three years of their death, the state or governing body may step in and take control of the distribution and management of the assets.
Maryland Estate Tax Exemption The Maryland estate tax threshold for 2025 is $5 million, and has been since 2019. This means that if you die and your total estate is worth less than $5 million, the estate owes nothing at all to the state of Maryland.
While state laws differ for inheritance taxes, an inheritance must exceed a certain threshold to be considered taxable. For federal estate taxes as of 2024, if the total estate is under $13.61 million for an individual or $27.22 million for a married couple, there's no need to worry about estate taxes.
A return is required for every estate whose federal gross estate, plus adjusted taxable gifts, is valued at $1,000,000 or more (for decedents dying prior to January 1, 2002, other rules apply) if the decedent at date of death was a resident of Maryland, or a nonresident but owned real or tangible personal property in ...
Spouse and Direct or Lineal Heirs For decedents dying on or after July 1, 2000, direct or lineal heirs are exempt from inheritance tax. This includes a spouse, child, grandchild, great-grandchild, stepchild, parent, or grandparent.
To Whom Does the Maryland Inheritance Tax Apply? The Maryland Inheritance Tax applies to all beneficiaries unless they have a specific exemption from the tax. A decedent's spouse, child, stepchild, grandchild, step-grandchild, parent, grandparent or sibling are exempt from paying Maryland Inheritance Tax.
The Maryland estate tax return must be filed directly with the Comptroller of Maryland. The Comptroller will send the return to the Register of Wills for completion of Section III to certify the payment of inheritance taxes. Use the appropriate version of Form MET-1 for the date of the decedent's death.