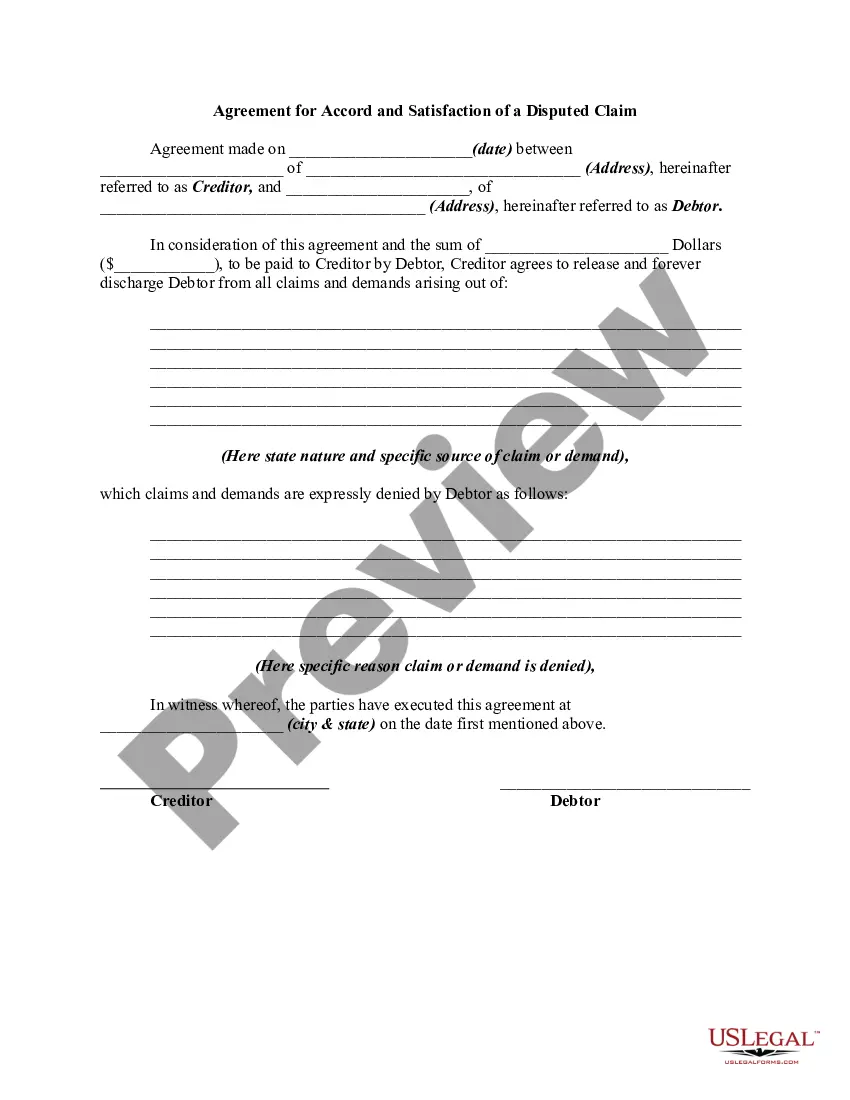
Denied Claim Agreement For Insurance In Bronx
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
Form popularity
FAQ
Steps to Appeal a Health Insurance Claim Denial Step 1: Find Out Why Your Claim Was Denied. Step 2: Call Your Insurance Provider. Step 3: Call Your Doctor's Office. Step 4: Collect the Right Paperwork. Step 5: Submit an Internal Appeal. Step 6: Wait For An Answer. Step 7: Submit an External Review. Review Your Plan Coverage.
Depending on the facts of a particular claim, it could take weeks, months, or even years to settle or otherwise resolve a claim. Once an insurance company has completed its investigation, however, it has 15 days to notify a claimant as to whether it is accepting or denying the claim.
Be persistent Your appeal should include an explanation of your reconsideration request, along with any necessary supporting documentation, such as a copy of the claim in question and copies of earlier communication to the company about the matter.
Some basic pointers for handling claims denials are outlined below. Carefully review all notifications regarding the claim. Be persistent. Don't delay. Get to know the appeals process. Maintain records on disputed claims. Remember that help is available.
If your claim has been denied or your benefits were terminated, and you do not agree with the decision, you have three options: Appeal the decision. File a lawsuit. Negotiate a Settlement.
Filing a No-Fault Claim Generally, if the accident took place in New York State, you should file your No-Fault claim with the insurer of the vehicle you were in when the accident occurred or, if you were a pedestrian, with the insurer of the vehicle that struck you.
If your resubmitted claim is denied and you believe the denial was improper, you may appeal the decision ing to the carrier's guidelines. Make sure you know exactly what information you need to submit with your appeal. Keep in mind that appeal procedures may vary by insurance company and state law.
An insurance claims denial is when—at some point in that process—the insurer deems that the information provided is not relevant or satisfactory, or that the service itself was not provided appropriately, and so withholds payment to the physician.
The insurance company may try to deny your claim for a host of reasons, including: Damages exceeding the limits of the insurance policy coverage. The existing coverage limits already being exhausted. The policy not including the appropriate kind of coverage.