Account Estate Bank Withdrawal In Ohio
Description
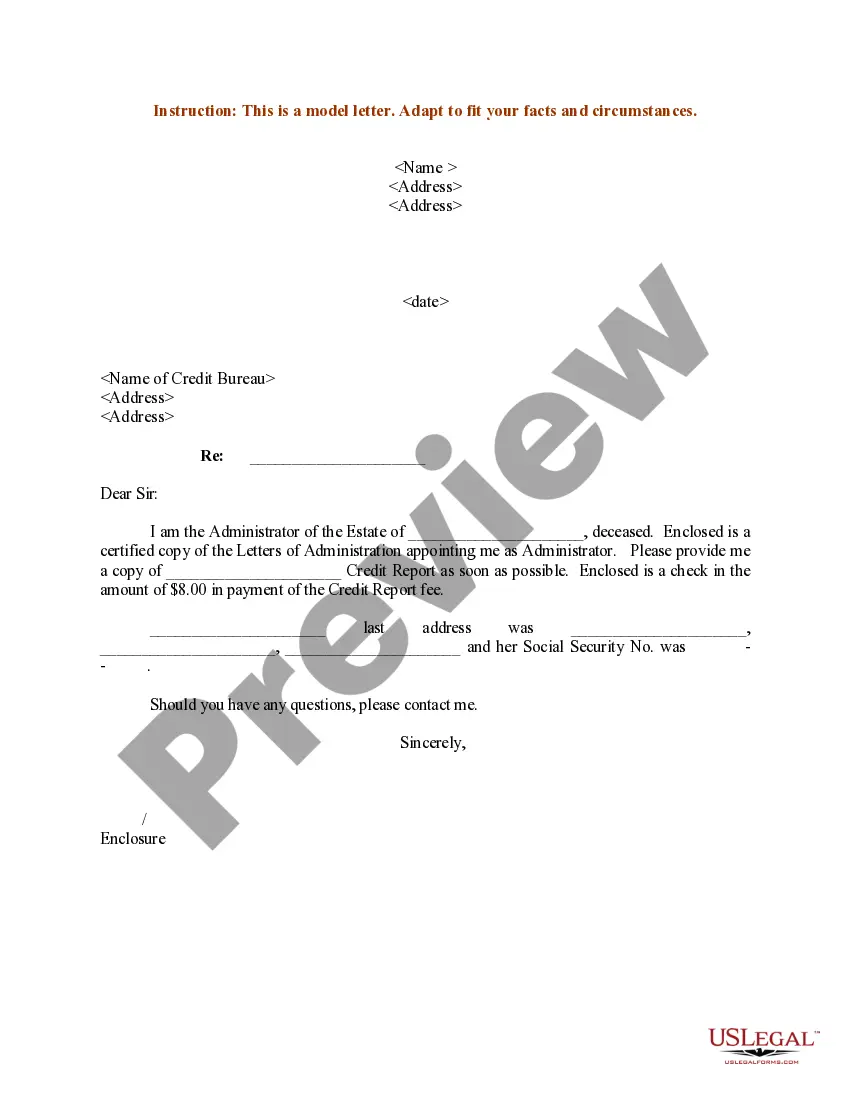
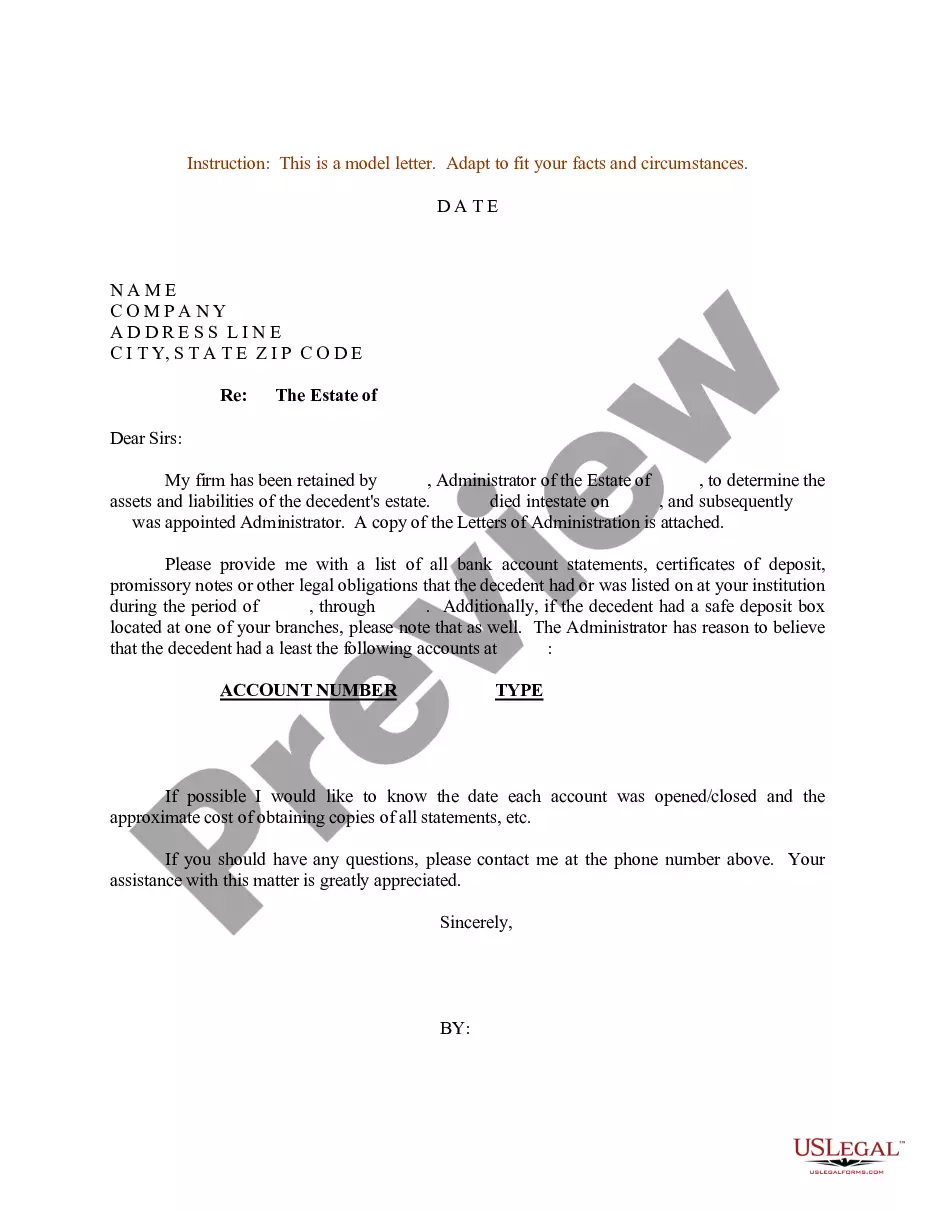
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?



Form popularity
FAQ
All creditors, taxes, and disputes must be settled before the Executor can transfer remaining assets to the heirs and beneficiaries of the Will. Once this is done, the probate estate can be closed.
Keeping an estate open refers to the time between the death and the assets being fully distributed. State laws typically govern the specific timeframe for keeping an estate open after death, but the average is about two years.
State laws typically govern the specific timeframe for keeping an estate open after death, but the average is about two years. The duration an estate remains open depends on how fast it goes through the probate process, how quickly the executor can fulfill their responsibilities, and the complexity of the estate.
In Ohio, you can make a living trust to avoid probate for virtually any asset you own—real estate, bank accounts, vehicles, and so on. You need to create a trust document (it's similar to a will), naming someone to take over as trustee after your death (called a "successor trustee").
Banks generally cannot close a deceased account until after the person's estate has gone through probate or has otherwise settled. Joint accounts that are held together with a surviving owner are not considered deceased accounts. Ownership of these accounts reverts to the surviving owner.
Non-Probate Property in Ohio Real estate held in joint or survivorship form. Assets and property with a transfer-on-death designation. Insurance proceeds with a named beneficiary. Payable-on-death bank accounts. Assets held in trust.
Respected Sir/Madam, I am writing to you with a heavy heart to inform you of the demise of my husband, Mr. Rajeev Singh, who had a savings account in your esteemed bank. It is a difficult time for our family, and I need to settle his financial affairs.
What Not to Do When Someone Dies: 10 Common Mistakes Not Obtaining Multiple Copies of the Death Certificate. 2- Delaying Notification of Death. 3- Not Knowing About a Preplan for Funeral Expenses. 4- Not Understanding the Crucial Role a Funeral Director Plays. 5- Letting Others Pressure You Into Bad Decisions.
The bank is likely to ask for two forms of your identification (usually a passport or driver's licence, or a proof of address with a utility bill) and a copy of the will. If there's no will, the bank could ask for evidence of your relationship to the deceased. You'll also need the death certificate.
A deceased person's bank account is inaccessible unless you're a joint owner, a beneficiary of the account or the estate executor.