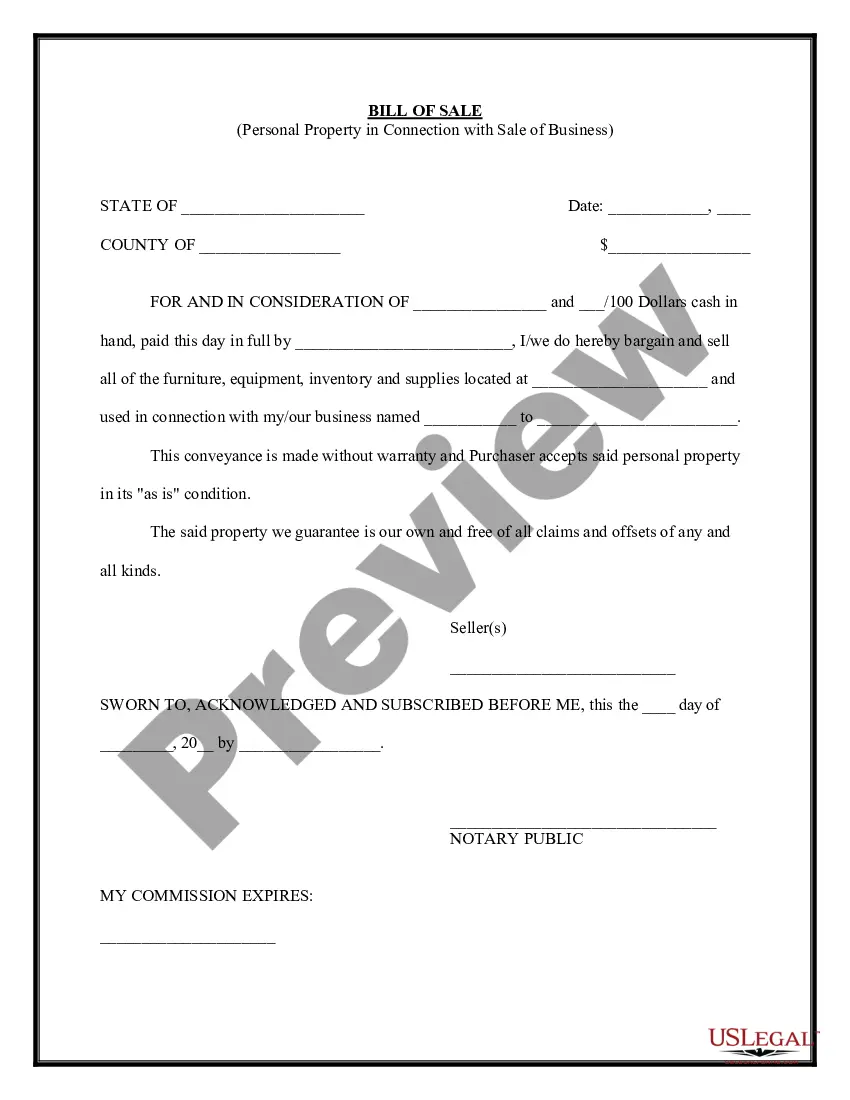
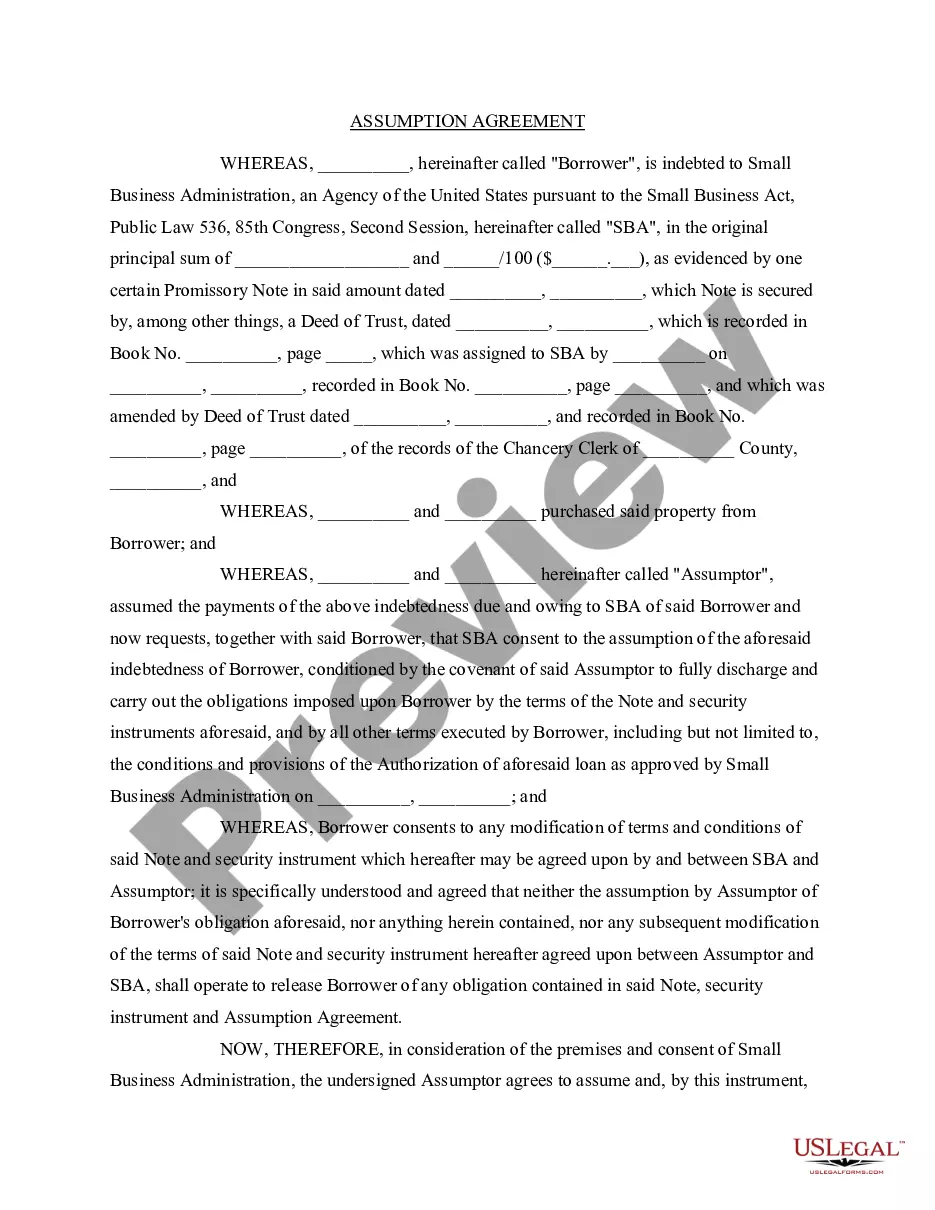
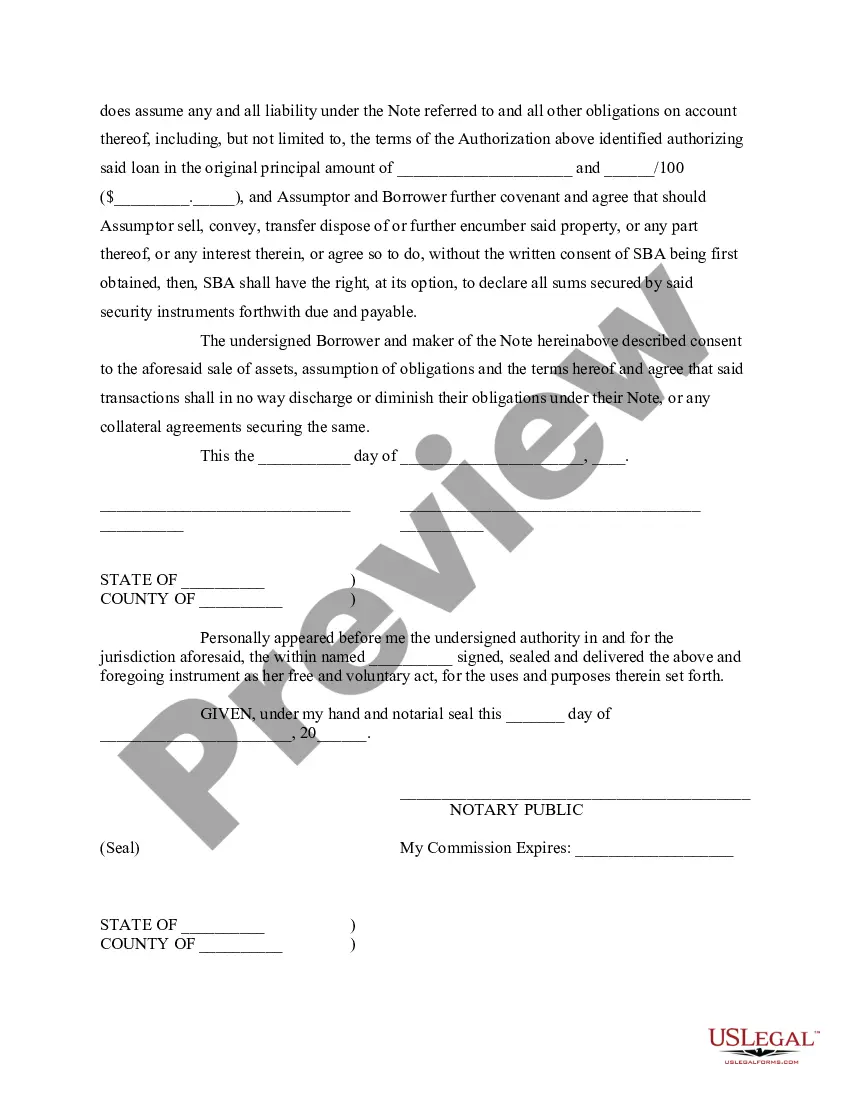
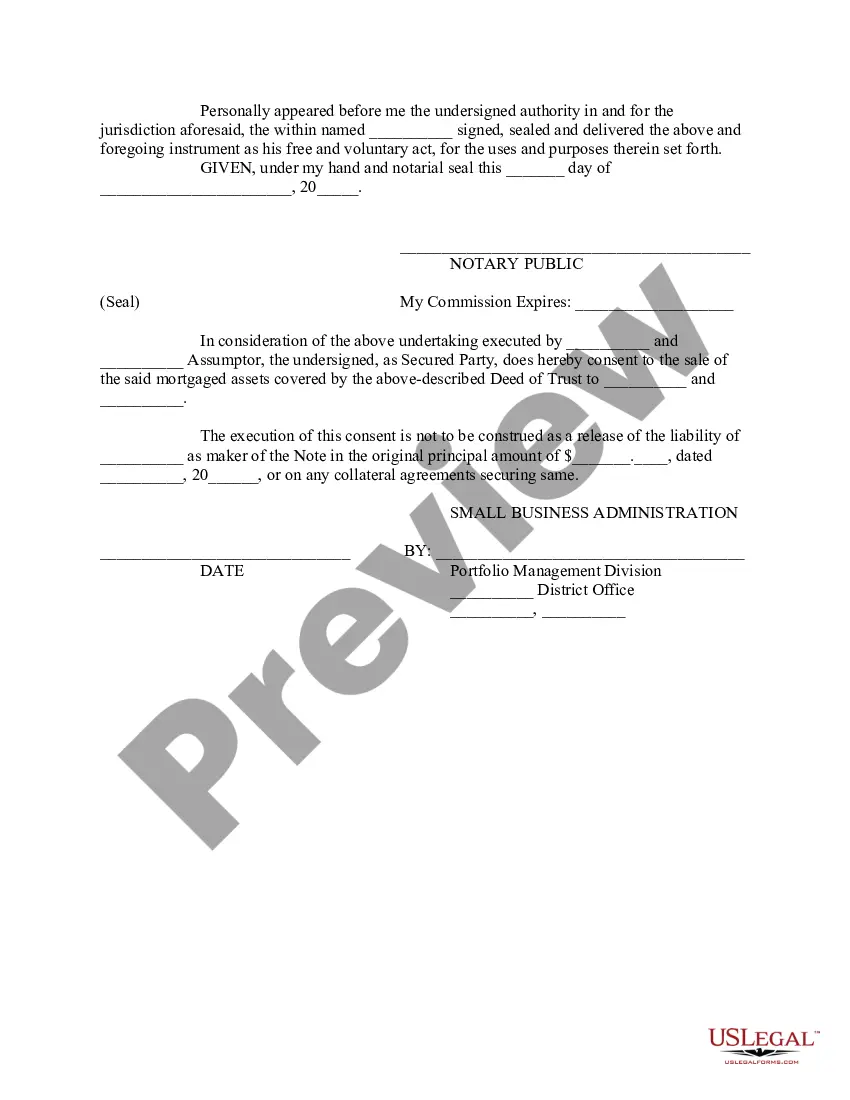
Sba Loan Agreement With Guarantor In Philadelphia
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?



Form popularity
FAQ
All loans insured by the SBA require a personal guarantee from every owner with a 20 percent or greater equity stake in the business.
The field office must have a written request from the borrower, the guarantor to be released, or the proposed substitute. (3) Consent of other parties. The written consent of all parties (e.g., other guarantors, standby creditors, etc.) must be obtained before the transaction is finalized.
Benefits of SBA-guaranteed loans Unique benefits: Lower down payments, flexible overhead requirements, and no collateral needed for some loans.
Individuals who own 20% or more of a small business applicant must provide an unlimited personal guaranty. SBA Lenders may use this form.
Pursuant to 13 CFR § 120.160(a), all SBA 7(a) loans must be guaranteed by at least one person or entity. Generally, guarantees are required of any individual or entity who owns 20% or more of a borrower entity.
A limited guarantee is a legal contract in which a party promises to fulfill a specific obligation. Limited guarantees are usually very restrictive contracts and apply to only one transaction. For example, a limited guarantee would be used for a private equity buyout with a set dollar limit.
Unlimited and limited personal guarantees are both promises that borrowers make to lenders. The difference is that unlimited personal guarantees aren't capped, whereas limited personal guarantees are capped.
A company limited by guarantee (CLG) is a type of company where the liability of members in the event the company is wound up is limited to a (typically very small) amount listed in the company's articles or constitution. Most have no share capital, although rare exceptions exist.