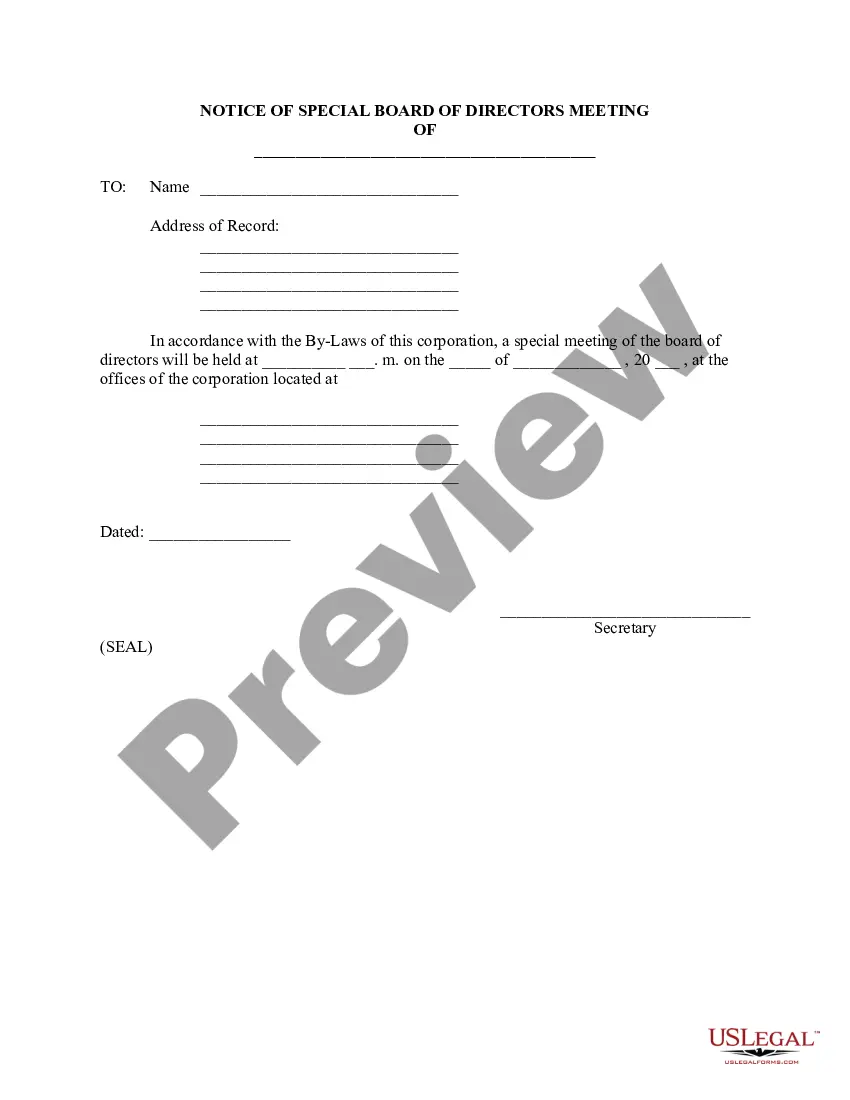
Special Meeting Of Creditors In Orange
Description
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?

Form popularity
FAQ
At the meeting, the debtor (the person who filed for bankruptcy) answers questions under oath about the bankruptcy paperwork that they submitted. The debtor may also be asked about their property, debts, income, and expenses. Creditors may join the meeting and ask the debtor questions, too.
Now, in most consumer cases, creditors don't attend the 341 meeting, even though it's called the meeting of creditors. In probably 95, if not 98% of cases, no creditors actually attend. It's only going to be the trustee that will be asked some questions to verify your financial situation.
Votes of related creditors If directors and shareholders, their spouses, relatives and other entities controlled by them are creditors of the company, they are entitled to attend and vote at creditors' meetings, including the meeting to decide the company's future.
As outlined above, at the creditors' meeting, the creditors are given an opportunity to nominate their own liquidator. The company will already have nominated its choice of liquidator and if the creditors do not propose an alternative, the company's liquidator will be automatically appointed.
It is not a court hearing, and there is no judge. Instead, the meeting is conducted by a trustee. At the meeting, the debtor (the person who filed for bankruptcy) answers questions under oath about the bankruptcy paperwork that they submitted.
You can appoint an individual as proxy to attend and vote at a meeting on your behalf. Creditors who are companies will have to nominate a person as proxy so they can participate in the meeting.
What Will the Trustee Ask Me About at the Meeting of Creditors? The trustee can ask you about anything related to your financial situation, and most questions will involve your debts, assets, income, expenses, and, importantly, prior transactions.
The creditors of the company must be given at least 10 days' notice of the creditors' meeting. Notice of the meeting must also be advertised in two daily newspapers circulating in the area of the registered office of the company or the area in which the company carried on business.
The “meeting of creditors” also known as a “341 meeting,” is a required step in the bankruptcy process. It is not a court hearing, and there is no judge. Instead, the meeting is conducted by a trustee.
Under the Act, the administrative receiver must not only notify all creditors of his appointment within 28 days but, unless the company goes into liquidation, he must within three months of his appointment, call a meeting of creditors (section 48) on 14 days' notice and present a report dealing with the events leading ...