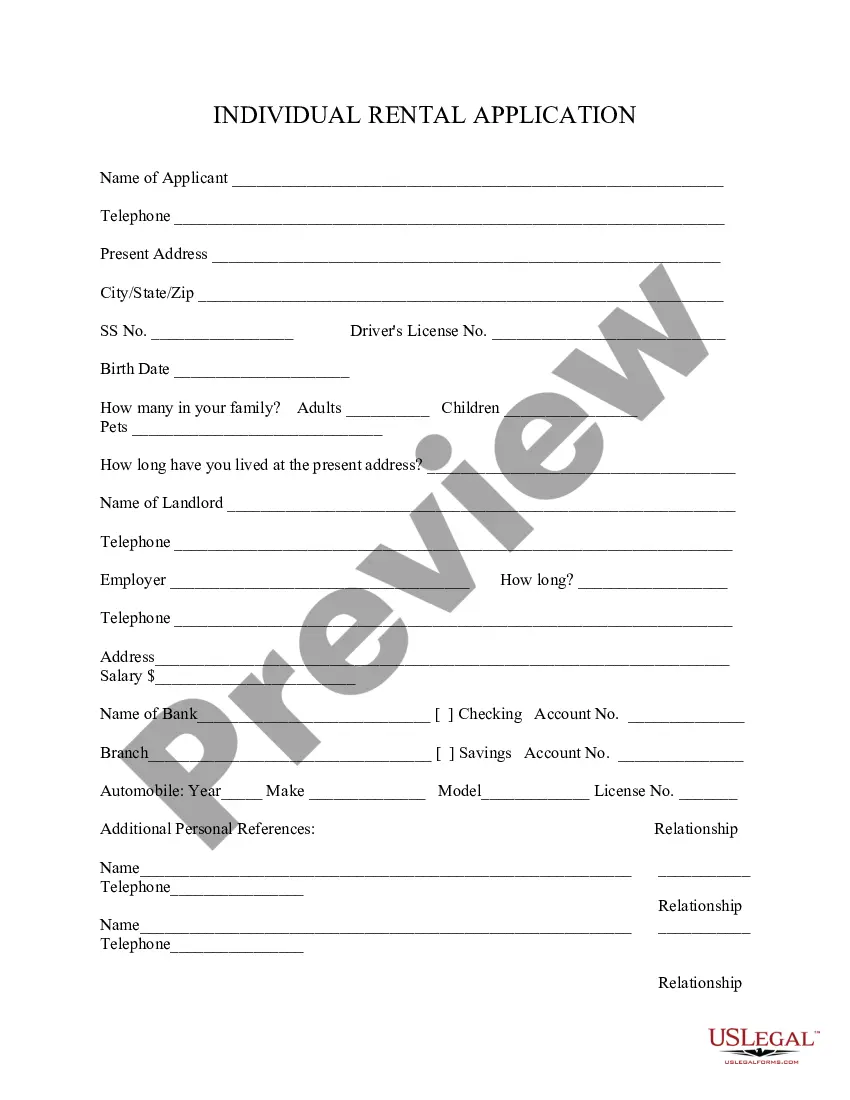
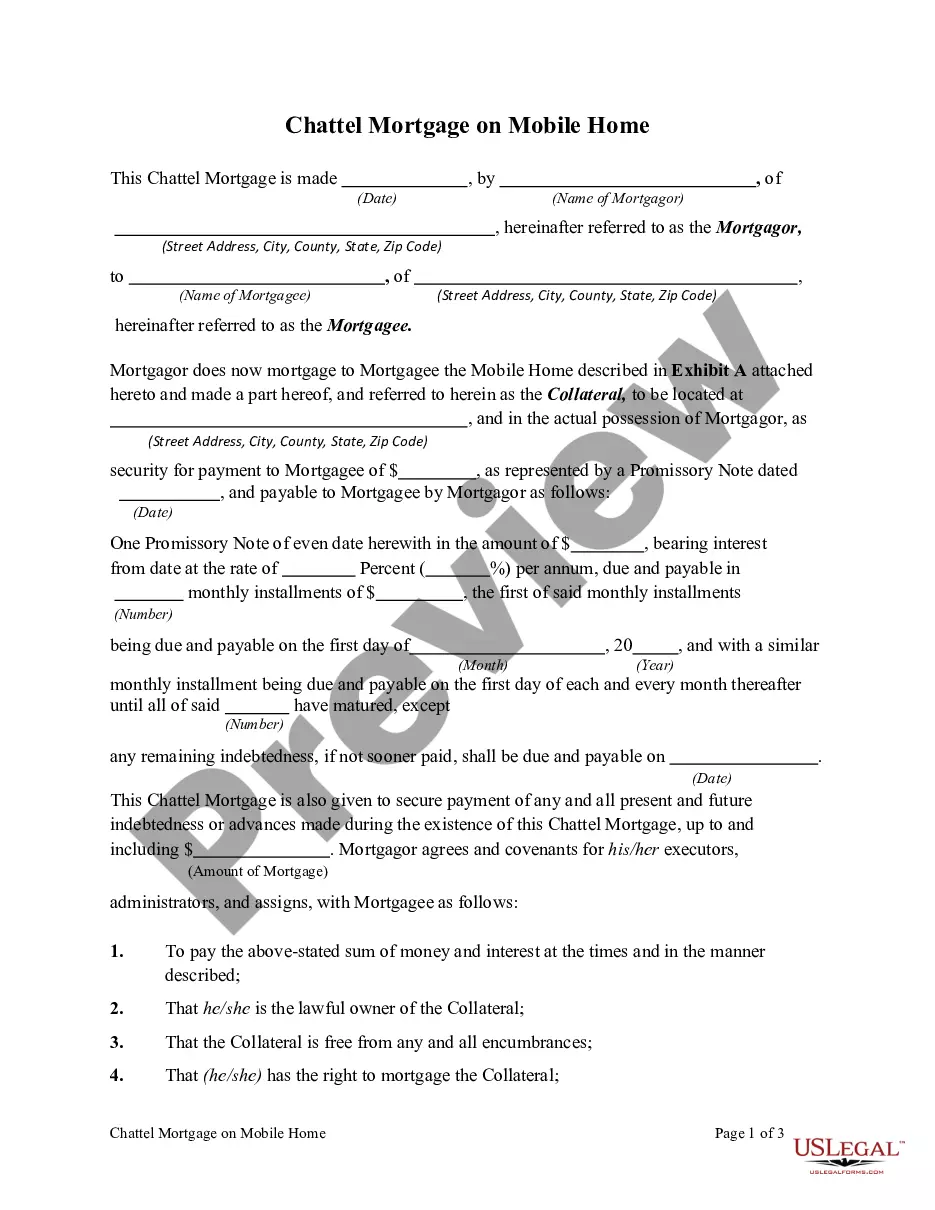
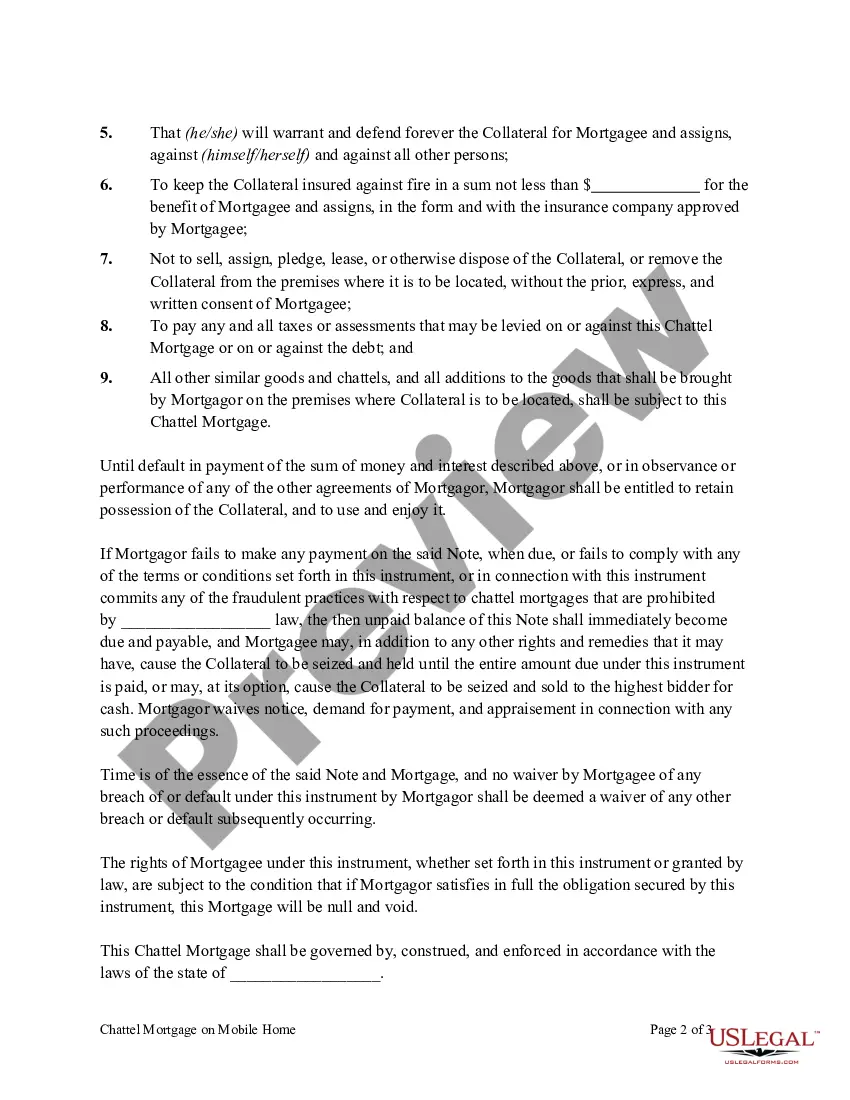
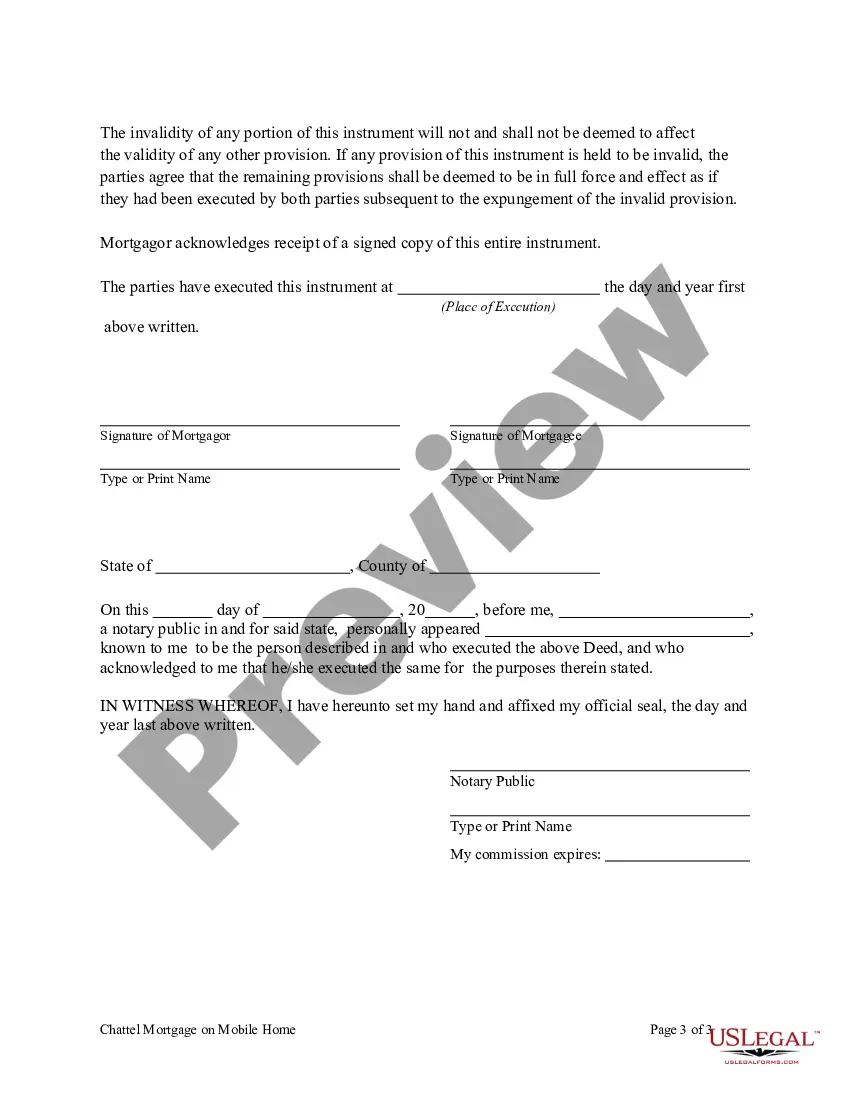
Chattel Mortgage Form With Extra Judicial Foreclosure In Los Angeles
Description
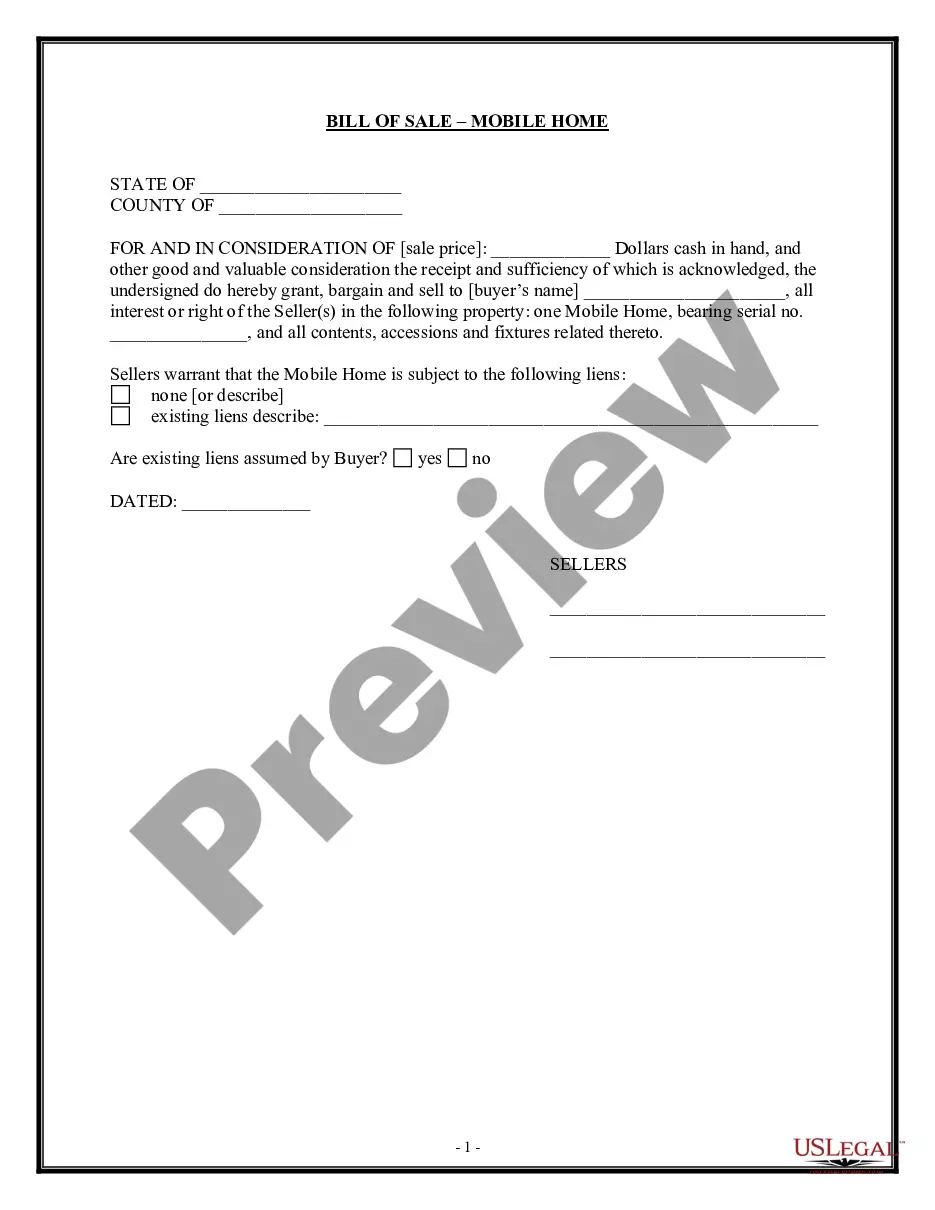
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?


Form popularity
FAQ
In California, lenders can foreclose on deeds of trust or mortgages using a nonjudicial foreclosure process (outside of court) or a judicial foreclosure process (through the courts). The nonjudicial foreclosure process is used most commonly in our state.
In a judicial foreclosure, after the judge orders the sale of a home, it's usually auctioned off to the highest bidder. The homeowner has some time after the sale to buy the home back from the successful bidder (called the right of redemption). The amount of time depends on whether the sale satisfied the debt.
In California, lenders can foreclose on deeds of trust or mortgages using a nonjudicial foreclosure process (outside of court) or a judicial foreclosure process (through the courts). The nonjudicial foreclosure process is used most commonly in our state.
Notification: After the foreclosure sale, you will receive a notice from the trustee if surplus funds are available. The trustee must also file a report with the court. Filing a Claim: Submit a claim form to the trustee or the court, detailing your right to the surplus funds.
In California, you typically need to miss three consecutive mortgage payments (120 days past due) before foreclosure proceedings start. It's essential to address any missed payments quickly to avoid escalating into a foreclosure situation that could threaten your home.
States with the highest foreclosure rates were Nevada (one in every 2,741 housing units with a foreclosure filing); New Jersey (one in every 3,059 housing units); Florida (one in every 3,086 housing units); California (one in every 3,152 housing units); and South Carolina (one in every 3,272 housing units).
If they want to start foreclosure, they'll need to follow the steps and timeline below. Lender contacts you to do a foreclosure avoidance assessment. 30 days after contact, lender can record a Notice of Default. 90 days later, lender can record a Notice of Sale. 21 days later, the property can be sold. After the foreclosure.
Unlike some states that have a statutory redemption period after the foreclosure sale, California primarily offers a redemption period prior to the foreclosure sale. This period allows homeowners to “redeem” their property by paying off the total amount owed before the sale occurs.
It takes several months for a lender to foreclose on a California property. If everything goes ing to schedule, the process typically takes approximately 120 days — about four months — but the process can take as long as 200 or more days to conclude.
In California, lenders can foreclose either: Without going to court (non-judicial) By going to court (judicial)