Az Purchase Residential Home With Mortgage
Description
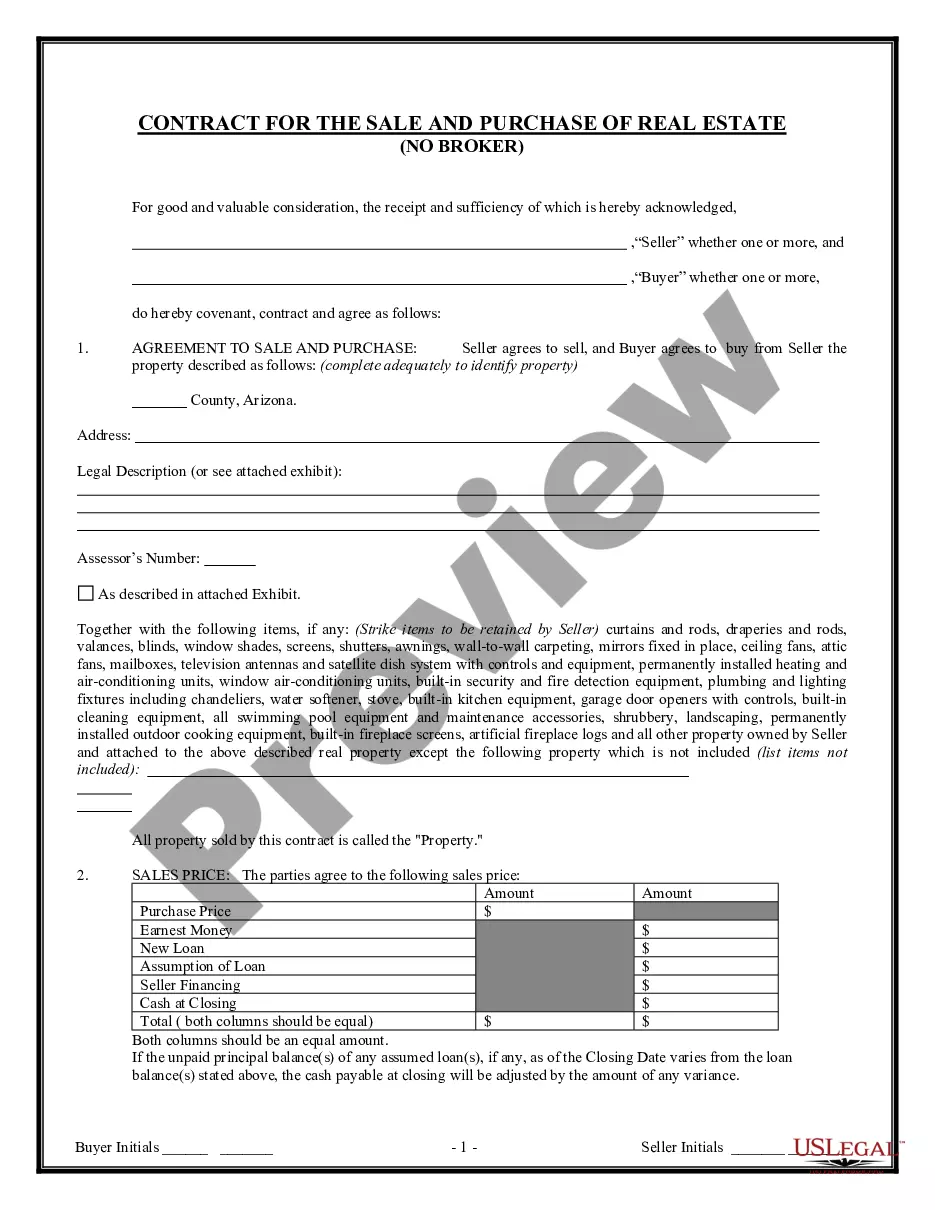
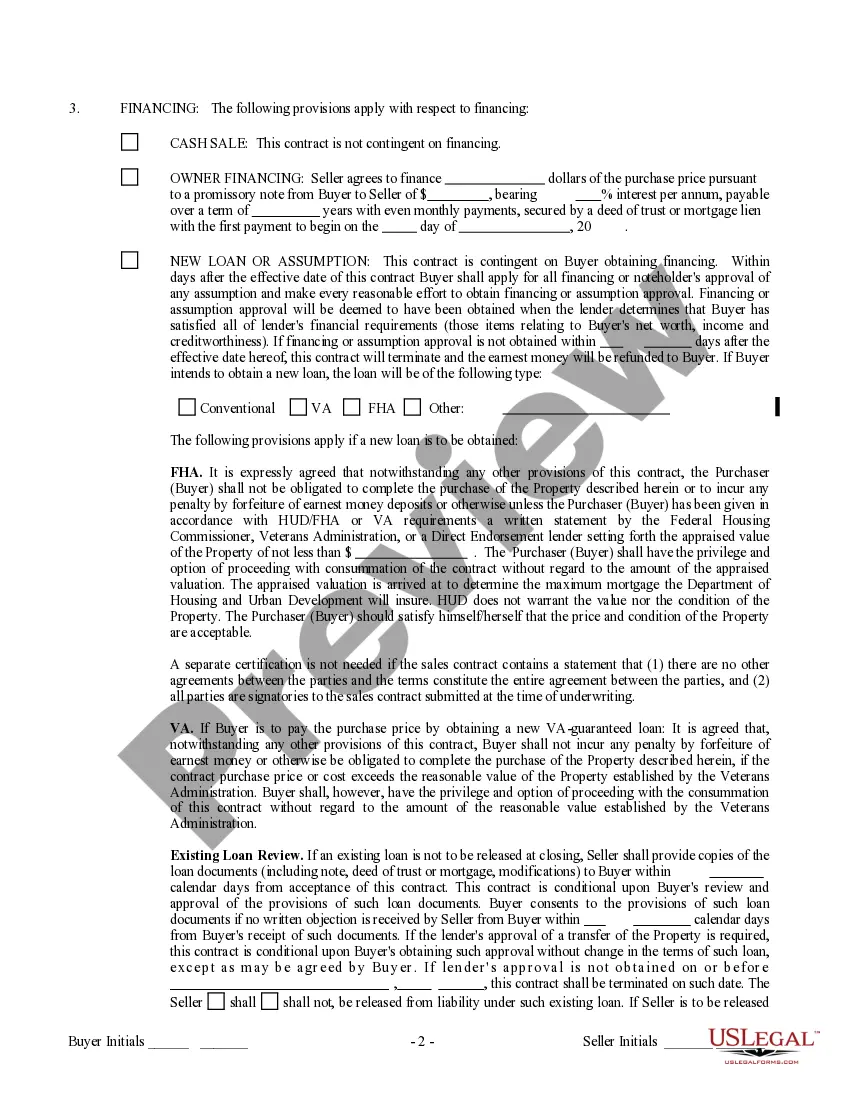
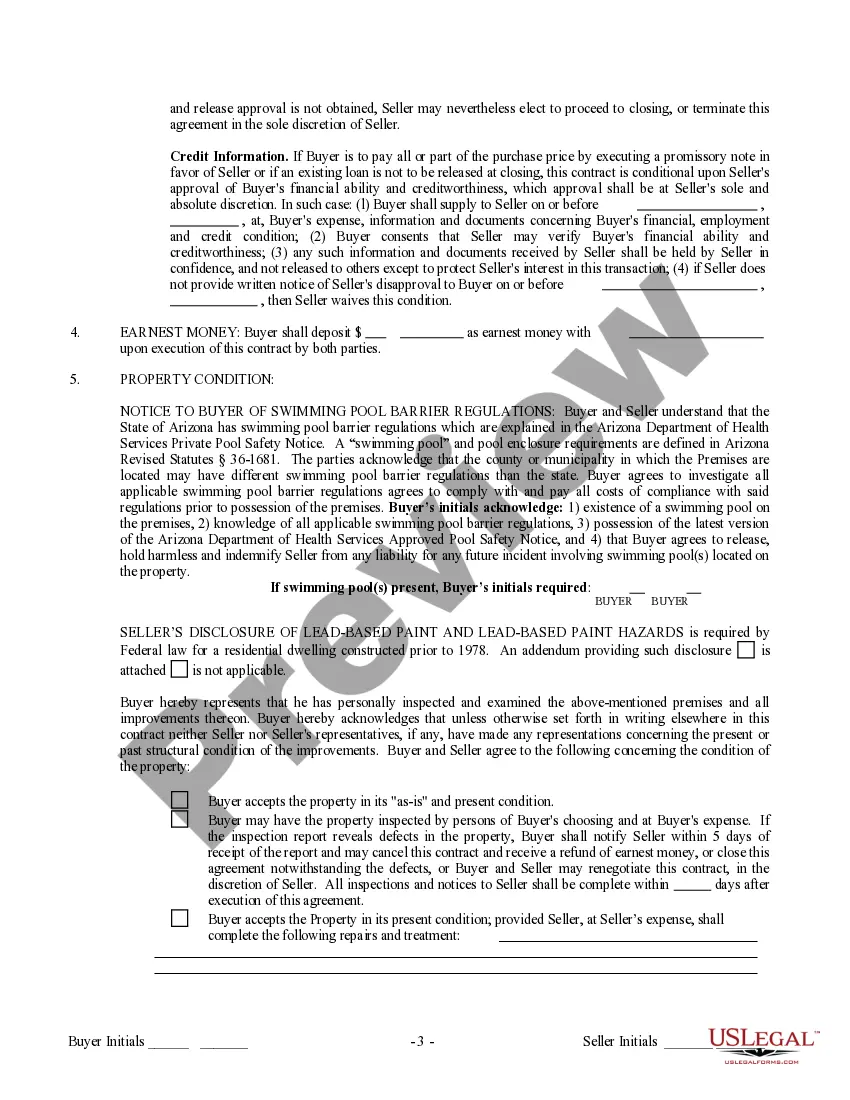
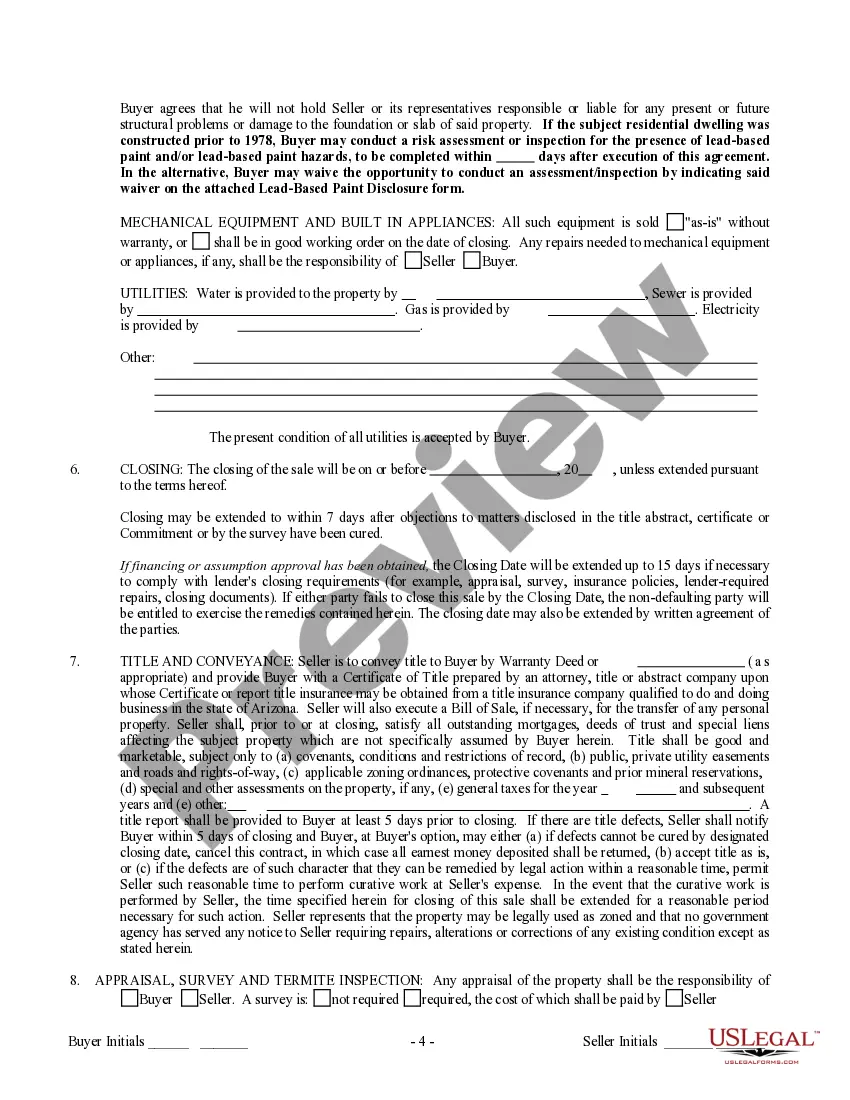
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Looking for another form?
How to fill out Arizona Contract For Sale And Purchase Of Real Estate With No Broker For Residential Home Sale Agreement?
Discovering a go-to resource for obtaining the most recent and suitable legal templates is part of the challenge involved with red tape. Securing the correct legal documents requires accuracy and meticulousness, which is why it is crucial to obtain samples of Az Purchase Residential Home With Mortgage exclusively from trustworthy sources, such as US Legal Forms. An incorrect template could squander your time and prolong the issue you are facing. With US Legal Forms, you can have minimal worries. You can access and examine all the information relating to the document’s application and appropriateness for your situation and location.
Follow the outlined steps to complete your Az Purchase Residential Home With Mortgage.
Eliminate the stress associated with your legal paperwork. Explore the extensive US Legal Forms library to source legal templates, verify their relevance to your situation, and download them immediately.
- Use the library navigation or search bar to find your template.
- Check the form’s description to ensure it meets the requirements of your state and locality.
- If available, view the form preview to confirm that the template is the one you are seeking.
- Return to the search and find the appropriate document if the Az Purchase Residential Home With Mortgage does not meet your needs.
- If you are certain about the form’s relevance, proceed to download it.
- If you are a registered user, click Log in to verify your identity and access your chosen forms in My documents.
- If you haven’t created an account yet, click Buy now to obtain the template.
- Select the payment plan that fits your requirements.
- Proceed to the registration to finalize your purchase.
- Complete your purchase by selecting a payment method (credit card or PayPal).
- Choose the document format for downloading Az Purchase Residential Home With Mortgage.
- Once you have the form on your device, you can edit it using the editor or print it and fill it out manually.
Form popularity
FAQ
To buy a residential home with a mortgage in Arizona, start by assessing your financial situation and determining your budget. Next, get pre-approved for a mortgage, which will help you understand how much you can borrow. Once you find a suitable home, make an offer and negotiate the terms. Finally, use a platform like USLegalForms to simplify the paperwork involved in securing your mortgage and completing the purchase.
Yes, you can buy a residential home in Arizona even if you currently have a mortgage. Many homeowners choose to purchase another property while maintaining their existing mortgage, especially if they are upgrading or investing. However, lenders will evaluate your debt-to-income ratio to ensure you can manage both mortgage payments. Consulting with a financial advisor or using resources from USLegalForms can help you navigate this process smoothly.
To comfortably afford a $400,000 residential home with a mortgage, your salary should ideally be around $80,000 to $100,000 annually. This estimate accounts for various factors, including the down payment, interest rates, and other debts. Lenders typically recommend that your housing costs should not exceed 28% of your gross monthly income. Therefore, it's crucial to assess your financial situation and consider your budget before making a purchase.
Arizona offers a $20,000 down payment assistance program to help eligible buyers with their home purchase. This assistance can significantly reduce the financial burden when buying a residential home with a mortgage. It's designed for first-time homebuyers or those who haven't owned a home in the last three years. You can find more information on this program through your local housing authority or platforms like USLegalForms to streamline the application process.
To purchase a residential home in Arizona with a mortgage, lenders typically look for a minimum credit score of around 620. However, some programs may allow for lower scores, especially for first-time homebuyers. A higher credit score can help you secure better mortgage rates, making it easier to afford your new home. Therefore, it's beneficial to check your credit score and work on improving it if necessary.
Yes, you can write your own purchase agreement for a house, but it is advisable to ensure it meets all legal requirements. Using a platform like uslegalforms can simplify this process by providing templates that follow state laws. A well-crafted agreement is vital for your Az purchase residential home with mortgage, as it protects your interests and clarifies the terms of the sale.
The stages of the home buying process include determining your budget, getting pre-approved for a mortgage, and searching for homes. Once you find a suitable property, you will make an offer and negotiate the terms. After that, you will conduct inspections, finalize the mortgage, and close the sale. Understanding these stages can help you smoothly navigate your Az purchase residential home with mortgage.
In Arkansas, the primary instrument for securing home loans is a deed of trust, rather than a mortgage. This deed provides the lender with a security interest in the property while also offering certain protections for the borrower. If you're looking to make an AZ purchase residential home with a mortgage, understanding the differences between these instruments can help you navigate the closing process effectively.
To successfully complete an AZ purchase residential home with a mortgage in Arizona, start by assessing your financial situation. Obtain a pre-approval from a lender, which showcases your readiness to buy. Next, research neighborhoods, create a wish list, and collaborate with a local real estate agent. Finally, be prepared to complete necessary paperwork, secure financing, and handle closing procedures.
The 20 30 3 rule provides a straightforward guideline for an AZ purchase residential home with a mortgage. According to this rule, aim for a 20% down payment, keep your monthly housing costs under 30% of your gross income, and ensure you do not buy a home that costs more than three times your annual income. Following this rule can help you maintain financial stability while pursuing homeownership.