Split-Dollar Insurance Agreement with Policy Owned Jointly by Employer and Employee
What this document covers
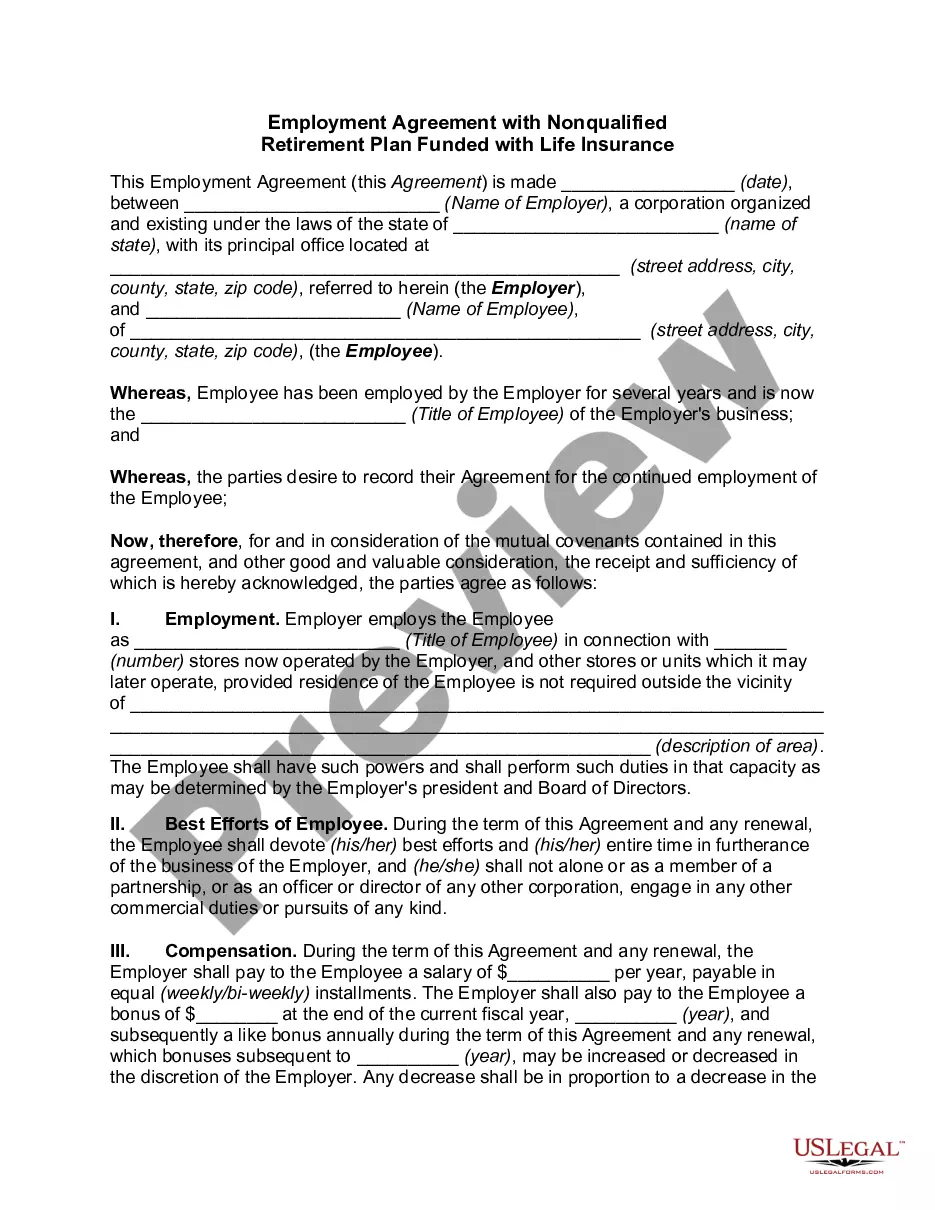
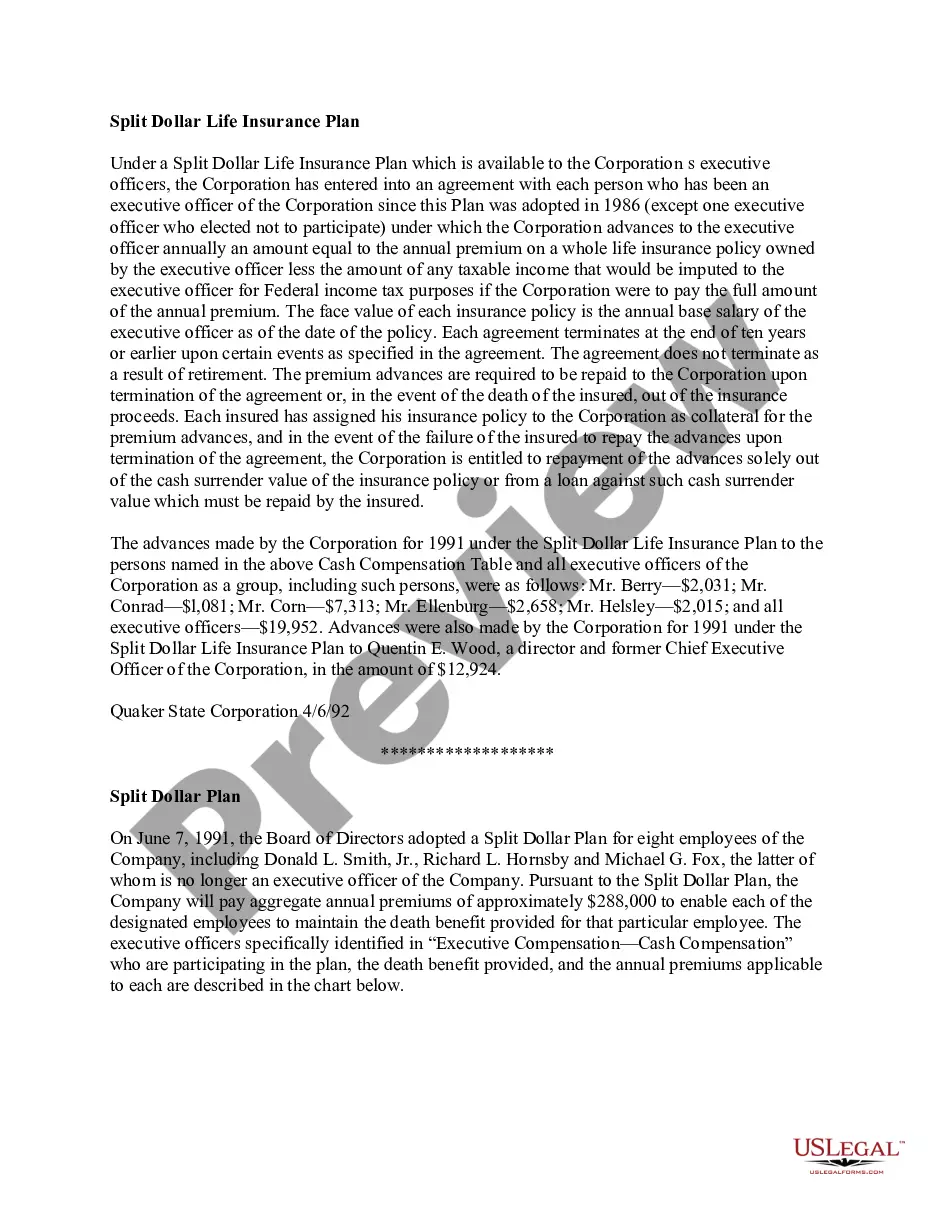
The Split-Dollar Insurance Agreement is a legal document that outlines the terms under which an employer and an employee jointly share the responsibilities and benefits of a permanent life insurance policy. This agreement details how the premium costs, cash values, and death benefits will be divided. It is particularly useful in providing supplemental benefits to key employees or executives, differentiating it from standard life insurance agreements by emphasizing the shared ownership and benefits structure.
What’s included in this form
- Date of agreement execution.
- Identification of the employer and employee.
- Terms outlining joint application for life insurance.
- Specifications for premium payments from both parties.
- Clauses addressing policy ownership and death benefits distribution.
- Termination clauses and conditions for cessation of benefits.
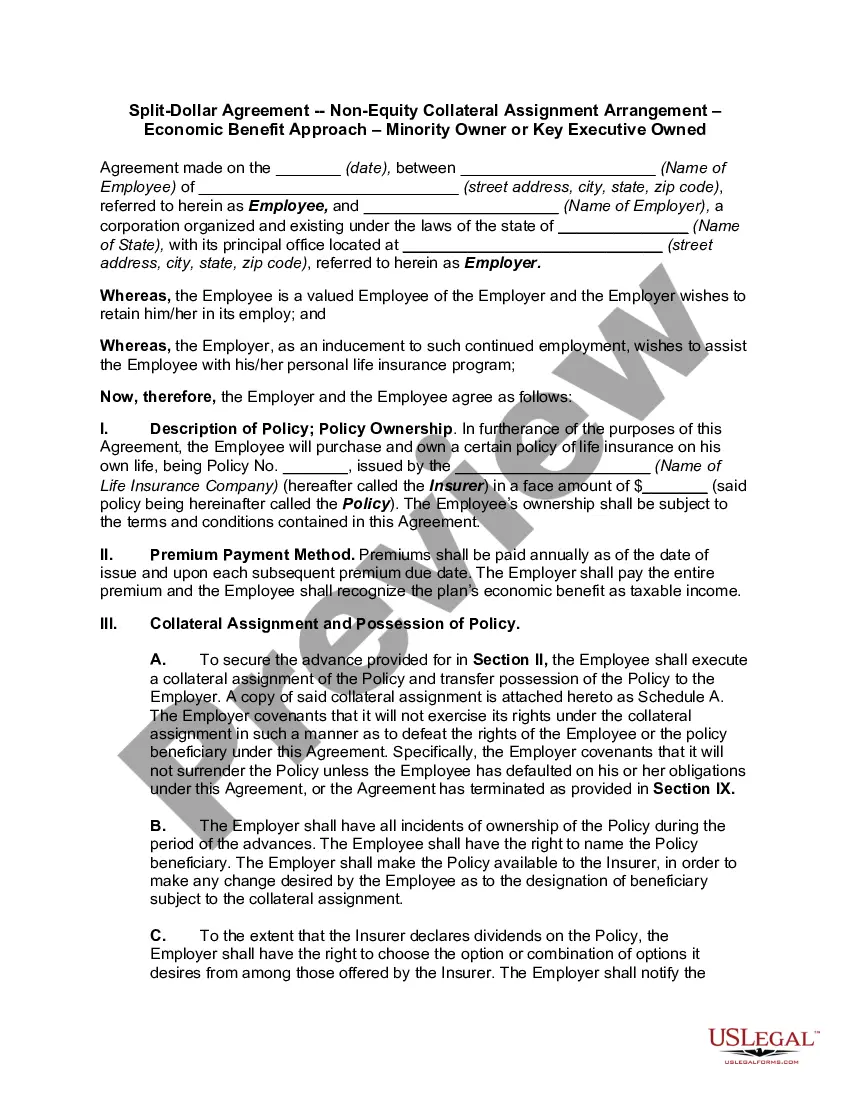
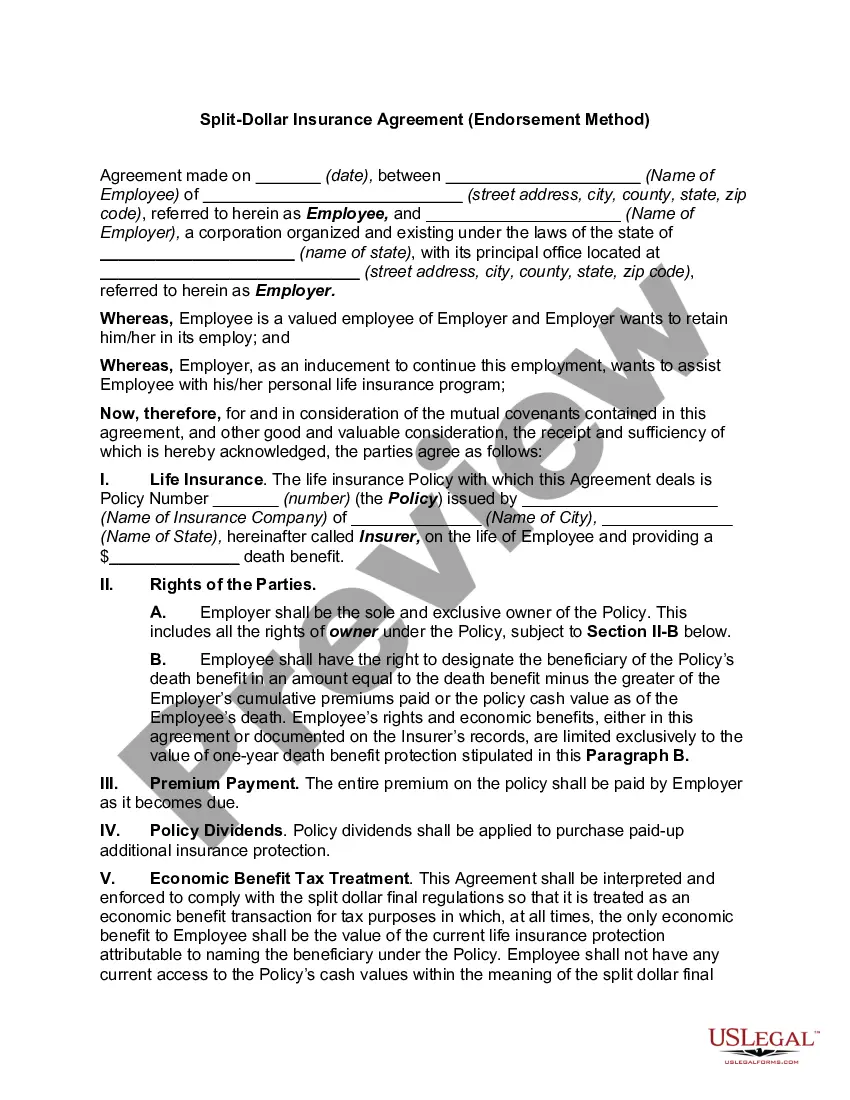
When to use this document
This form should be utilized when an employer wishes to establish a split-dollar insurance plan with an employee. It is particularly applicable in circumstances where an organization aims to enhance employee retention, provide supplemental benefits, or ensure the financial security of key employeesâ families. This framework becomes crucial when negotiating roles, responsibilities, and benefits related to life insurance ownership within a workplace context.
Who can use this document
- Employers looking to provide supplemental benefits to key employees or executives.
- Employees who wish to participate in a split-dollar life insurance arrangement.
- Human resources professionals and legal advisors overseeing employee benefits agreements.
How to prepare this document
- Enter the date of the agreement at the top of the document.
- Fill in the names and addresses of both the employer and the employee.
- Specify the employee's title and the name of the insurance company involved.
- Detail the amounts for the policy and the premium distribution agreement.
- Include conditions for termination and how benefits will be handled if employment ends.
Does this form need to be notarized?
This form does not typically require notarization unless specified by local law. However, it's wise to check state requirements to ensure compliance.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Typical mistakes to avoid
- Failing to clearly define the roles of the employer and employee in the agreement.
- Not specifying the insurance policy details accurately.
- Overlooking the terms related to performance metrics and their implications on the agreement.
- Neglecting to include the governing law clause relevant to the respective state.
Benefits of using this form online
- Easy access to downloadable templates drafted by licensed attorneys.
- Ability to customize the form to fit specific needs and scenarios.
- Convenient and secure storage of completed agreements for future reference.
- Efficiency in completing legal documents without needing in-person consultations.
Legal use & context
- The agreement establishes a clear legal framework for the joint insurance arrangement.
- It requires adherence to particular terms regarding premium sharing and death benefits.
- Compliance with state regulations is crucial to enforceability.
Key takeaways
- The Split-Dollar Insurance Agreement outlines the terms between employers and employees for a shared life insurance policy.
- It is a strategic tool for enhancing employee benefits and retention.
- Clear documentation of roles and responsibilities helps avoid disputes.
Looking for another form?
Form popularity
FAQ
The endorsement split dollar plan is one that is owned by the employer. The premiums are paid by the employer and the beneficiary is listed as the employee.
Dividing your life insurance proceeds through per stirpes basically means that the payout is to be split by the branch of your family. In other words; if you have 2 children, each is entitled to 50/50% of the proceeds provided he or she is alive.
Disadvantages of split dollar life insurance plans Your business will generally receive no tax deduction for its share of premium payments under the split dollar plan. Depending on how the agreement is structured, employees may have to pay income taxes each year on the value of the economic benefits provided to them.
Under a collateral assignment split dollar arrangement, the business loans a key employee money to pay the premium on a life insurance policy.He or she owns the policy and has the ability to name the beneficiary, and is taxed on the interest-free element of the loan.
There's no rule issued by life insurance companies that disallows you from owning multiple life insurance policies. And there are some scenarios where it may make sense to do so. For instance, you may have purchased a $250,000 term life policy at age 30, only to decide at age 40 that you need more coverage.
In a split-dollar plan, an employer and employee execute a written agreement that outlines how they will share the premium cost, cash value, and death benefit of a permanent life insurance policy.Generally, the owner of the policy, with some exceptions, is also the owner for tax purposes.
Split-dollar is a strategy that allows the sharing of the cost and benefit of a permanent life insurance policy. Any permanent life insurance policy that builds cash value can be used.
Funding a split dollar plan is a way to reward a key employee while accruing cash value in a whole life insurance policy that can serve as a ready source of funding for the employer. This funding can be used for a future buyout or even a deferred compensation plan.
Fortunately, there are no legal limits as to how many life insurance policies you can own.However, while many life insurance companies generally have very little concern over the number of policies you own, they may look more closely at the total amount of your benefits.