Retirement Plan Transfer Agreement regarding contribution plan meeting requirements of the Internal Revenue Service
What is this form?
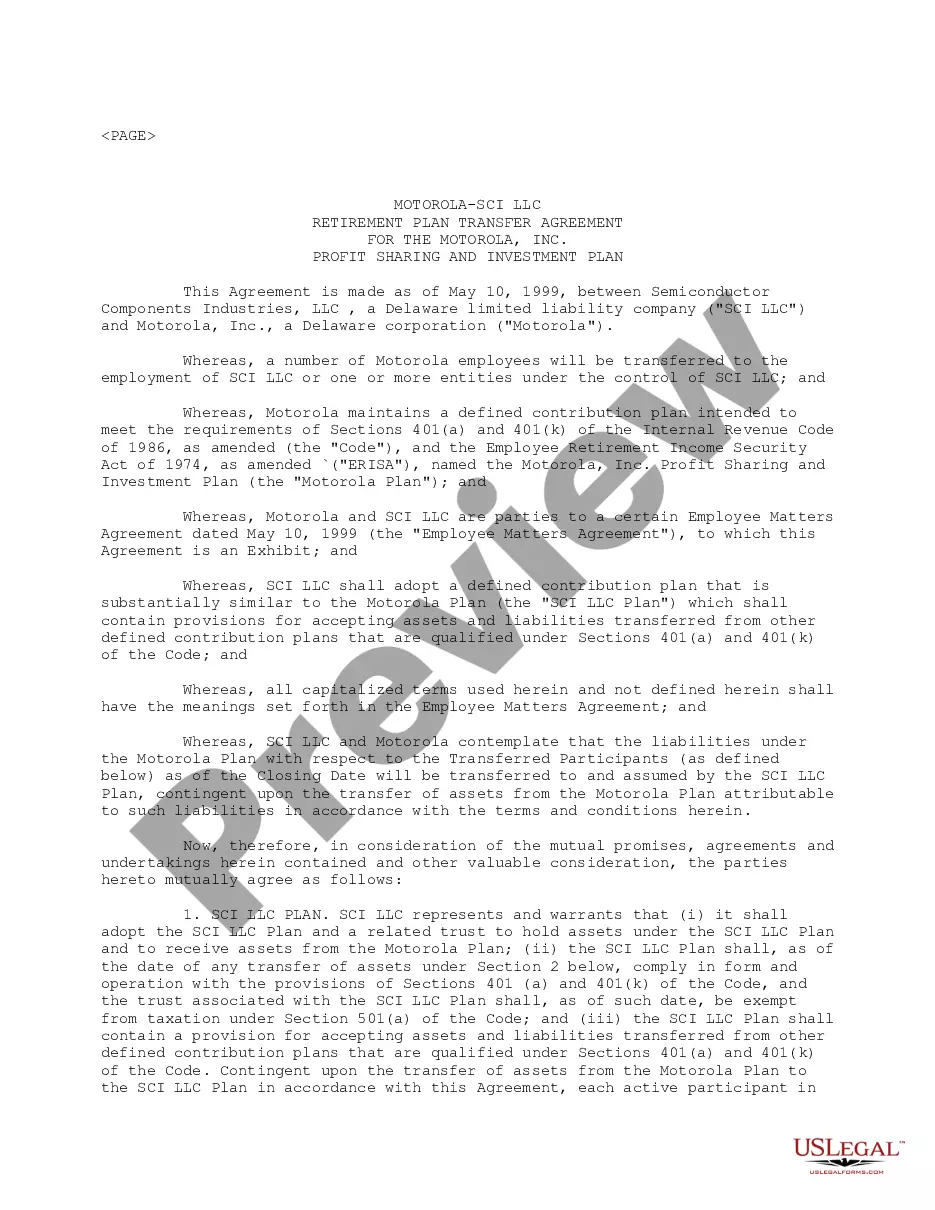
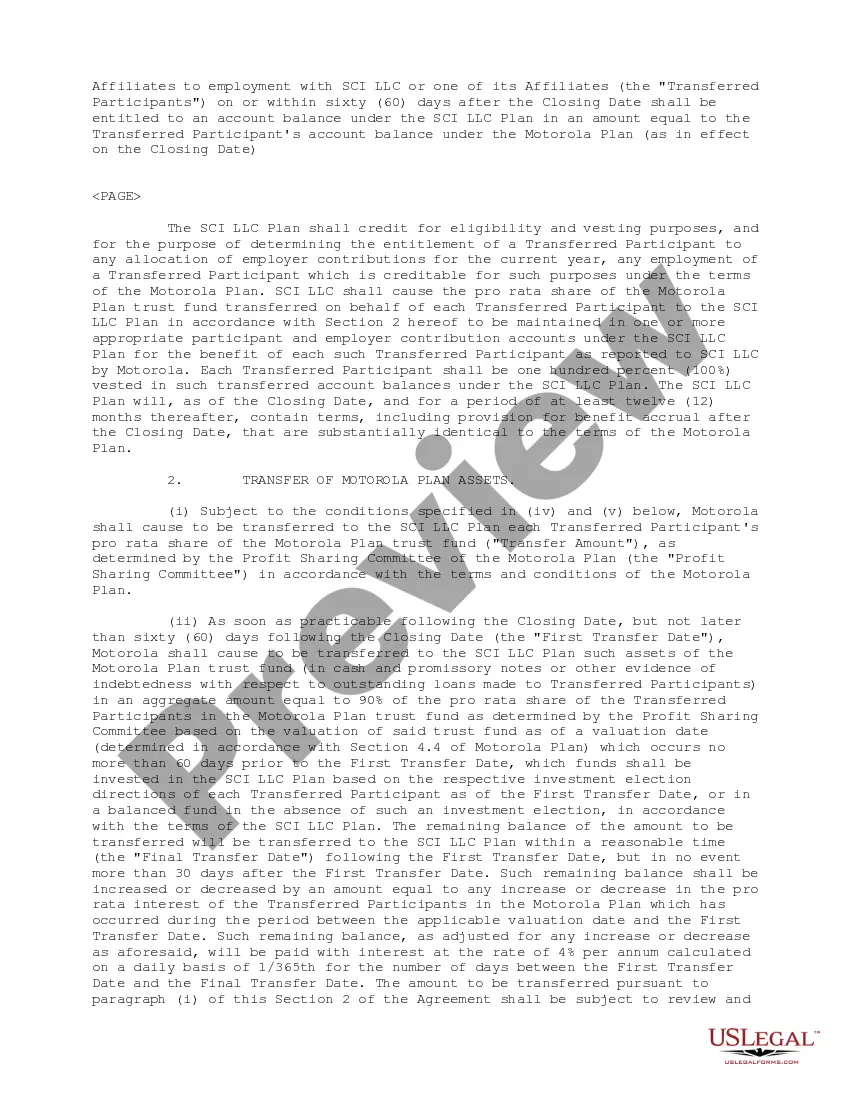
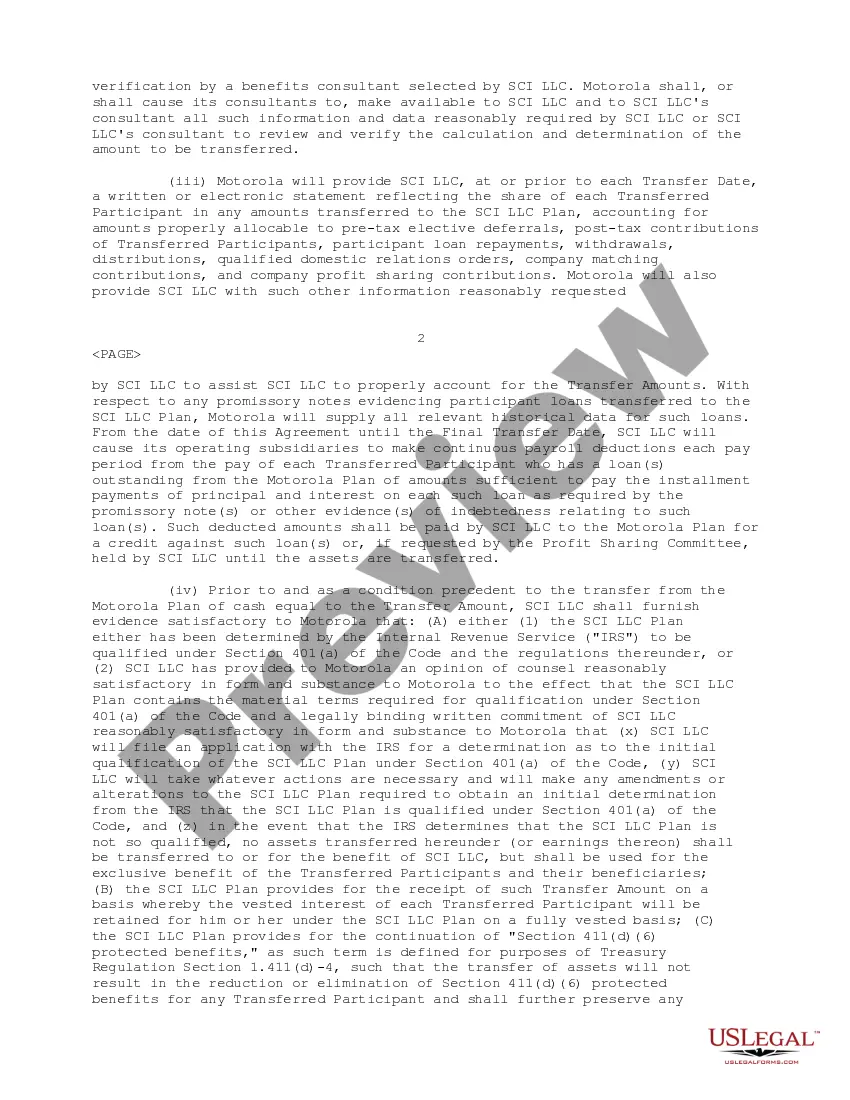
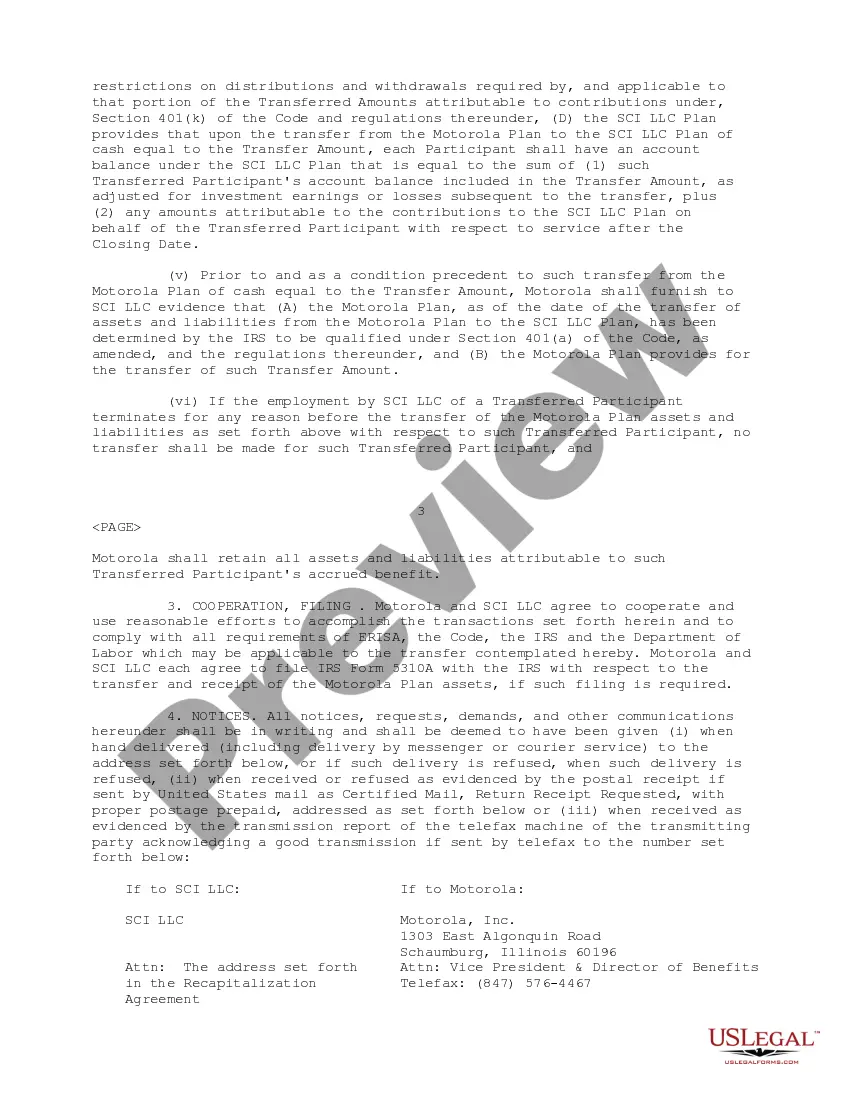
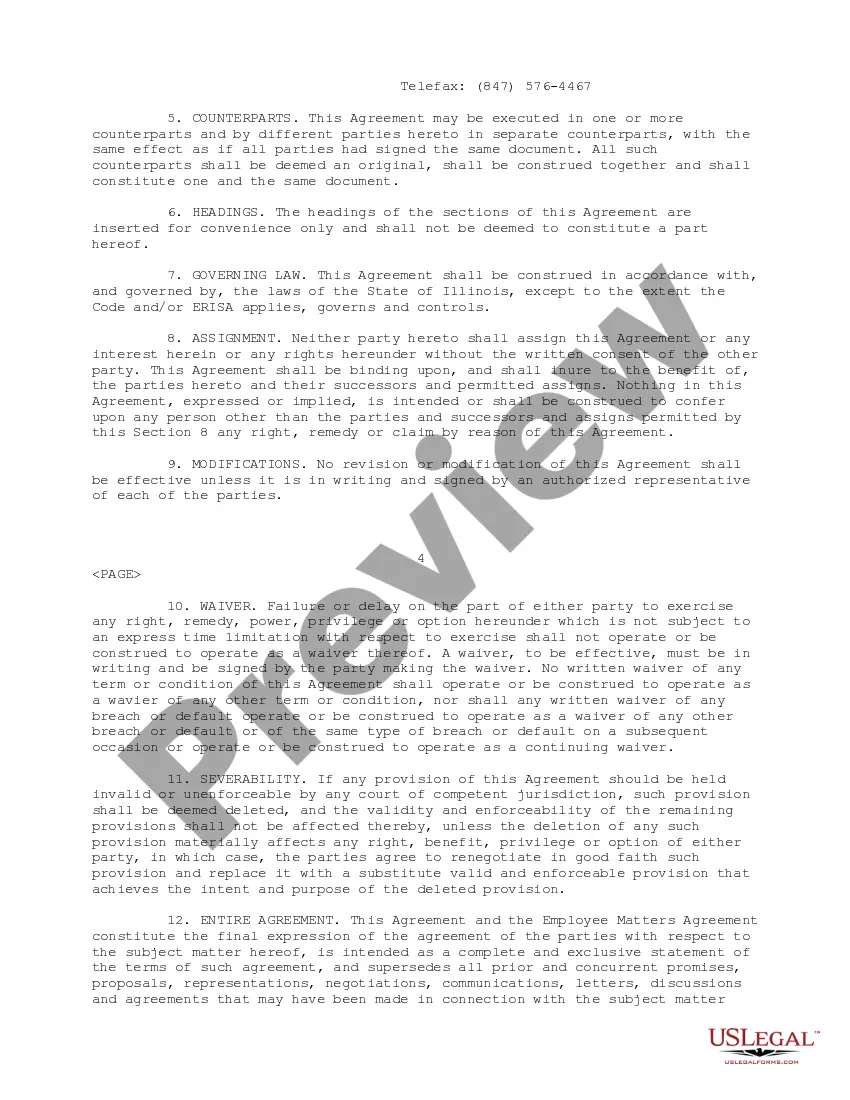
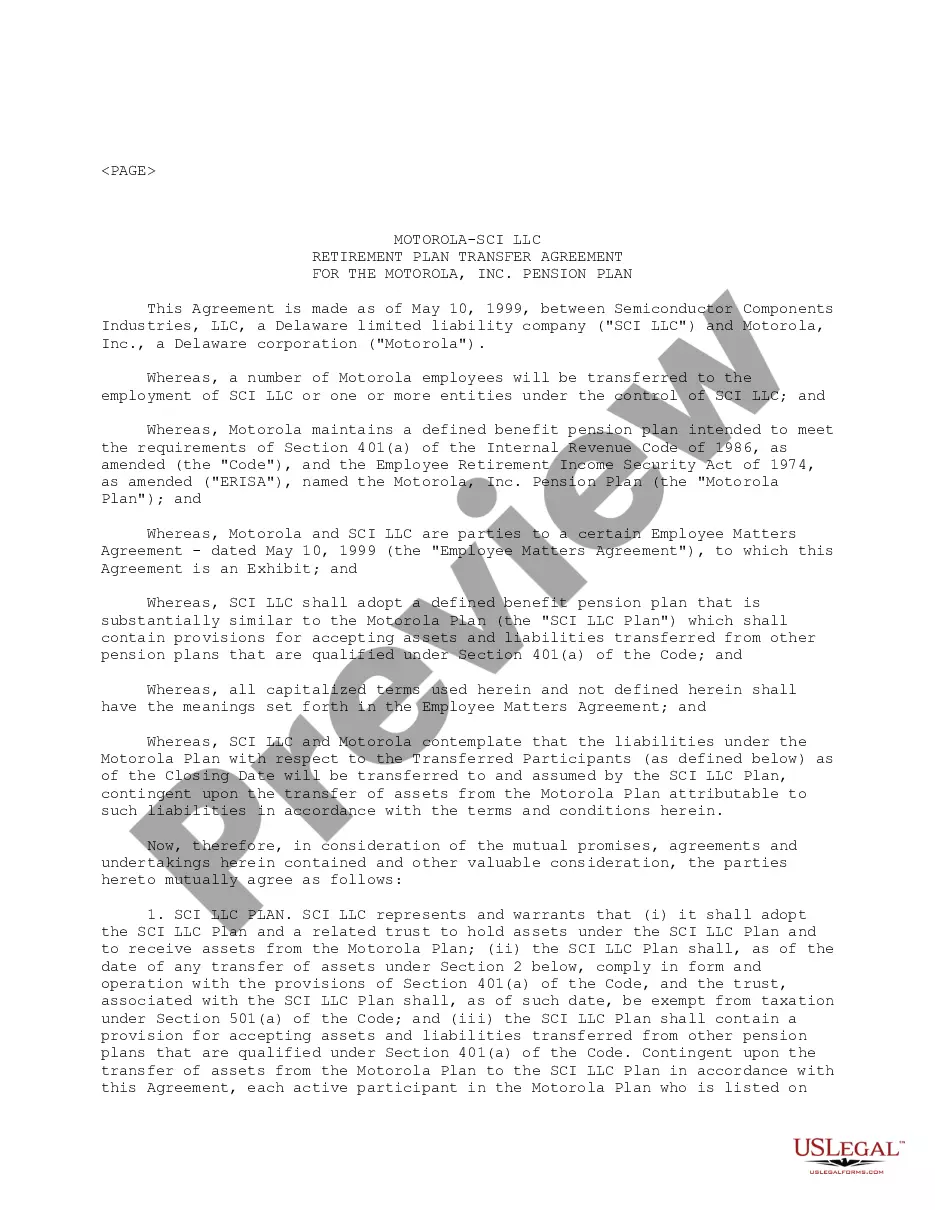
The Retirement Plan Transfer Agreement is a legal document facilitating the transfer of retirement assets from the Motorola, Inc. Profit Sharing and Investment Plan to the Semiconductor Components Industries, LLC (SCI LLC) Plan. This agreement is designed to meet the contribution plan requirements set forth by the Internal Revenue Service (IRS) and ensure the smooth transition of retirement benefits for participants who change employment from Motorola to SCI LLC.
Key components of this form
- Identification of parties involved: Semiconductor Components Industries, LLC and Motorola, Inc.
- Details regarding the Motorola Plan, including its compliance with IRS requirements.
- Procedures for transferring participants' account balances and liabilities from the Motorola Plan to the SCI LLC Plan.
- Conditions for maintaining vested interests of transferred participants in the SCI LLC Plan.
- Cooperation requirements related to IRS filings and compliance with ERISA regulations.
When to use this document
This form is used when employees of Motorola are transitioning to SCI LLC, allowing for the transfer of their retirement plan assets. If you are an employee affected by this transition, or involved in overseeing the retirement plans of these companies, using this agreement ensures the participants' benefits are handled properly and in compliance with federal regulations.
Intended users of this form
- Employees of Motorola who are being transferred to SCI LLC.
- HR representatives managing employee benefits during the transition.
- Legal advisors who assist in drafting or reviewing retirement plan agreements.
How to complete this form
- Identify the parties: Enter the legal names of Semiconductor Components Industries, LLC and Motorola, Inc.
- Specify the transition date: Include the effective date of the agreement.
- List the participants: Provide the details of all affected participants transferring from Motorola to SCI LLC.
- Define the transfer amount: Detail the amounts being transferred for each participant based on their current account balances.
- Obtain signatures: Ensure that authorized representatives from both parties sign the agreement to validate it legally.
Notarization guidance
This form does not typically require notarization unless specified by local law. Always confirm the requirements in your jurisdiction before finalizing the agreement.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Typical mistakes to avoid
- Failing to include all necessary participant information.
- Not ensuring the agreement complies with IRS and ERISA requirements.
- Omitting signatures or dates from authorized individuals.
Benefits of completing this form online
- Convenience of downloading and filling out the form digitally.
- Editability allows for quick adjustments as needed.
- Reliable source with templates drafted by licensed attorneys for accuracy.
- The agreement must comply with IRS regulations to be valid and enforceable.
- Both parties must ensure that they fully understand their rights and obligations before executing the agreement.
- Failure to accurately execute the agreement could lead to loss of retirement benefits for the Transferred Participants.
Summary of main points
- The Retirement Plan Transfer Agreement ensures a smooth transition of retirement benefits for employees moving from Motorola to SCI LLC.
- It includes critical compliance with IRS regulations and guarantees that employees remain fully vested in their benefits.
- Using a standardized form simplifies the process and reduces the risk of errors during the transfer.
Looking for another form?
Form popularity
FAQ
Understanding workplace retirement plans A defined contribution plan is a common workplace retirement plan in which an employee contributes money and the employer typically makes a matching contribution.In a defined contribution plan, both you and your employer can contribute to your individual account.
A qualified plan is simply one that is described in Section 401(a) of the Tax Code. The most common types of qualified plans are profit sharing plans (including 401(k) plans), defined benefit plans, and money purchase pension plans. In general, your contributions are not taxed until you withdraw money from the plan.
Nondiscrimination in coverage, contributions, and benefits. Minimum age and service requirements. Minimum vesting standard. Limits on contributions and benefits. Top-heavy plan requirements.
And investors in those plans often earn lower returns than they expected. A defined benefit plan delivers retirement income with no effort on your part, other than showing up for work. And that payment lasts throughout retirement, which makes budgeting for retirement a whole lot easier.
Qualified plans have tax-deferred contributions from the employee, and employers may deduct amounts they contribute to the plan. Nonqualified plans use after-tax dollars to fund them, and in most cases employers cannot claim their contributions as a tax deduction.
Qualification rules include: Nondiscrimination in coverage, contributions, and benefits. Minimum age and service requirements. Minimum vesting standard. Limits on contributions and benefits.
Qualified retirement plans are grouped into two primary categories: defined benefit plans and defined contribution plans.
401(k). Solo 401(k). 403(b). 457(b). IRA. Roth IRA. Self-directed IRA. SIMPLE IRA.
What type of retirement plan is not required to have a vesting schedule, is not approved by the IRS, can discriminate in favor of highly compensated employees, and can benefit the employer? -free.