Loan Agreement for Employees
Overview of this form
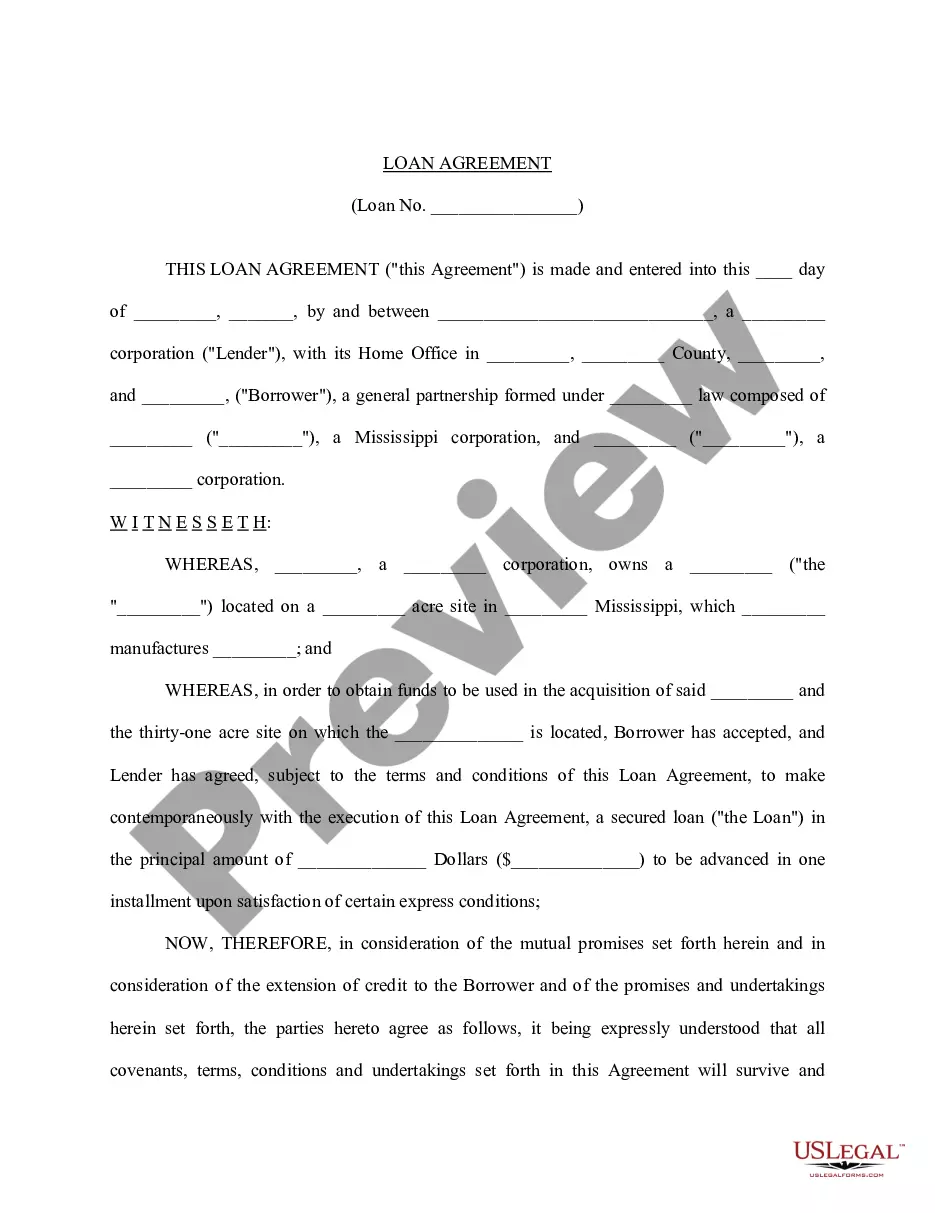
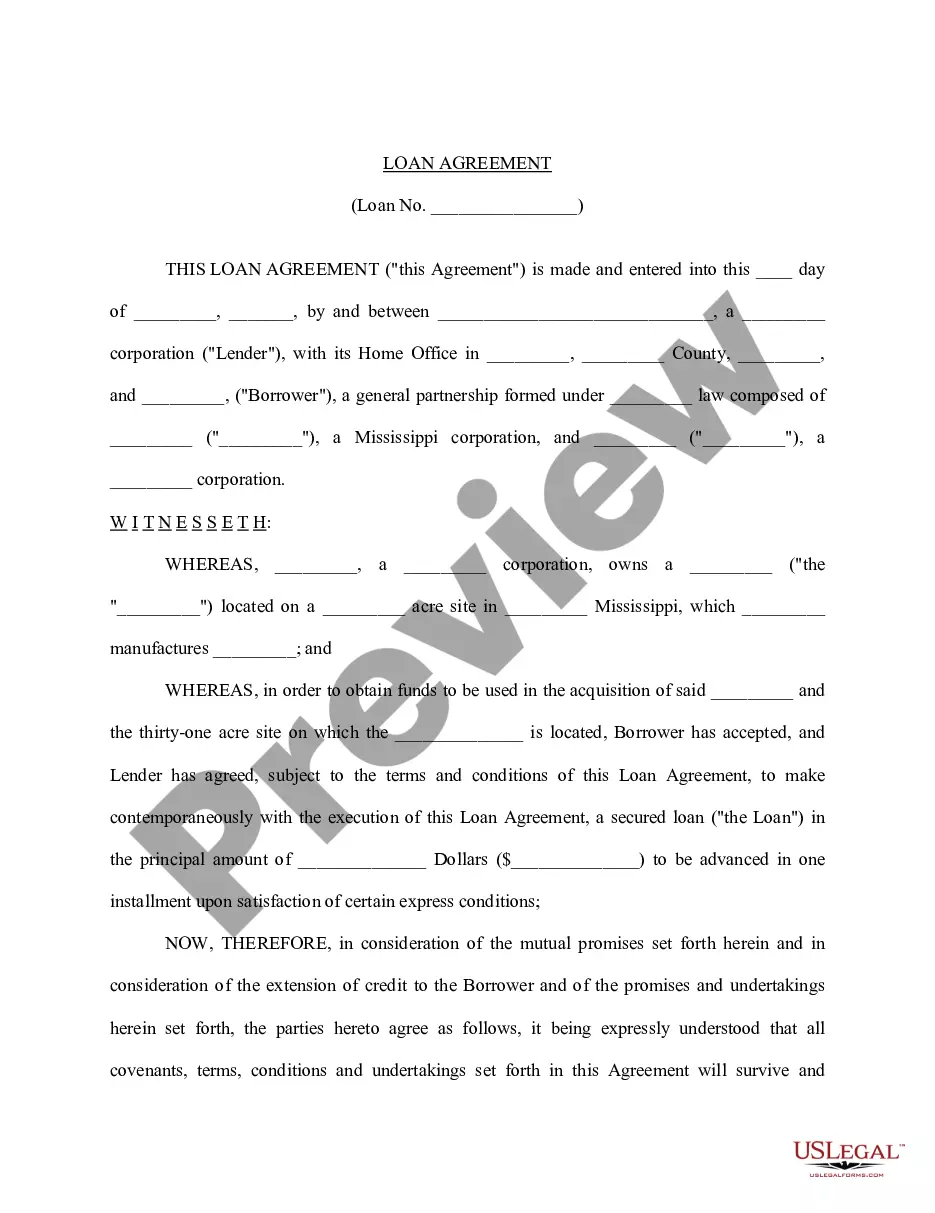
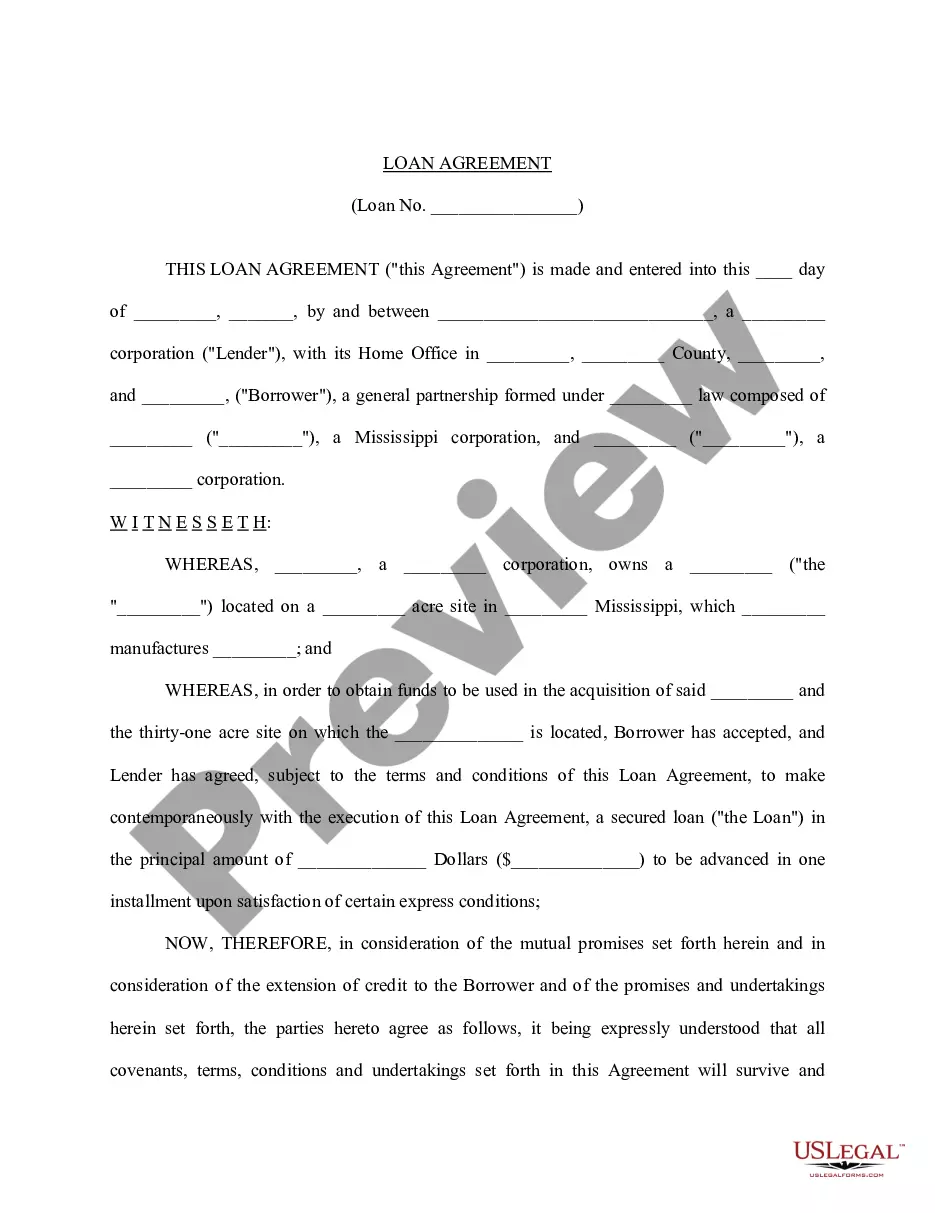
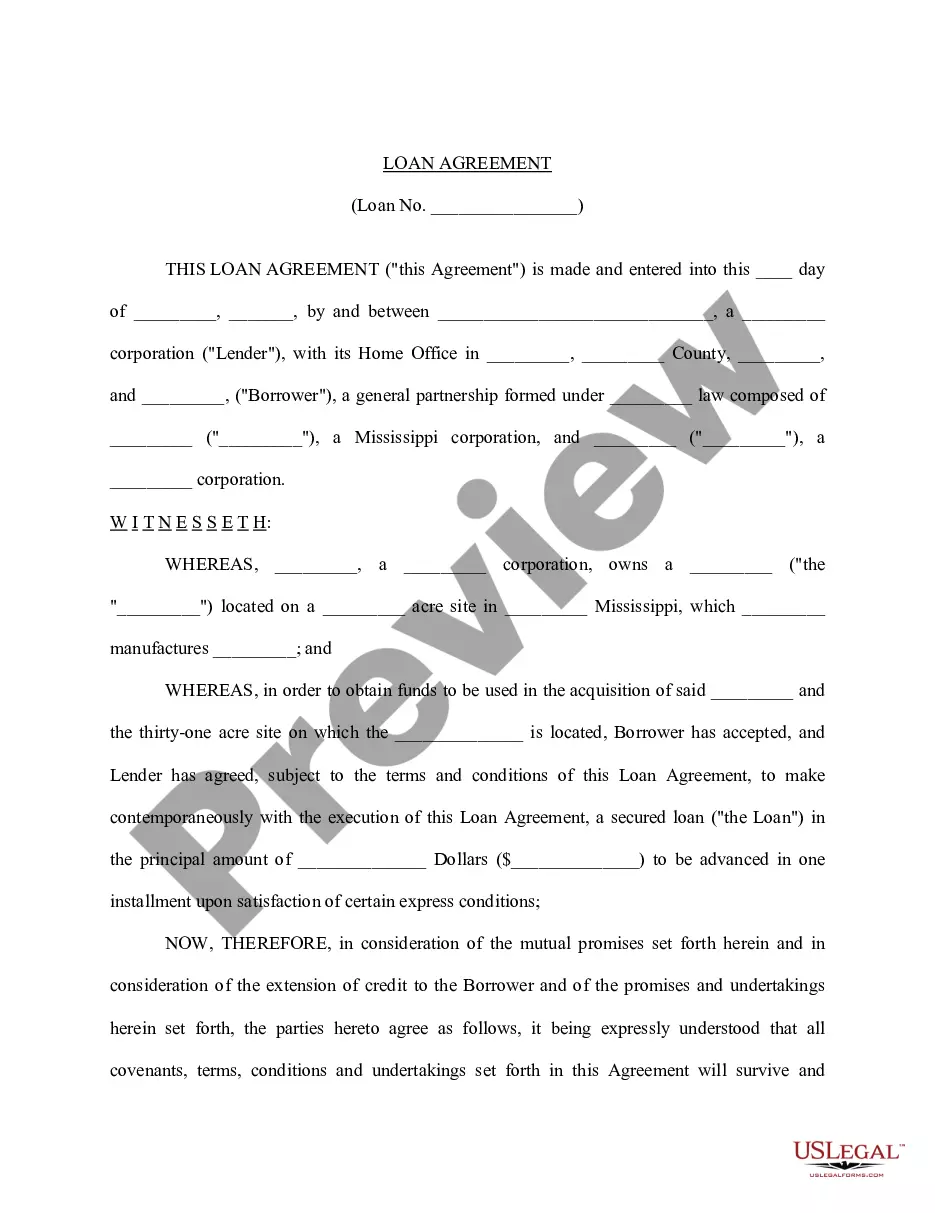
The Loan Agreement for Employees is a legal document that outlines the terms under which a lender extends a loan to an employee. This agreement establishes the roles, responsibilities, and liabilities of both parties involved in the loan process. Unlike other loan agreements, this specific template is tailored for employer-employee relationships, making it essential for ensuring clarity and mutual understanding in financial transactions between employers and their employees.
What’s included in this form
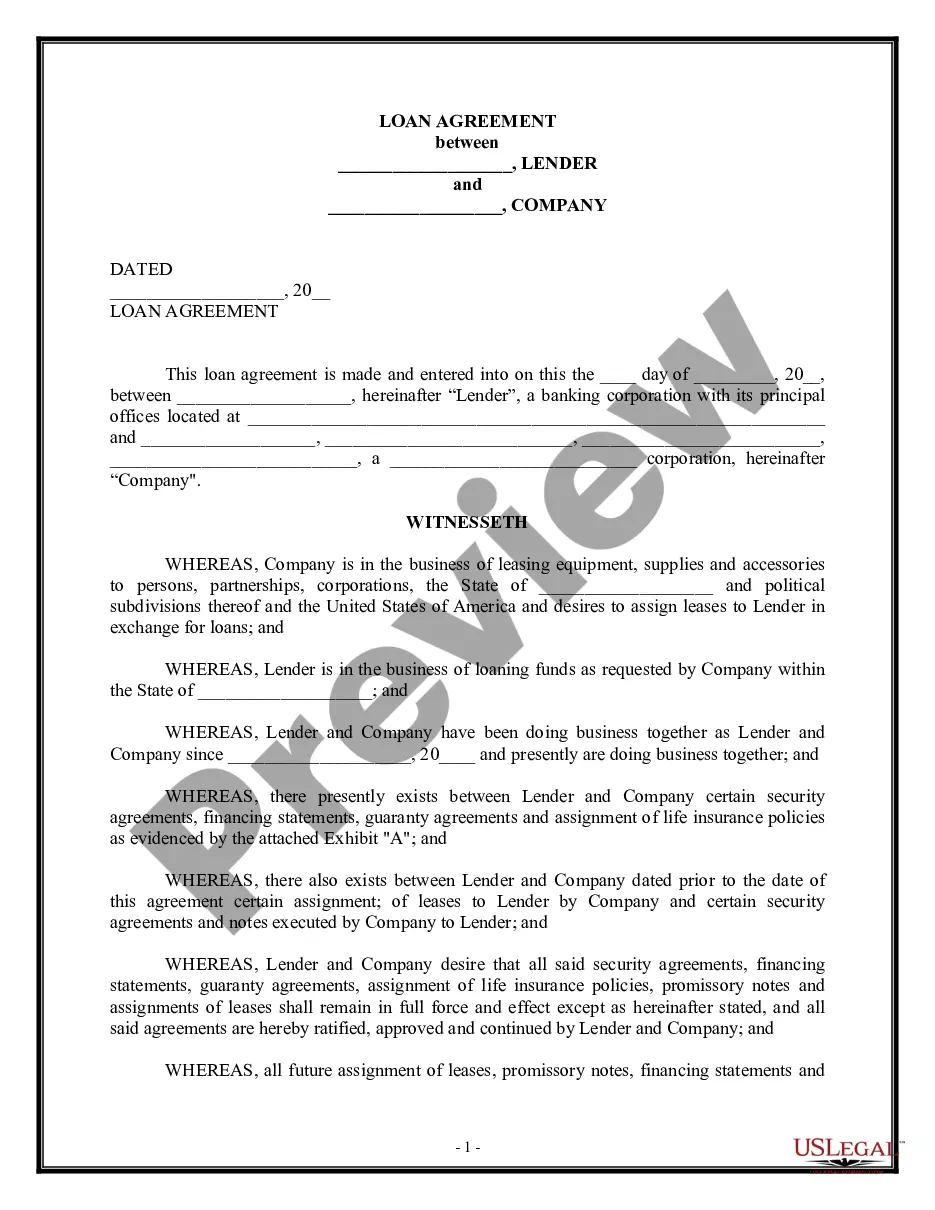
- Identification of the parties involved: lender and borrower details.
- Loan amount and terms, including interest rates and repayment schedule.
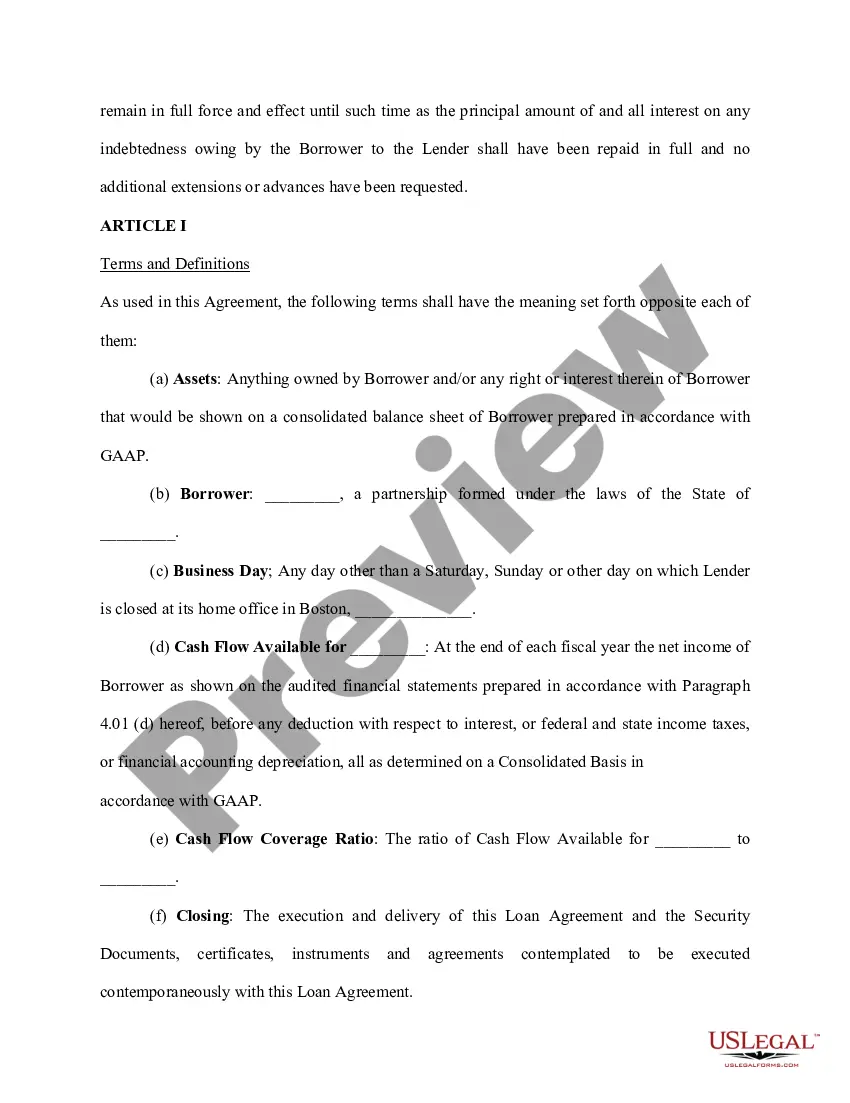
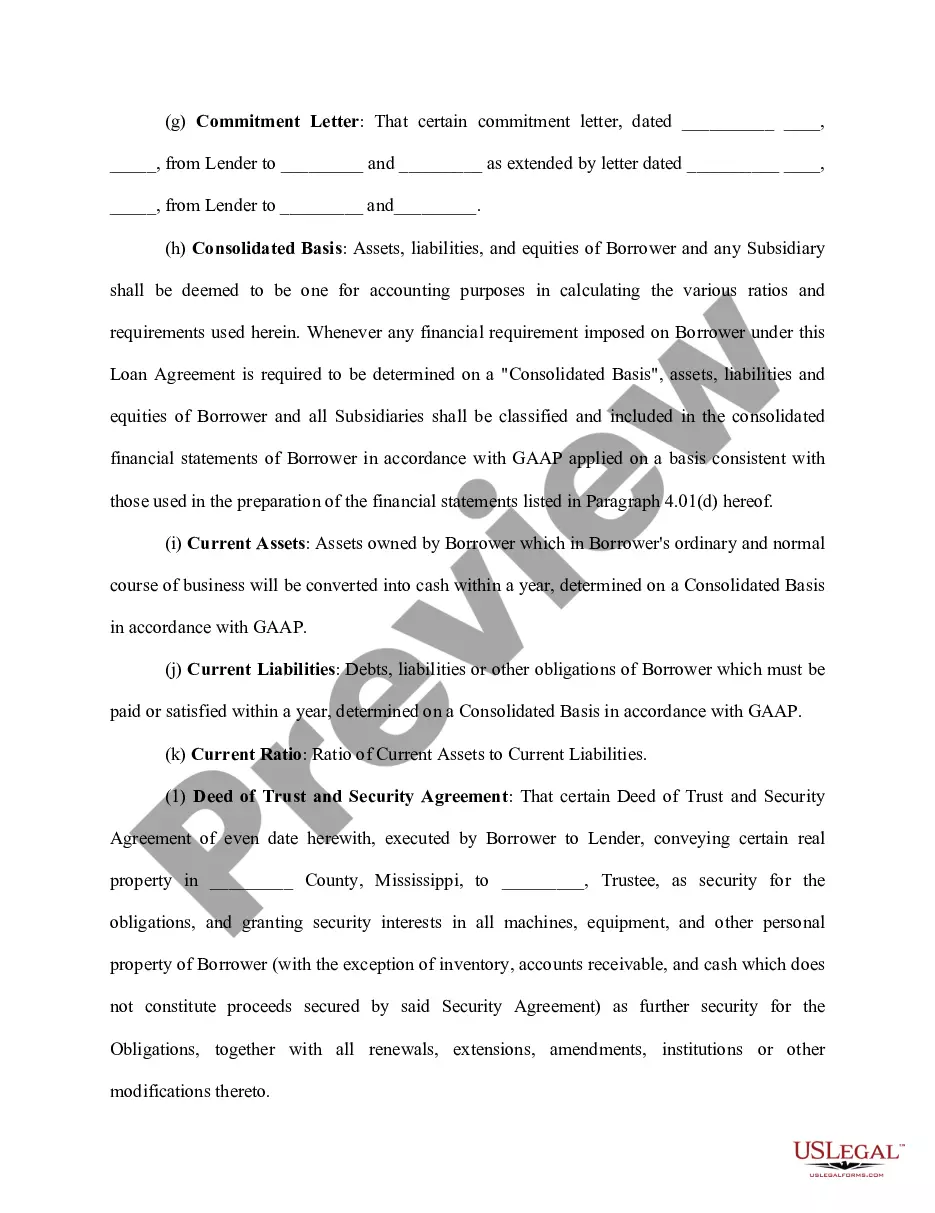
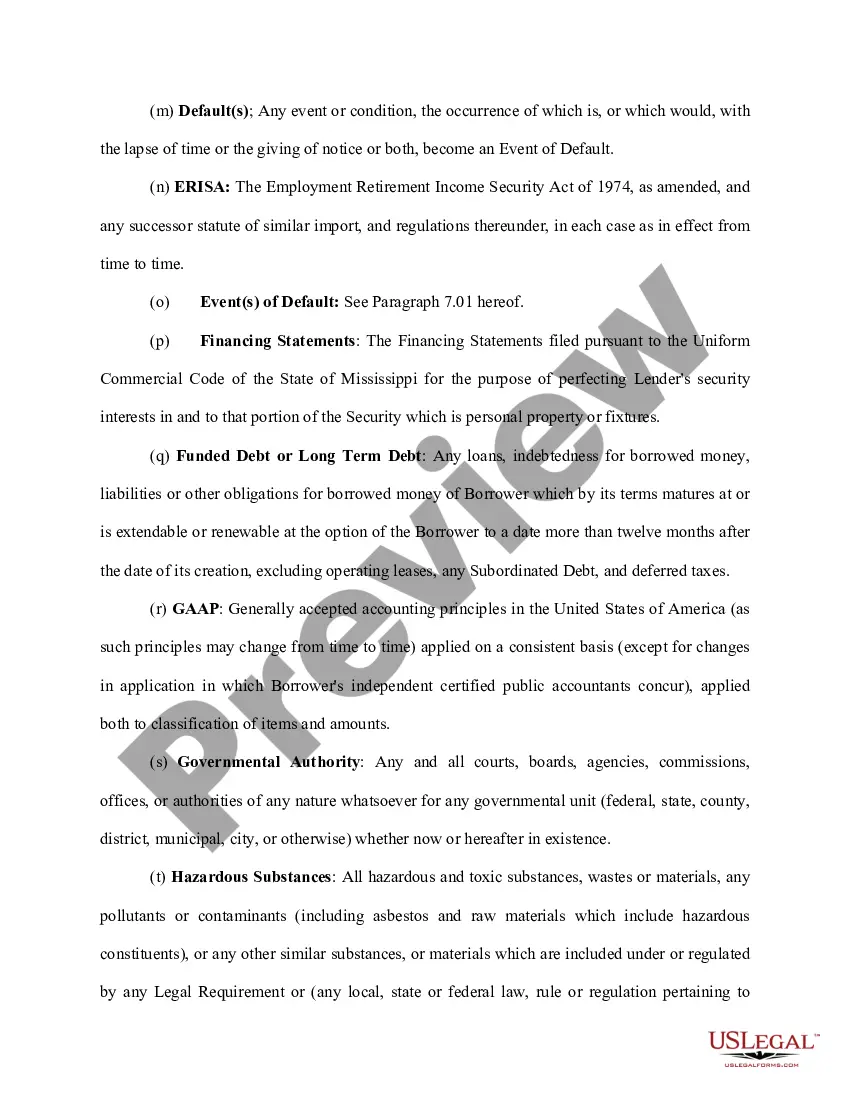
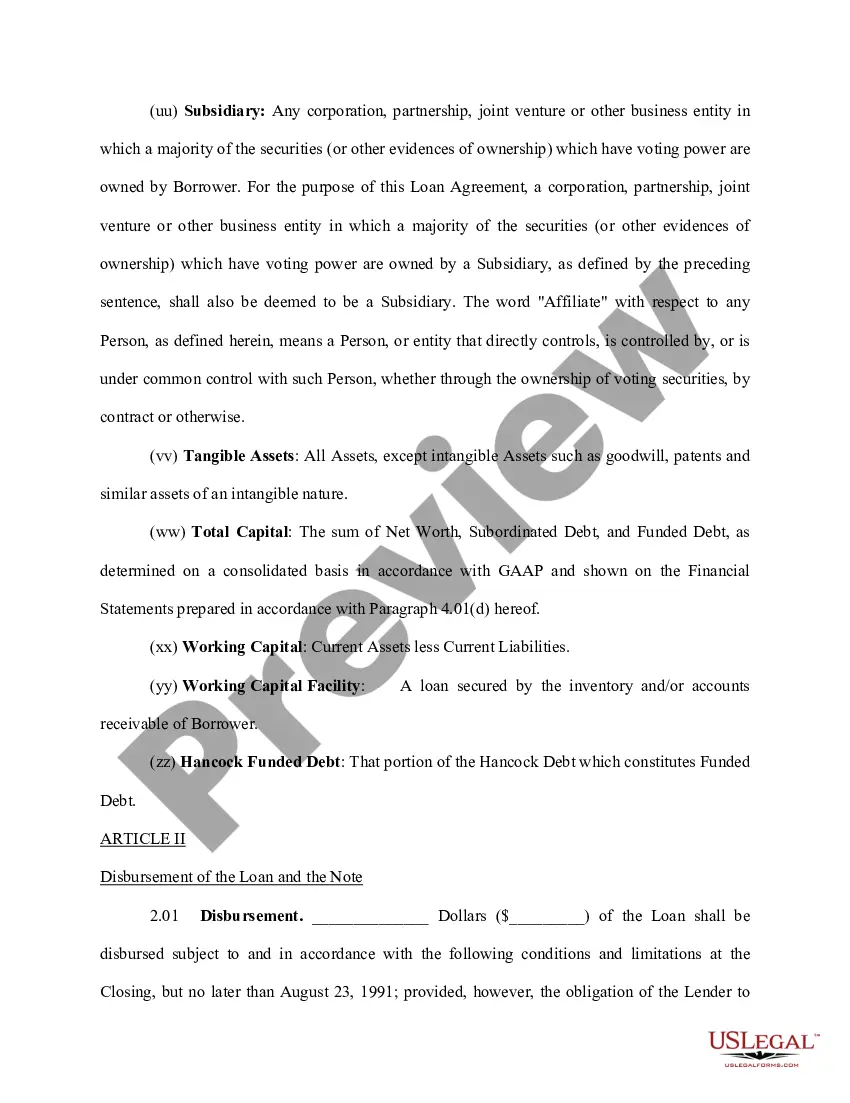
- Definitions of key terms to ensure clarity in obligations.
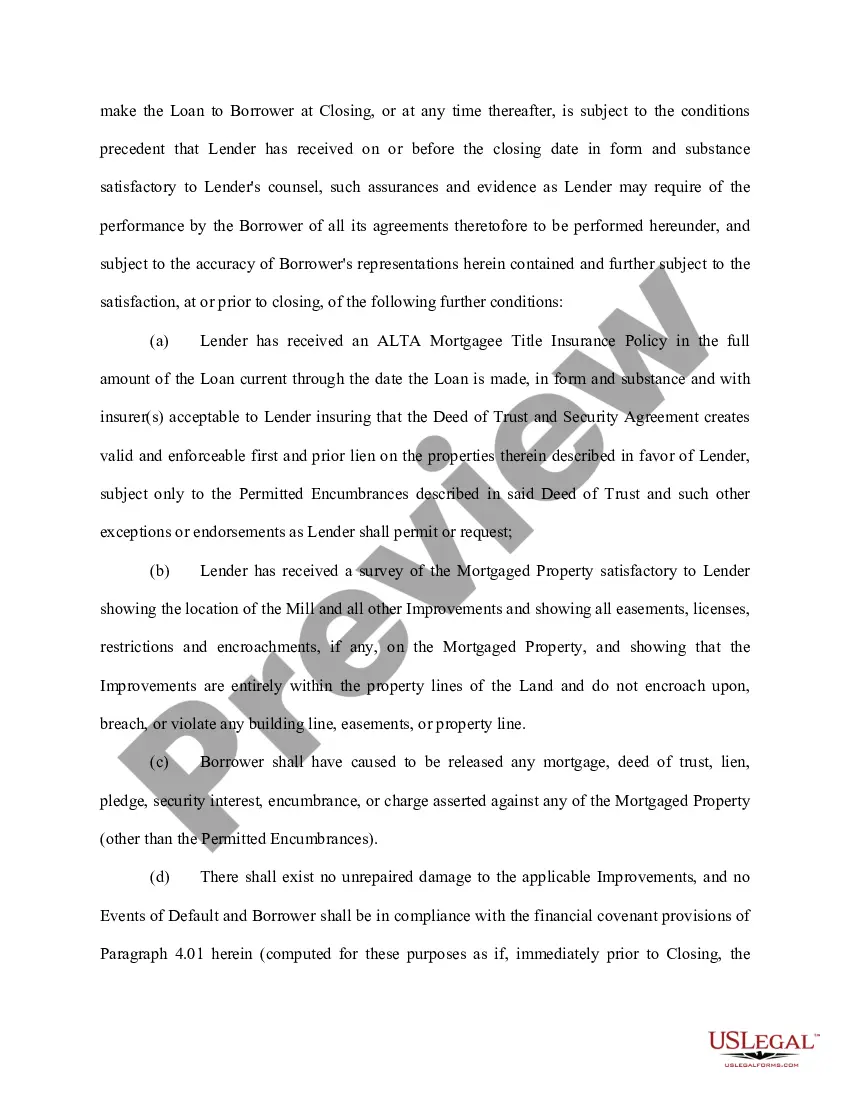
- Conditions for disbursement of loan funds.
- Warranties and representations by both parties.
- Default events and remedies provided for the lender.
Situations where this form applies
This form should be used whenever an employer intends to loan money to an employee. It is crucial in situations such as providing funds for personal expenses, supporting education costs, or facilitating home purchases. This agreement ensures both parties have a clear understanding of repayment expectations and protects their rights under the loan terms.
Who should use this form
- Employers looking to provide financial assistance to employees.
- Employees who are borrowing money from their employer.
- Human resources professionals managing loan processes.
- Legal professionals assisting in drafting or reviewing loan agreements.
How to prepare this document
- Identify the lender and borrower by stating their full names and addresses.
- Specify the loan amount being offered and the agreed-upon interest rate.
- Outline the repayment schedule, including due dates and payment methods.
- Include any conditions that must be met before funds are disbursed.
- Both parties should sign and date the agreement to make it legally binding.
Is notarization required?
This form does not typically require notarization unless specified by local law. However, having the document notarized can add an extra layer of security and validity to the agreement if desired.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.
Mistakes to watch out for
- Failing to clearly define the repayment terms.
- Not including all necessary parties in the agreement.
- Omitting essential details like interest rates or late fees.
- Not having both parties sign the document, making it unenforceable.
Why use this form online
- Convenience of immediate access and ability to edit as needed.
- Reliable templates drafted by licensed attorneys, ensuring compliance.
- Secure storage and sharing options to protect sensitive information.
- Easy to use even for individuals with limited legal experience.
This Loan Agreement is legally binding and enforceable as long as it follows applicable laws and regulations. Both parties need to clearly understand their obligations and the conditions under which the loan is granted.
Summary of main points
- The Loan Agreement for Employees outlines the terms of the loan and protects both partiesâ interests.
- It is vital to fill out the document accurately and obtain all necessary signatures.
- Employers must ensure compliance with local laws regarding employee loans.
Looking for another form?
Form popularity
FAQ
Identity of the Parties. The names of the lender and borrower need to be stated. Date of the Agreement. Interest Rate. Repayment Terms. Default provisions. Signatures. Choice of Law. Severability.
The most basic loan agreement is commonly called an "IOU." These are typically used between friends or relatives for small amounts of money, and simply state the dollar amount that is owed. They do not usually say when payment is due, nor include any interest provisions.
A loan to an employee is money advanced by the company to assist the employee. If the employee is expected to repay the loan within one year of the balance sheet date, the loan balance is a current asset of the company. Any amount not expected to be collected within one year is a noncurrent or long term asset.
State laws for employee loansEmployers in the U.S. can provide loans to their employees, but may have to comply with different laws depending on your state. Some states allow employees to repay loans through payroll deductions, but only if it doesn't reduce their wages below the $7.25-per-hour federal minimum wage.
State the purpose for the loan. #Set forth the amount and terms of the loan. Your agreement should clearly state the amount of money you're lending your friend, the interest rate, and the total amount your friend will pay you back.
A 'perquisite' is a benefit offered by the employer to an employee based on his job designation. Such a benefit is considered under the head 'Salary' for tax purposes. Similarly, an interest-free or concessional loan provided by an employer is taxable as a 'perquisite' for an employee.
A loan agreement is the document in which a lender usually a bank or other financial institution sets out the terms and conditions under which it is prepared to make a loan available to a borrower.
Starting the Document. Write the date at the top of the page. Write the Terms of the Loan. State the purpose of the personal payment agreement and the terms for returning the money. Date the Document. Statement of Agreement. Sign the Document. Record the Document.
A salary, or wage, advance is a type of short-term loan from an employer to an employee. No taxes should come out of the actual advance, but you must withhold taxes from the repayment.This way, the employees' wages will be taxed as normal.