Loan Agreement for Family Member
Understanding this form
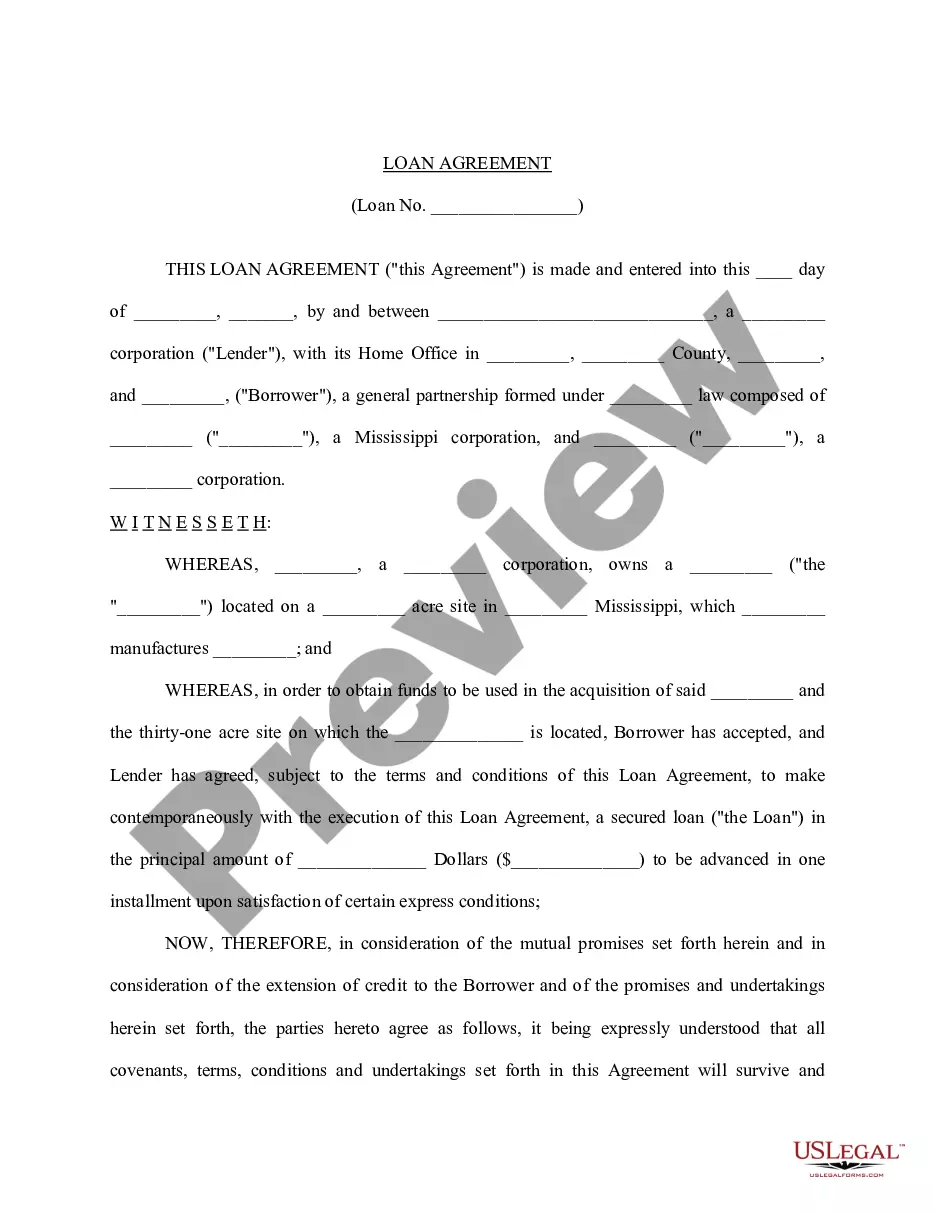
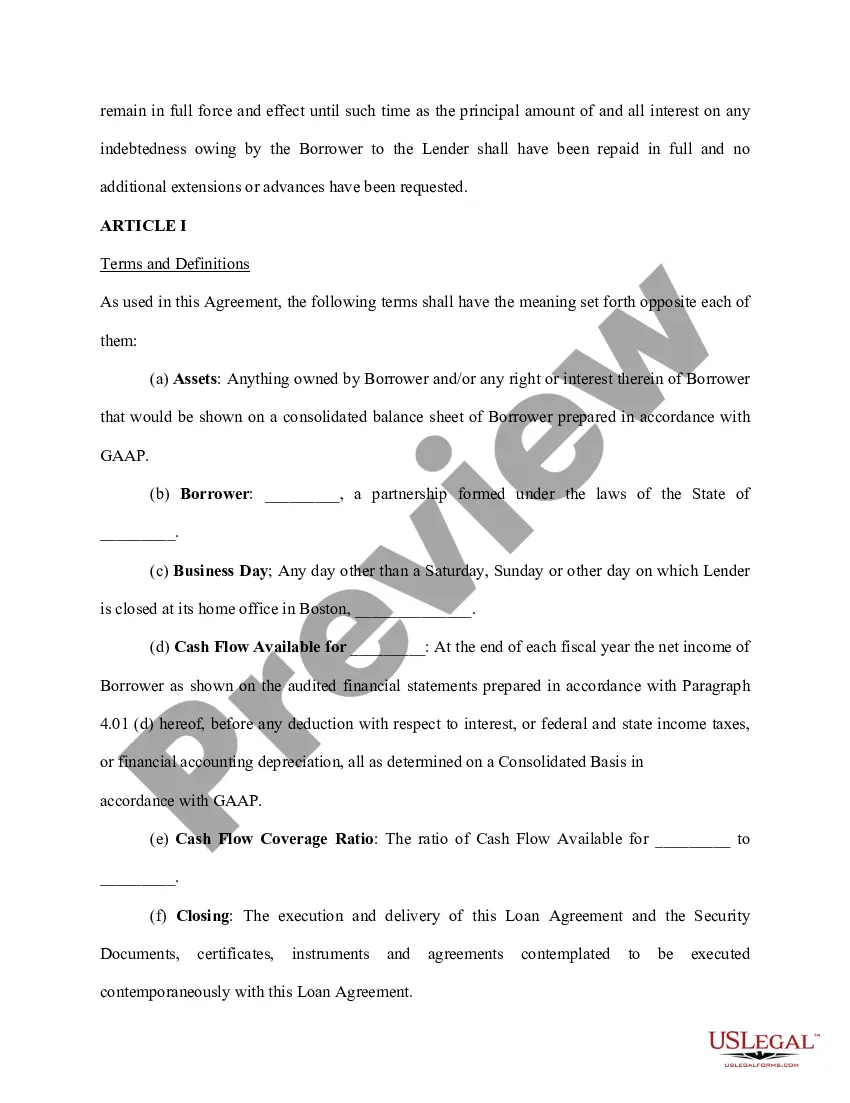
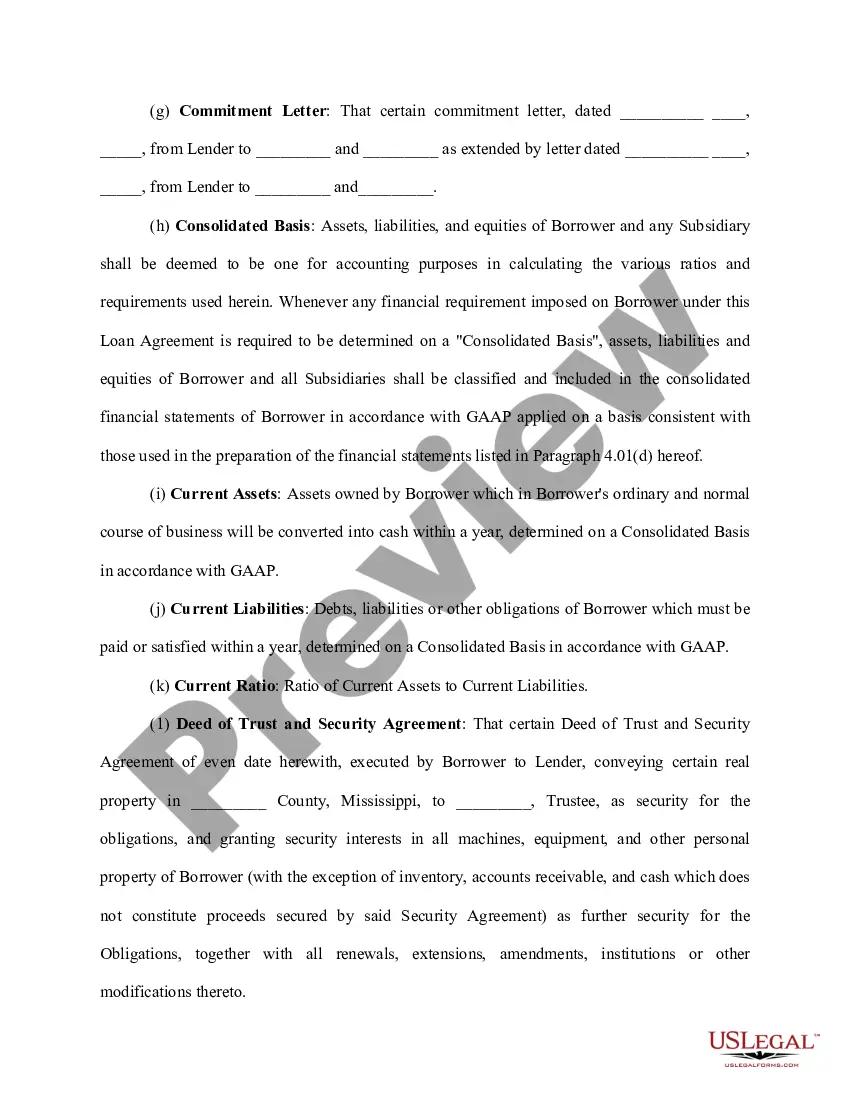
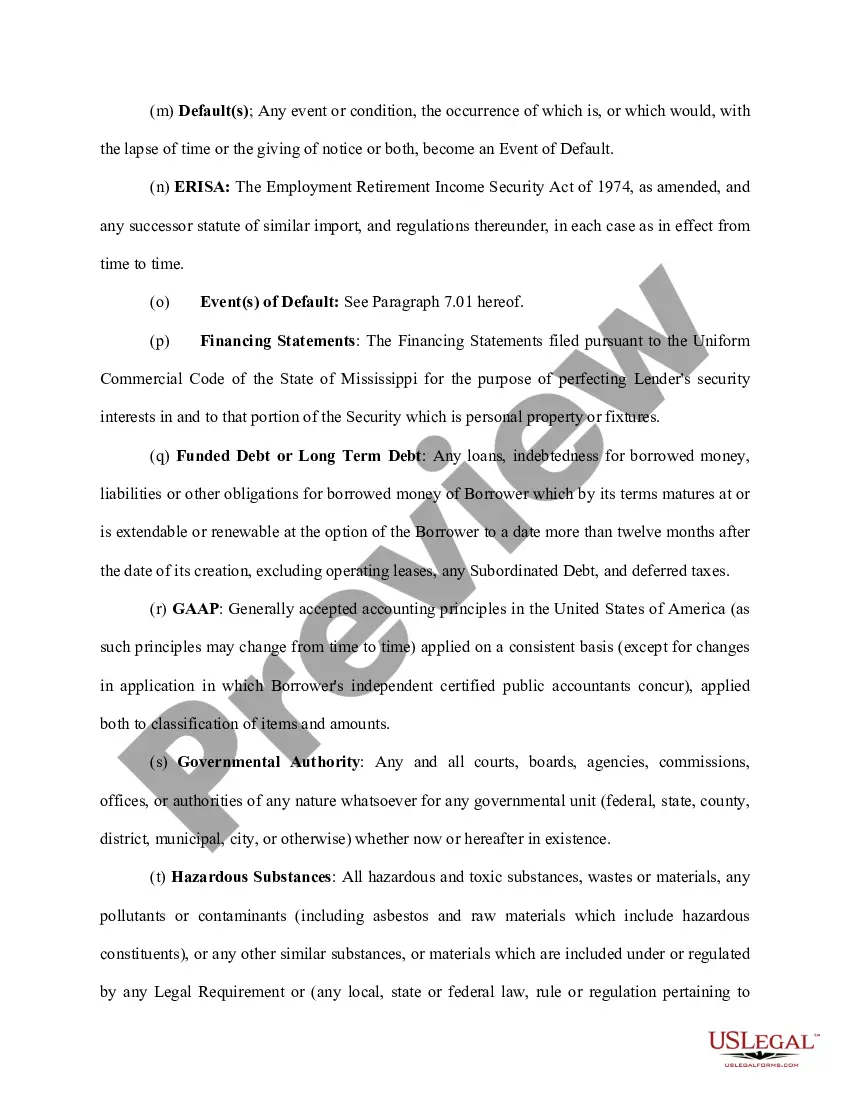
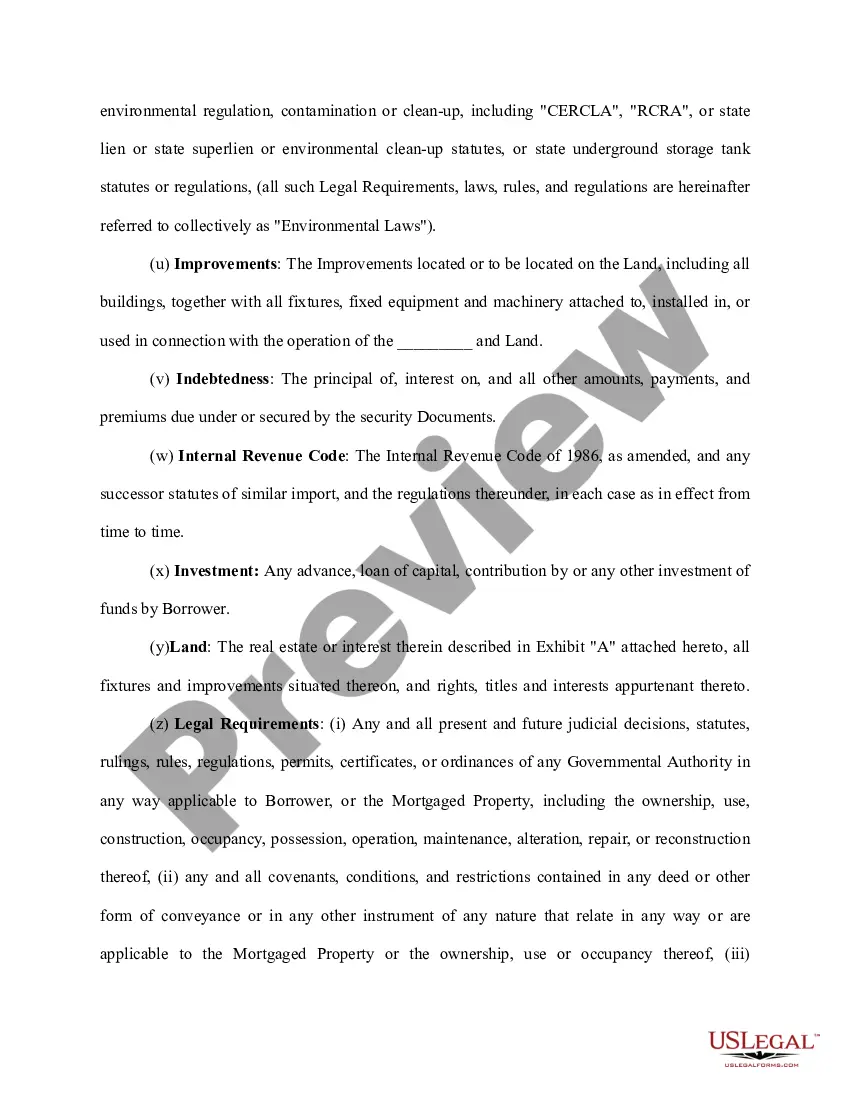
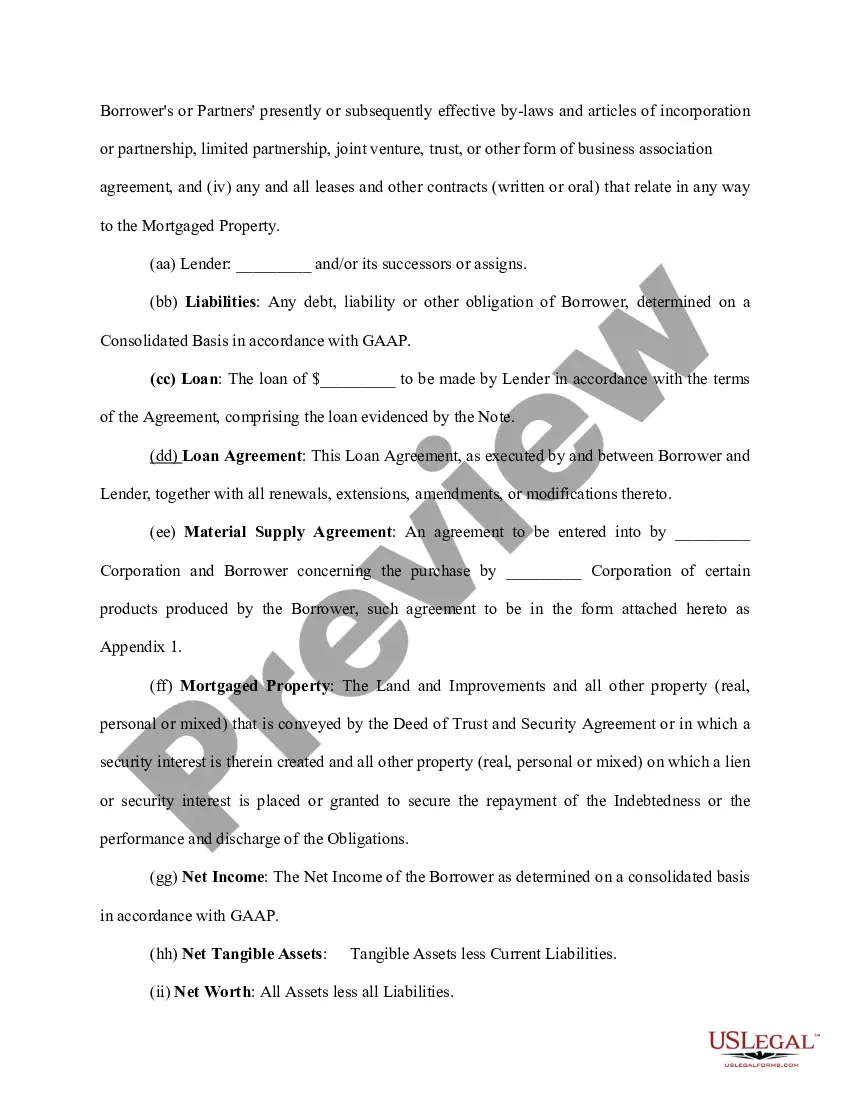
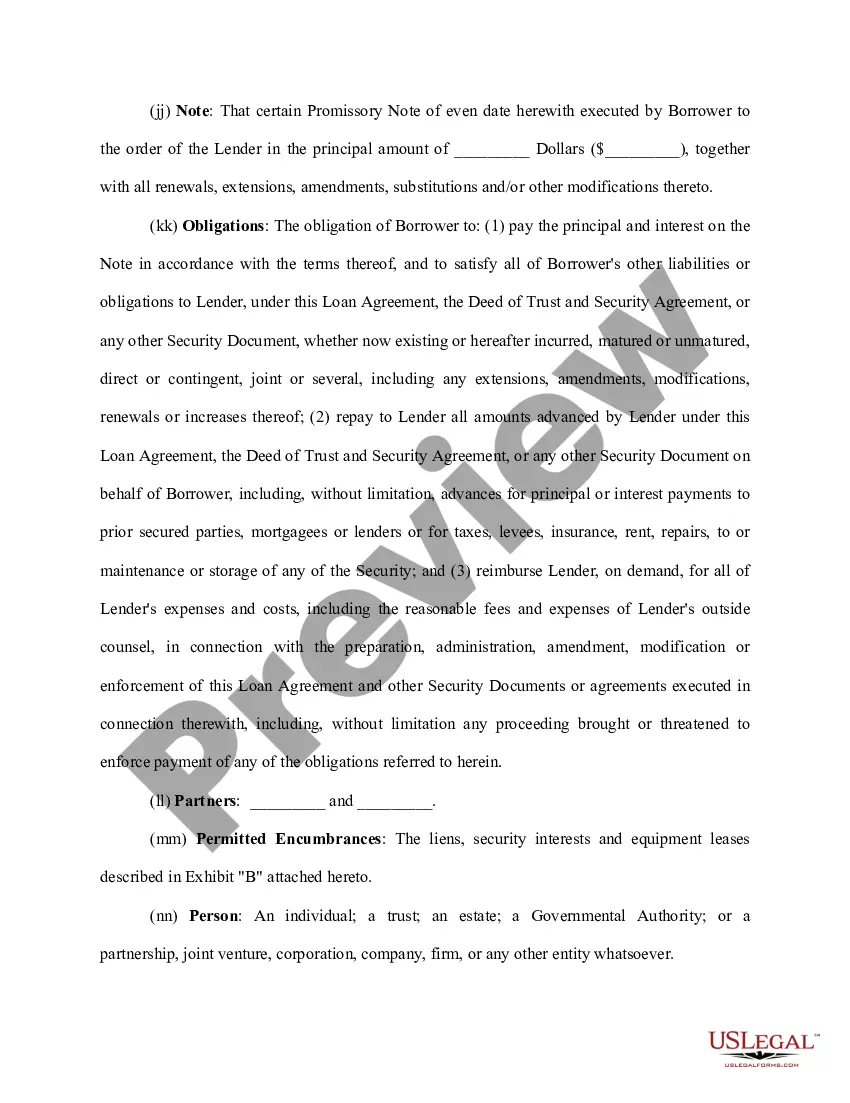
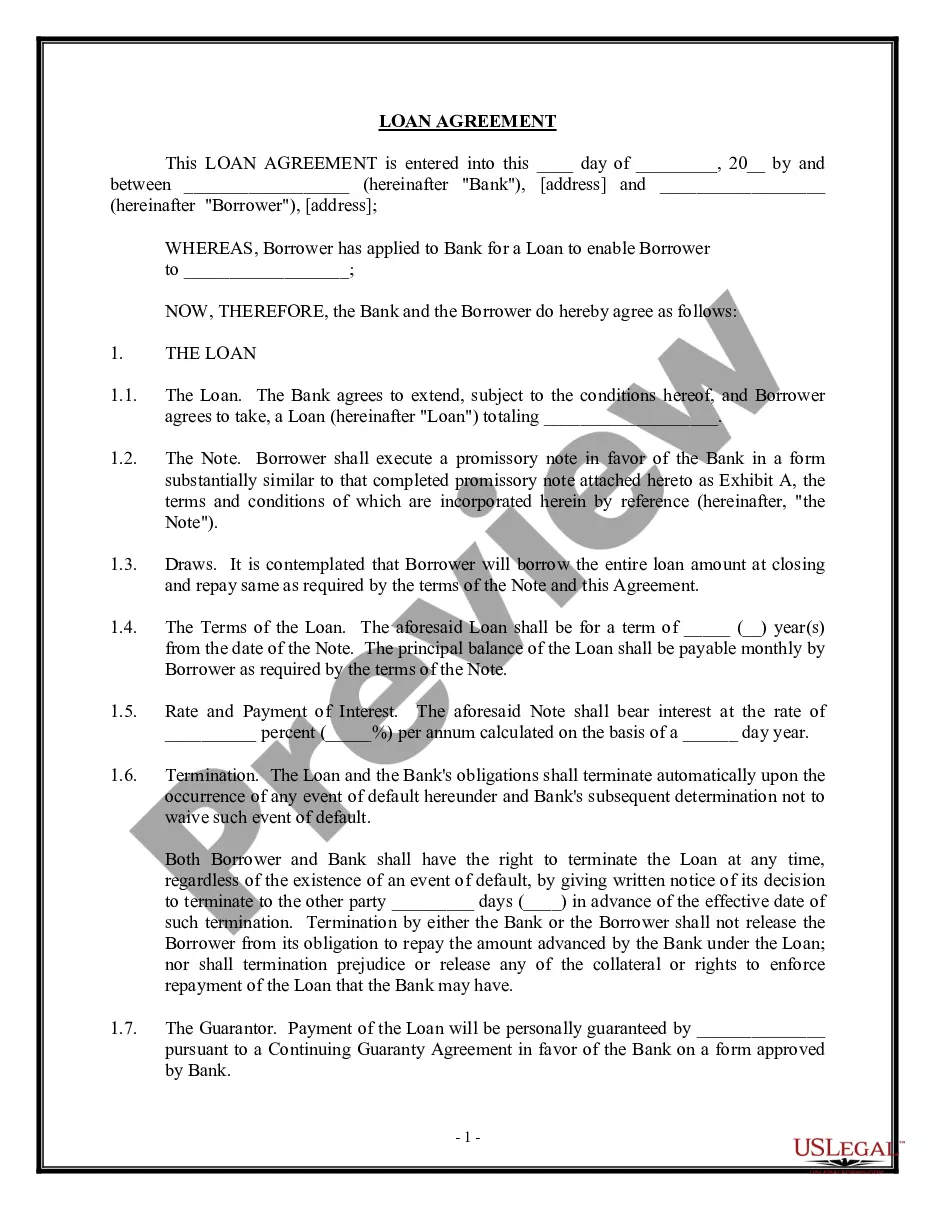
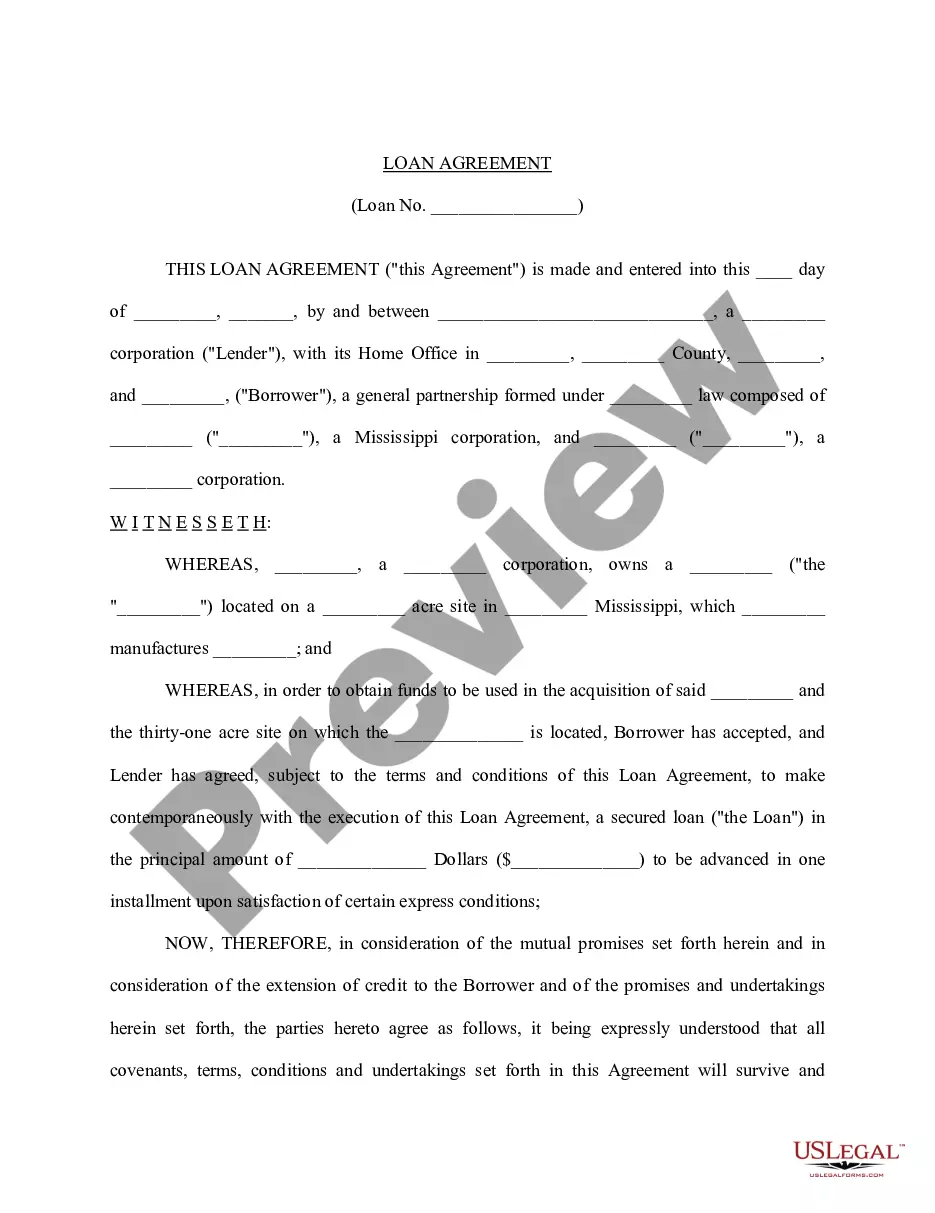
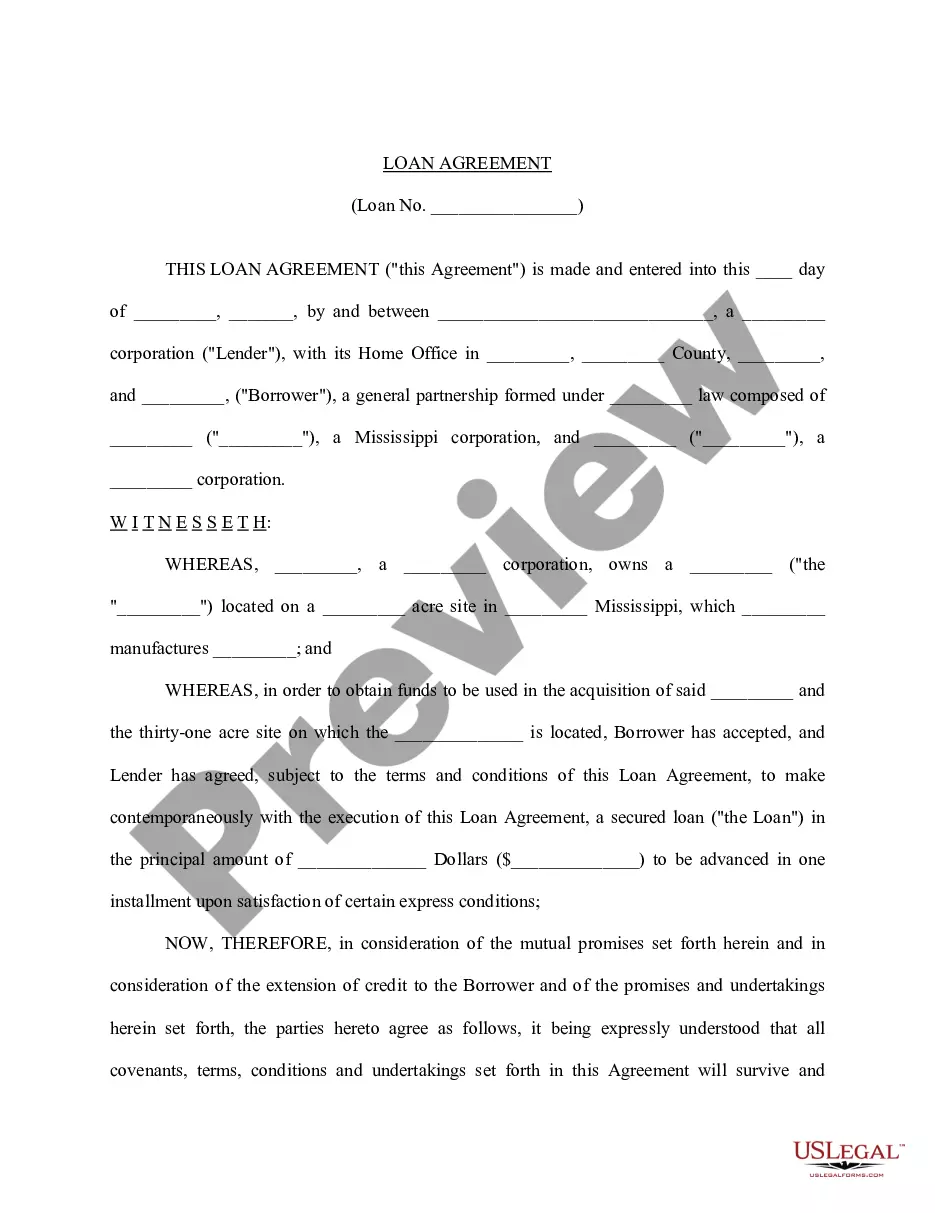
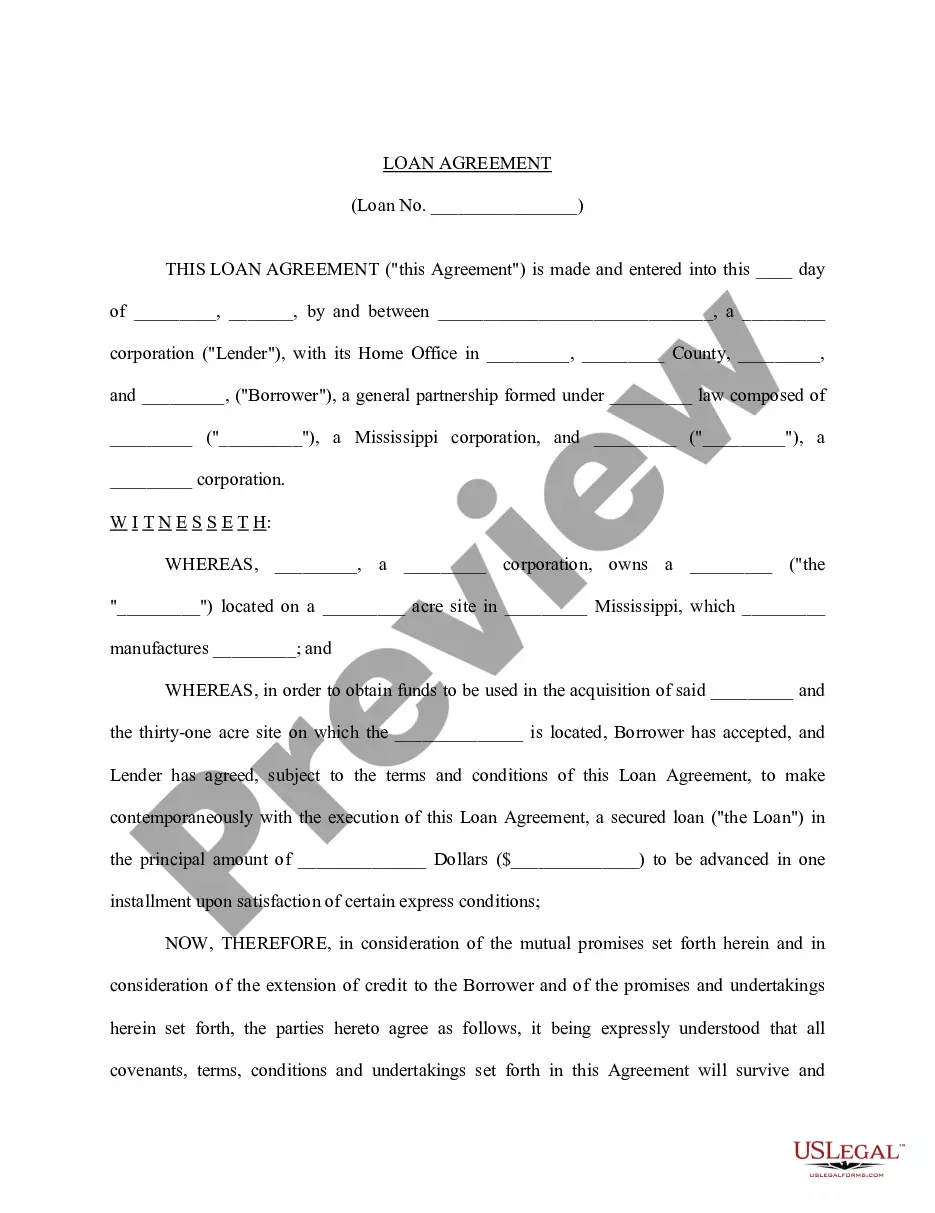
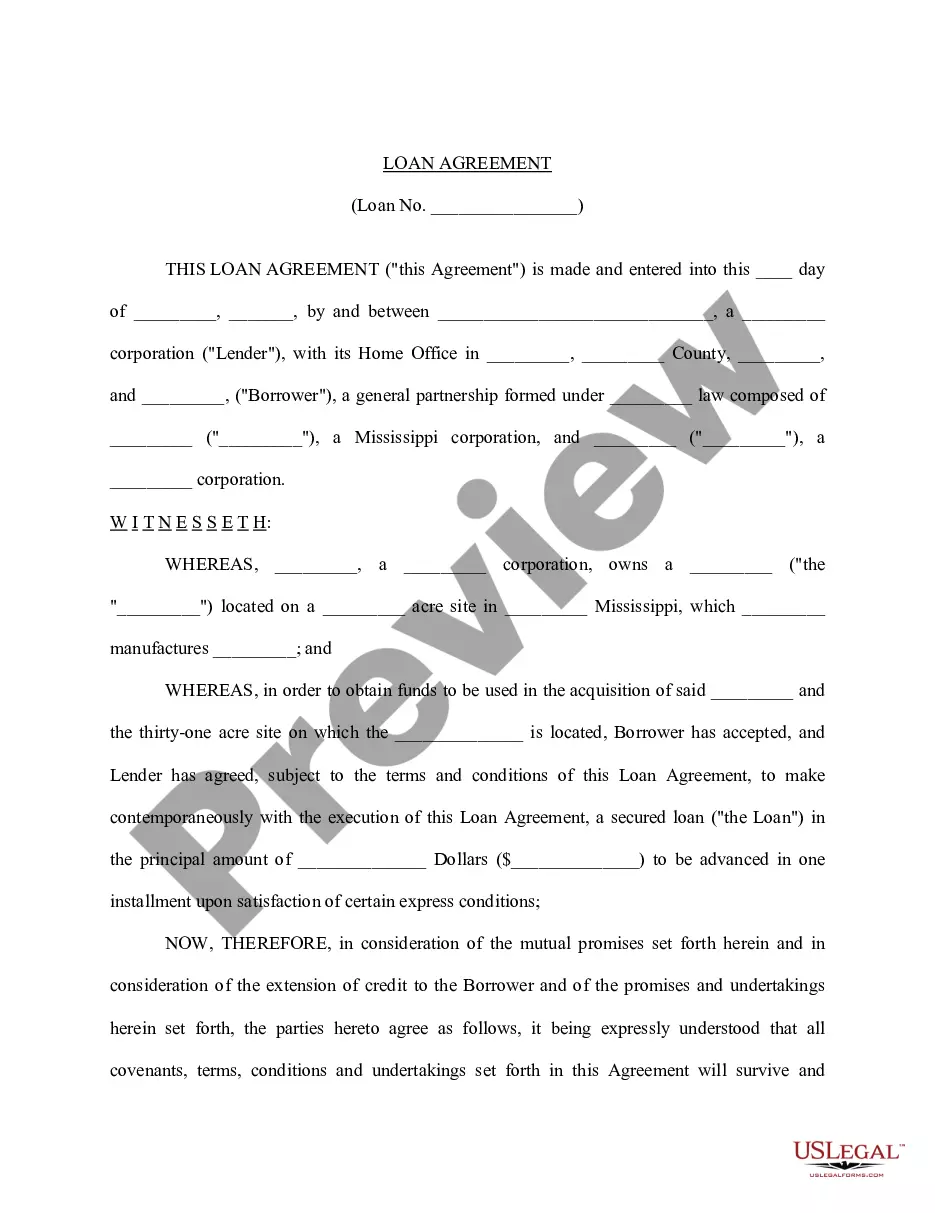
The Loan Agreement for Family Member is a legal document used between a lender and a borrower who are family members. This form outlines the terms of the loan, specifying the rights and responsibilities of both parties. Unlike informal loan arrangements, this agreement provides a clear structure that protects both individuals, ensuring transparency and legal standing for the transaction.
Form components explained
- Loan Amount: Specifies the total amount being borrowed.
- Interest Rate: Details the interest that the borrower agrees to pay on the loan.
- Repayment Terms: Outlines the timeline for repayment, including any specific intervals for payments.
- Default Conditions: States what constitutes a default and the consequences of non-payment.
- Signatures: Areas for both parties to sign, making the agreement legally binding.
Common use cases
This form is typically used when a family member wants to lend money to another family member. It can be applied in various situations such as helping a relative with buying a home, funding a business, or providing assistance during financial hardship. Utilizing this Loan Agreement helps establish clear expectations and terms, reducing the likelihood of misunderstandings in family financial matters.
Who needs this form
This Loan Agreement is suitable for:
- Family members engaging in financial transactions to ensure clear communication.
- Individuals seeking to formalize a loan to protect themselves legally.
- Those wanting to avoid discrepancies that can arise from informal agreements.
Steps to complete this form
- Identify the parties involved, including the lender and borrower.
- Enter the total loan amount and the applicable interest rate.
- Specify the terms of repayment, including due dates and payment amounts.
- List conditions regarding default and any consequences.
- Both parties must sign and date the agreement to finalize it.
Notarization guidance
This form does not typically require notarization unless specified by local law. Check your local regulations to confirm whether notarization is necessary for your agreement.
Get your form ready online
Our built-in tools help you complete, sign, share, and store your documents in one place.
Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.
Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.
Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.
If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.
We protect your documents and personal data by following strict security and privacy standards.

Make edits, fill in missing information, and update formatting in US Legal Forms—just like you would in MS Word.

Download a copy, print it, send it by email, or mail it via USPS—whatever works best for your next step.

Sign and collect signatures with our SignNow integration. Send to multiple recipients, set reminders, and more. Go Premium to unlock E-Sign.

If this form requires notarization, complete it online through a secure video call—no need to meet a notary in person or wait for an appointment.

We protect your documents and personal data by following strict security and privacy standards.
Avoid these common issues
- Failing to specify the interest rate clearly.
- Not including a timeline for repayment.
- Omitting signatures from both parties.
- Neglecting to state the consequences of default.
Benefits of completing this form online
- Convenience of downloading and filling out the form at your own pace.
- Editable fields allow for customization to meet specific needs.
- Increased reliability by using a professionally drafted template.
Looking for another form?

Form popularity
FAQ
Total amount of money being loaned. Date of the loan. How the loan was delivered (cash, check, direct deposit) The name and address of the person loaning the money. The name and address of the person borrowing the money.
Ask for a plan. Review the borrower's finances and help them set up a budget that includes your monthly repayment. Make sure they understand this is a loan, not a gift. Set terms that both sides agree can be enforced 2026 and enforce them! Keep your distance. Get it down on paper.
Starting the Document. Write the date at the top of the page. Write the Terms of the Loan. State the purpose of the personal payment agreement and the terms for returning the money. Date the Document. Statement of Agreement. Sign the Document. Record the Document.
Come up with a schedule for repayment. Use a family contract template that includes a repayment schedule. Set and interest rate. Put your agreement in writing. Keep payment records.
Starting the Document. Write the date at the top of the page. Write the Terms of the Loan. State the purpose of the personal payment agreement and the terms for returning the money. Date the Document. Statement of Agreement. Sign the Document. Record the Document.
If you've got the financial means, you may want to consider giving money to family members with no strings attached. For 2019, family members can give up to $15,000 per individual giftee without triggering gift tax laws.
You can take a tax deduction for a nonbusiness bad debt if: The money you gave your nephew was intended as a loan, not a gift. You must have actually loaned cash to your nephew.
If you've got the financial means, you may want to consider giving money to family members with no strings attached. For 2019, family members can give up to $15,000 per individual giftee without triggering gift tax laws.